Introduction
Commercial Paper (CP) is an unsecured, short-term debt instrument issued by corporations, financial institutions, and other large entities to finance immediate operational needs such as inventory and accounts payable. It is a widely used money market instrument that serves as an alternative to bank loans for short-term funding requirements. CPs provide companies with a flexible and cost-effective means of raising funds while offering investors a relatively safe investment with better returns compared to traditional savings instruments.
History and Evolution of Commercial Paper
NABARD 2021-2024 Cutoff Analysis | What we can Learn? #nabard_grade_a_exam #nabard_cutoffTap to play · from the C4S channel
Commercial Paper was first introduced in the United States in the 19th century and has since evolved into a vital financial instrument across the globe. In India, CP was introduced in 1990 to provide an additional short-term borrowing avenue for highly rated corporate entities. Over the years, the CP market has grown significantly, fueled by increasing corporate financing needs and regulatory support.
A clean PDF of this page with the C4S header — it opens right away, and the link comes to your WhatsApp too.
Key Features of Commercial Paper
- Tenure:
- Typically issued for maturities ranging from 7 days to 1 year.
- Denomination:
- Generally issued in multiples of ₹5 lakh or more.
- Issuers:
- Corporations, financial institutions, and primary dealers.
- Investors:
- Mutual funds, banks, insurance companies, pension funds, and other institutional investors.
- Issuance Mode:
- Issued in dematerialized form and traded electronically.
- Security:
- Unsecured, making it riskier than secured debt instruments.
- Credit Ratings:
- Must have a high credit rating from agencies like CRISIL, ICRA, and CARE.
Current Status of Commercial Paper Market in India (2024-2025)
As of February 2025, the Indian CP market is witnessing notable trends:
- Record Bond Issuance:
- In 2024, Indian corporations raised ₹10.67 trillion through corporate bonds, a 9% increase from 2023. The CP segment, however, has seen fluctuations due to regulatory scrutiny.
- RBI Oversight:
- The Reserve Bank of India (RBI) has increased scrutiny on Non-Banking Financial Companies (NBFCs), leading to a slowdown in CP issuance.
- Shift to Long-Term Debt:
- Many corporations are shifting towards long-term bonds due to declining yields and better stability.
- Liquidity Concerns:
- The RBI has announced measures to enhance liquidity in response to tax outflows, which may impact CP issuance.
Comparison with Certificates of Deposit (CDs)
While Commercial Paper and Certificates of Deposit (CDs) serve similar purposes, they differ in several aspects:
| Feature | Commercial Paper (CP) | Certificate of Deposit (CD) |
|---|---|---|
| Issuer | Corporations, financial institutions | Banks and financial institutions |
| Security | Unsecured | Secured by the bank issuing it |
| Maturity | 7 days to 1 year | 3 months to 5 years |
| Investor Type | Institutional investors, mutual funds | Institutional and retail investors |
| Regulatory Body | RBI, SEBI | RBI |
| Risk Level | Higher due to no collateral | Lower due to bank guarantee |
| Liquidity | High | High, but depends on secondary market demand |
Advantages of Commercial Paper
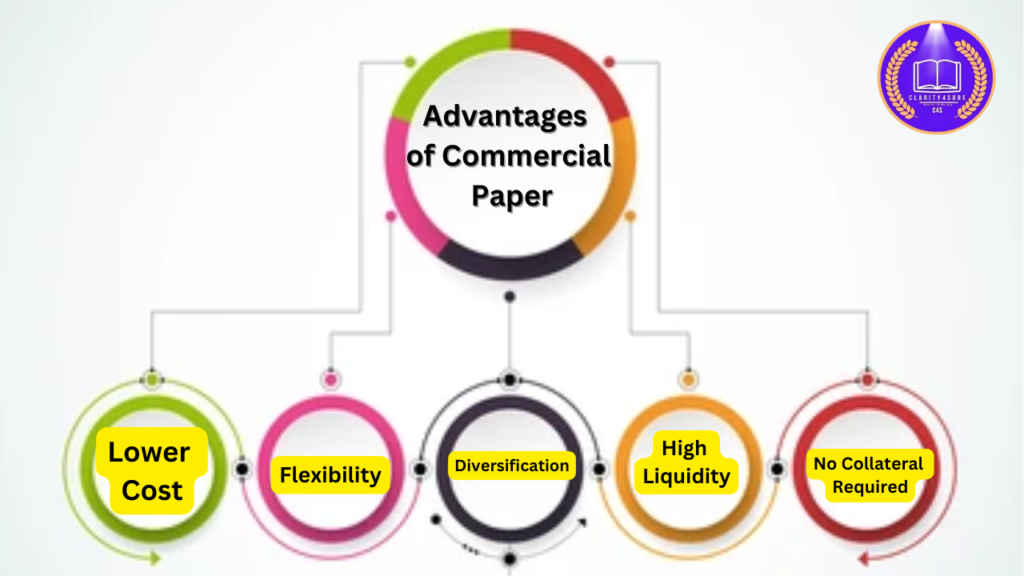
- Lower Cost:
- Generally offers a lower interest rate compared to traditional bank loans.
- Flexibility:
- Allows corporations to raise funds quickly without lengthy procedures.
- Diversification:
- Helps companies diversify their borrowing sources.
- High Liquidity:
- Easily tradable in the secondary market.
- No Collateral Required:
- Being unsecured, there is no need to pledge assets.
- Efficient Short-Term Financing:
- Ideal for companies needing quick funding without long-term debt commitments.
Disadvantages of Commercial Paper
- Credit Risk:
- Since it is unsecured, it carries higher default risk.
- Limited Accessibility:
- Only large, creditworthy firms can issue CP.
- Market Volatility:
- Interest rates can fluctuate, impacting issuance costs.
- Short-Term Nature:
- Not suitable for long-term financing needs.
- Regulatory Restrictions:
- Issuance depends on the credit rating and financial health of the issuer.
Statistical Overview of the CP Market
| Metric | 2023 | 2024 | Growth (%) |
|---|---|---|---|
| Total Corporate Bond Issuance (₹ Trillion) | 9.79 | 10.67 | 9% |
| CP Issuance in First Half of October (₹ Billion) | Data Not Available | Declined | – |
| Average Yield on CPs (%) | Data Not Available | Data Not Available | – |
(Source: RBI, SEBI, and Financial Reports)
Regulatory Framework for Commercial Paper in India
The issuance and trading of CP in India are regulated by the Reserve Bank of India (RBI) and Securities and Exchange Board of India (SEBI). Some key regulations include:
- Eligibility Criteria:
- Only corporates with a minimum credit rating of A3 can issue CPs.
- Limits on Issuance:
- CPs cannot exceed the issuer’s working capital limit.
- Mode of Issuance:
- Must be issued in dematerialized form.
- End-Use Restrictions:
- Cannot be used for speculative purposes.
- Disclosure Requirements:
- Issuers must disclose financial health, utilization of proceeds, and credit rating in public filings.
Recent Trends and Future Outlook
Recent Trends (2023-2024)
- Declining CP Issuance:
- Regulatory concerns and a preference for long-term debt have impacted CP demand.
- Higher Demand from Mutual Funds:
- Institutional investors are shifting towards CPs with higher credit ratings.
- Rising Interest Rates:
- Borrowing costs have increased, leading to a cautious approach by issuers.
Future Outlook (2025-2026)
- Regulatory Clarity:
- Improved guidelines may stabilize the market.
- Liquidity Enhancement Measures:
- RBI’s policy adjustments could boost CP issuance.
- Growing Role of Digital Platforms:
- Electronic platforms are enhancing transparency and ease of trading.
- Integration with Fintech:
- The adoption of blockchain and AI in financial markets may further streamline CP transactions.
Conclusion
Commercial Paper remains a crucial financial instrument for short-term corporate financing. While recent regulatory scrutiny has slowed issuance, the market is expected to stabilize with policy refinements. A comparison with Certificates of Deposit (CDs) highlights the differences in risk, security, and investor profiles. Investors and issuers must stay informed about market trends and regulatory changes to make well-informed financial decisions.
References
- Reserve Bank of India (RBI) Reports
- Securities and Exchange Board of India (SEBI) Guidelines
- Market Analysis from Financial Journals