Clarity 4 Sure · Revision Sheet
September 2025 — exam-ready facts
397 items from 23 days · NABARD Grade A · RBI Grade B · SEBI Grade A
Names, numbers and tables only — the narrative is stripped out. Prints two columns to a page. For the full write-up of any item, open the full version.
Want this month’s PDF on WhatsApp?
Tap below — WhatsApp opens with the message already written. Just press Send and the link arrives straight away.
Get the September 2025 revision sheet on WhatsAppFree live session
NABARD Grade A 2026: what the 2025 cut-offs changed, and the 90-day plan
The 2025 cycle was the toughest on record at every stage. This session reads those numbers properly and turns them into a week-by-week plan for Phase 1.
In 2 days · Sun, 27 Sep at 7:30 PM IST · 75 minutes · free
23days covered
397topics
18topics a day
7hto revise once
1
Cover the right column
Read only the topic name and try to recall the facts before you look.
2
Mark what you missed
Anything you could not recall is what the exam will find first.
3
Write one answer
Pick one topic and write 150 words on it. That is what converts marks.
60%Front Runners: >60% score
75%Priority Sector Lending (PSL): 75% of adjusted net bank credit must go to PSL categories.
₹5 lakhPMJAY (2018): Provides ₹5 lakh cover per household annually, covering 58.8 crore individuals…
₹1.5 trillionTo drain ₹1.5 trillion excess liquidity from the banking system.
50%At least 50% must be independent directors.
₹500 croreNet Worth: The applicant bank must have a minimum paid-up capital of ₹500 crore (may vary as…
21%Addresses the challenge of a rapidly aging population, projected to reach 21% of the populat…
₹83,000 croreObjective: The reform seeks to attract more foreign capital, particularly after significant…
₹30 lakhPooling of Assets Similar loans or receivables are grouped together into a pool to diversify…
$100 billionAdani Group companies lost over $100 billion in market capitalization within weeks.
1%Lumpsum investment: Incentive = 1% of the first application amount.
₹50,000Suppose you sold Stock A at a ₹50,000 loss and made a ₹70,000 profit from Stock B.
Pulled straight out of this month's own facts. If a figure here is new to you, go back and read that item in full.
International Affairs · 6
State Energy Efficiency Index (SEEI) 2024
- Objective: Drive data-backed policy action. Encourage inter-state competition. Support India’s net-zero 2070 vision.
- Coverage: 36 States/UTs, evaluated using 66 indicators across 7 sectors — Buildings, Industry, Transport, Agriculture, DISCOMs, Municipal Services, and Cross-sector initiatives.
- Front Runners: >60% score
- Achievers: 50–60%
Shanghai Cooperation Organisation (SCO)
- Established: 2001 (Shanghai), evolved from the Shanghai Five (1996).
- Headquarters: Beijing, China.
- Permanent Members (8): China, Russia, India, Pakistan, Kazakhstan, Kyrgyzstan, Tajikistan, Uzbekistan.
- Membership: Permanent Members (8): China, Russia, India, Pakistan, Kazakhstan, Kyrgyzstan, Tajikistan, Uzbekistan. Observers: Afghanistan, Belarus, Mongolia, Iran (progressing to full membership). Dialogue Partners: Turkey, Sri Lanka, Nepal, Egypt, Saudi Arabia, Qatar, etc.
Pradhan Mantri Viksit Bharat Rozgar Yojana (PMVBRY)
- Eligibility: First-time employees registered with EPFO, with salary up to ₹1 lakh.
- Benefit: One month’s EPF wage, up to ₹15,000, given in two instalments. 1st instalment: After 6 months of service. 2nd instalment: After 12 months of service + completion of a financial literacy programme.
- Eligibility: Employers hiring new employees with salaries up to ₹1 lakh.
- Benefit: Up to ₹3,000 per month per employee for 2 years.
Govt to Launch AI-Based Adivasi Language Translation App ‘Aadi Vaani’
- Aims to build a cadre of 20 lakh “change leaders” in tribal villages.
- Built on a database of 1 lakh+ sentences per language with the help of experts.
- Adi Seva Kendras to be set up in 1 lakh villages as single-window service centres for welfare schemes.
- The Ministry of Tribal Affairs has launched the Adi Karmayogi initiative under the Dharti Aba Janjatiya Gram Utkarsh Abhiyaan to create a cadre of 20 lakh “change leaders” for last-mile delivery of welfare schemes in tribal villages. The Adi Karmayogi Initiative was officially launched on August 19, 2025, by the Ministry of Tribal Affairs.
NASA Rover Finds Potential Sign of Ancient Life in Martian Rocks
- Location: Bright Angel rock formation in Jezero Crater, believed to be an ancient lake basin formed ~3.5 billion years ago.
- Landed: February 2021.
- On 10 September 2025, scientists reported that a rock sample collected by NASA’s Perseverance rover from Mars’ Jezero Crater shows potential signs of ancient microbial life, though non-biological processes cannot be ruled out. The findings were published in Nature journal.
- Mission Goal: Explore Jezero Crater, collect rock and regolith samples, and seek signs of ancient microbial life.
H-1B Visas
- Fee Impact: Increase from a few thousand dollars to $100,000 per applicant.
- Indian IT Companies: Major H-1B users (Infosys, Wipro, TCS) face higher compliance costs.
- Validity: 3 years, extendable to 6 years.
- Quota: 65,000 visas + 20,000 for US Master’s holders.
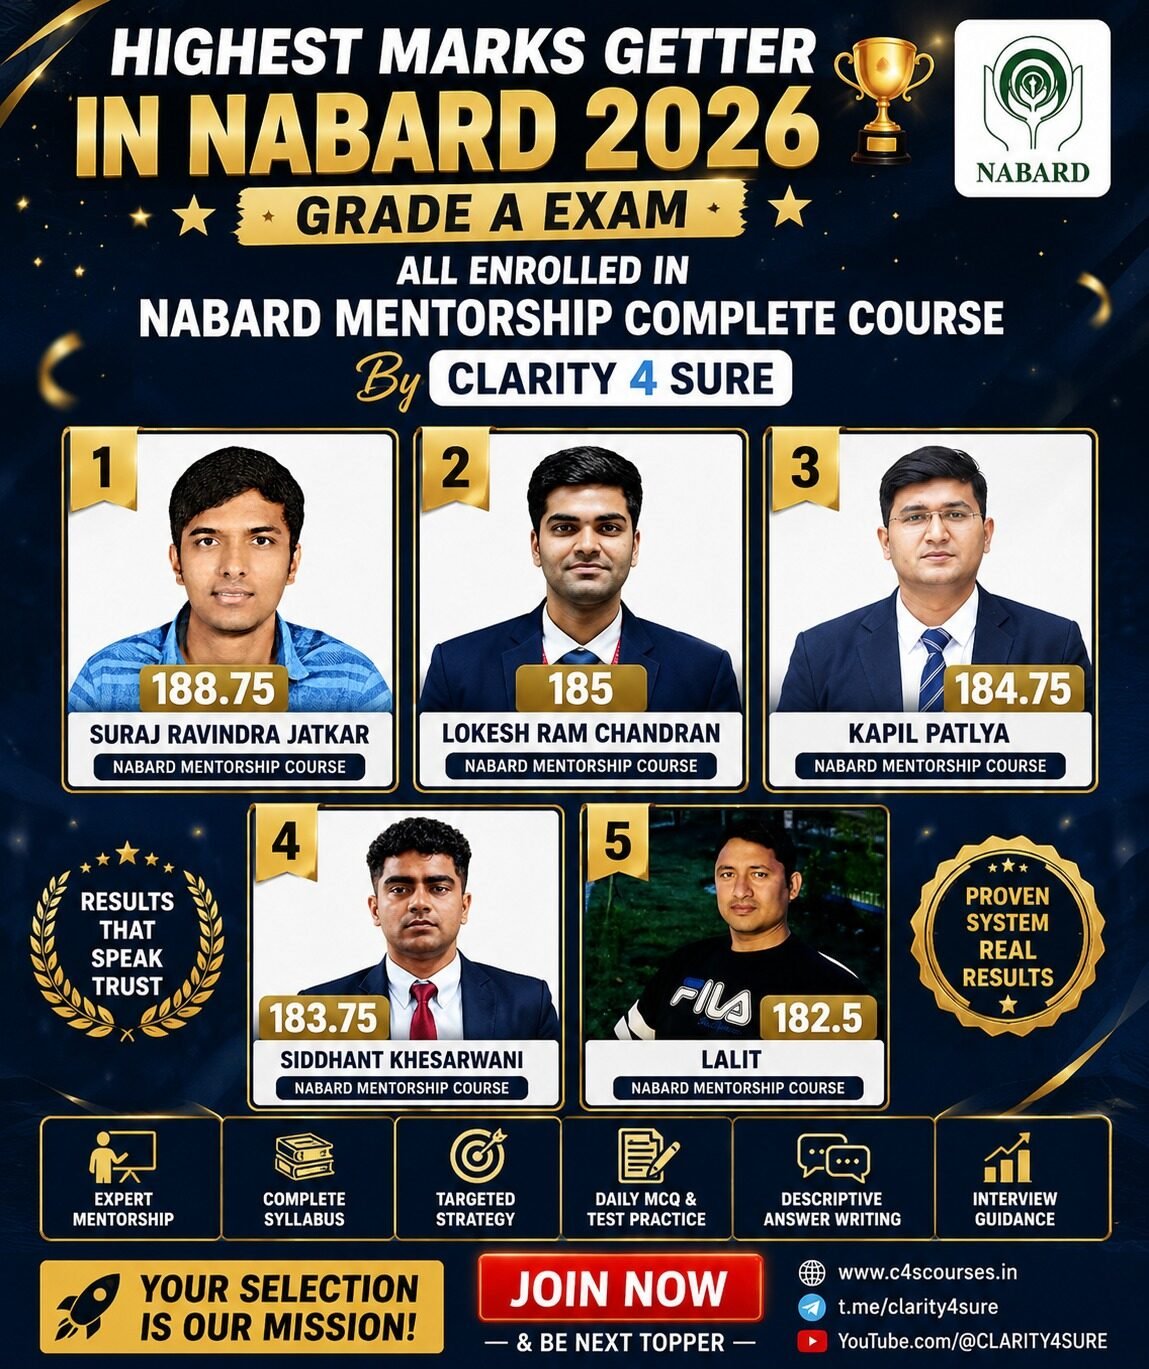
Results that speak
The six highest scorers in NABARD Grade A 2026 were all in one classroom
Every one of them was enrolled in the NABARD Mentorship Complete Course at Clarity 4 Sure. The same descriptive training and the same current affairs notes you are reading now.
- 1Suraj Ravindra Jatkar188.75
- 2Lokesh Ram Chandran185
- 3Vivek Kumar185
- 4Kapil Patlya184.75
- 5Siddhant Khesarwani183.75
- 6Lalit182.5
Banking/Finance · 130
RBI Data Shows Slow Credit and Deposit Growth in Rural India
- Went up from 56% in 2000 to 80% in 2025.
- Urban population increased from 28% in 2000 to 37% in 2024.
- Rural population reduced from 72% to 63% in the same period.
- RBI’s latest data highlights that Scheduled Commercial Banks (SCBs) have struggled to mobilise deposits and expand lending in rural India (“Bharat”) compared to semi-urban, urban, and metropolitan areas over the last 25 years.
| Aspect | Details |
|---|---|
| Meaning | Banks listed in the Second Schedule of the RBI Act, 1934. |
| Facilities Available | Eligible to borrow from RBI, use clearinghouse facilities, and access liquidity support. |
| Types Included | 1. Public Sector Banks 2. Private Sector Banks 3. Foreign Banks in India 4. Regional Rural Banks (RRBs) |
| Eligibility (Section 42(6), RBI Act, 1934) | - Capital Requirement: Minimum paid-up capital & reserves of ₹5 lakh (practically higher required). - Depositor Safety: Should not conduct business harmful to depositors. - Affairs Management: Must be in the interest of depositors and the public. - Compliance: Must satisfy RBI that it can follow RBI Act & Banking Regulation Act. |
RBI Likely to Approve Fino Payments Bank’s Conversion to Small Finance Bank
- Priority Sector Lending (PSL): 75% of adjusted net bank credit must go to PSL categories.
- Promoters: Individuals or professionals with at least 10 years’ experience in banking/finance, and entities like NBFCs, MFIs, and Local Area Banks (LABs).
- Foreign Shareholding: Allowed as per FDI policy for private banks (up to 74%).
- Minimum Capital: ₹200 crore paid-up capital at the time of licensing.
| Feature | Scheduled Commercial Banks (SCBs) | Small Finance Banks (SFBs) |
|---|---|---|
| Definition | Banks listed in the Second Schedule of RBI Act, 1934; includes Public, Private, Foreign, and RRBs. | A type of Scheduled Bank focused on financial inclusion for underserved sections. |
| Scope of Operations | Universal banking – can serve all segments (corporates, retail, MSMEs, rural, urban, international). | Primarily serve small borrowers, MSMEs, farmers, low-income groups. |
| Priority Sector Lending (PSL) | Must lend at least 40% of ANBC to PSL. | SFBs must allocate at least 60% of their ANBC (or Credit Equivalent of Off-Balance Sheet Exposures, whichever is higher) to priority sectors. |
| Branch Requirement | No specific rural mandate (but regulated by RBI norms). | At least 25% of branches must be in unbanked rural areas. |
| Examples | SBI, HDFC Bank, ICICI Bank, RRBs, etc. | AU SFB, Equitas SFB, Ujjivan SFB, Jana SFB, etc. |
| Capital Requirement | Higher; varies depending on bank type (Private, Public, RRBs). | Minimum ₹200 crore paid-up capital (at licensing). |
| Nature | Broad-based, covers the entire economy. | Specialized, focused on financial inclusion. |
RBI Imposes Penalty on Bandhan Bank
- Penalty imposed under powers conferred by Section 47A(1)(c) read with Section 46(4) of the Banking Regulation Act, 1949.
- Statutory Basis: Penalty imposed under powers conferred by Section 47A(1)(c) read with Section 46(4) of the Banking Regulation Act, 1949. Violations included breach of Section 10(1)(b)(ii) of the Act and RBI’s September 14, 2020 circular on automation of income recognition, asset classification and provisioning.
- Violations included breach of Section 10(1)(b)(ii) of the Act and RBI’s September 14, 2020 circular on automation of income recognition, asset classification and provisioning.
- 46(4): Defines the maximum penalty amount (₹1 crore + ₹50,000/day for continuing default).
SEBI’s Cybersecurity Framework to Ease Burden
- Large entities (e.g., top brokers, clearing members, depositories): Must comply with stringent cybersecurity controls and strict timelines due to their higher systemic risk.
- Small entities (small brokers, portfolio managers, RIAs, etc.): Simplified norms and extended timelines to reduce operational burden.
- Protect investors’ data and market infrastructure.
Unit Linked Insurance Plans (ULIPs)
- Premium ≤ 10% of the sum assured (for policies issued after April 1, 2012).
- They have a lock-in period of 5 years, but long-term holding is advised for wealth creation.
- Annual premium ≤ ₹2.5 lakh.
- This applies uniformly to ULIPs, including those issued before February 1, 2021, ending earlier confusion over tax treatment.
Foreign Investors Pull Out ₹34.99 Crore from Indian Equities
- Global factor: US tariffs of up to 50% on Indian exports hurt sentiment.
- Corporate earnings: Weaker-than-expected Q1FY26 results in some sectors.
- Foreign Portfolio Investors (FPIs) withdrew ₹34,993 crore (~$4 billion) from Indian equities in August 2025, the sharpest sell-off in six months. The move was triggered by steep US tariffs on Indian exports, high domestic valuations, and disappointing Q1 corporate earnings in some sectors.
- FPIs are overseas investors who invest in Indian stocks, bonds, or mutual funds for short- to medium-term gains.
Deutsche Bank Plans to Exit Indian Retail Banking
- Section 12B → RBI approval needed for acquisition of more than 5% stake in a bank.
- Banking Regulation Act, 1949 Section 44A → Deals with voluntary amalgamation/transfer of banking business. Section 35B → Requires RBI’s prior approval for certain management decisions (including transfers). Section 12B → RBI approval needed for acquisition of more than 5% stake in a bank.
- Foreign Exchange Management Act (FEMA), 1999 Foreign banks must comply with FEMA norms while selling/disposing assets in India.
- RBI Guidelines on Amalgamation of Private Sector Banks (2016) Even if only a portfolio or branch is transferred, the acquiring bank must satisfy RBI’s “fit and proper” criteria.
| Retail Banking | Corporate Banking |
|---|---|
| Serves individuals and households | Serves companies, firms, large institutions |
| Products: savings accounts, home loans, credit cards | Products: business loans, working capital, trade finance, treasury services |
| Many small customers | Few large customers |
RBI Update on Withdrawal of ₹2000 Banknotes
- The Reserve Bank of India (RBI) announced the withdrawal of ₹2000 denomination banknotes on May 19, 2023. RBI periodically updates the status of returned notes. As of August 31, 2025, almost all ₹2000 notes have been returned.
- ₹2000 note was introduced in November 2016 (post-demonetisation) to quickly meet currency needs.
- RBI Act, 1934
- Section 24: RBI’s power to determine denominations.
| Source of Income | Explanation | Example |
|---|---|---|
| Seigniorage (Currency Issuance) | Profit earned from issuing currency at face value higher than printing cost | Printing a ₹500 note costs ~₹5, but RBI issues at ₹500 → profit = ₹495 |
| Investment in Foreign Assets | Earnings from interest on foreign exchange reserves invested in safe securities | US Treasury bonds, Euro Govt bonds |
| Government Securities (Domestic) | Interest income from GoI bonds & Treasury bills held by RBI | Holding G-Secs bought during OMO operations |
| Lending to Banks (Repo/MSF) | Interest earned from short-term lending to commercial banks | Repo rate lending to SBI, HDFC Bank |
| Government Debt Management Fees | Commission for managing central & state govt borrowings | Issuing and servicing G-Secs on behalf of Govt |
| Banking Services Fees | Charges for providing settlement and payment systems | RTGS/NEFT transactions, cheque clearing |
| Other Investments (Gold, Bonds) | Returns from gold reserves & other financial instruments | Income from RBI’s gold holdings |
India’s Current Account Deficit
- FEMA, 1999 (Foreign Exchange Management Act) → Governs foreign exchange and external payments.
- RBI Act, 1934 → RBI manages forex reserves & balance of payments.
- Customs Act, 1962 → Governs import duties affecting trade balance.
- The Reserve Bank of India (RBI) reported that India’s current account deficit (CAD) fell sharply to $2.4 billion (0.2% of GDP) in Q1FY26 (April–June 2025), compared to $8.6 billion (0.9% of GDP) in Q1FY25. This came after a current account surplus of $13.5 billion (1.3% of GDP) in Q4FY25.
| Positive (Short-term) | Negative (Long-term) |
|---|---|
| Can support domestic consumption & growth via imports (oil, machinery) | Weakens rupee (depreciation pressure) |
| Indicates demand for capital goods (industrial growth) | Higher external debt as CAD financed by borrowing |
| May attract FDI/FPI to finance gap | Rising inflation (imported oil & goods) |
| Shows integration with global economy | Reduces forex reserves if persistent |
India’s Path to Universal Health Care (UHC)
- PMJAY (2018): Provides ₹5 lakh cover per household annually, covering 58.8 crore individuals (2023–24).
- Combined Annual Expenditure: ~₹28,000 crore, rising 8–25% (2018–2024).
- Utilisation Gap: Despite wide coverage, only 35% of insured hospital patients could use schemes (HCES 2022–23).
- Raise public health spending to 2.5% of GDP as per National Health Policy 2017 target.
External Commercial Borrowings (ECBs) in India
- RBI Act, 1934 – Empowers RBI to regulate external borrowings and foreign exchange.
- Loans raised by Indian corporates from foreign lenders in foreign currency, regulated under FEMA, 1999.
- Policy Framework under FEMA, 1999 Issues ECB Master Directions. Decides which sectors, borrowers, and lenders are eligible.
- Foreign Exchange Management Act (FEMA), 1999 – Legal basis for ECB regulation.
Government’s Draft Norms Ease Compliance for Foreign Investment in Insurance Sector
- Proposed wording change: Replace “to exceed 74% of paid-up equity capital” with “to exceed the limit as stipulated by the Insurance Act, 1938.” Seen as a precursor to raising the FDI cap to 100%, as announced in the Union Budget.
- Replace “to exceed 74% of paid-up equity capital” with “to exceed the limit as stipulated by the Insurance Act, 1938.”
- These conditions, experts noted, had earlier deterred global investors even after the FDI cap was raised from 49% to 74% in 2021.
- The government has issued draft amendments to the Indian Insurance Companies (Foreign Investment) Amendment Rules, 2015, aimed at reducing compliance hurdles and making India’s insurance sector more attractive to global investors.
SEBI Introduces Intraday Position Framework for Equity Index Options
- Equity Index Options are derivative contracts that allow traders to take positions on stock indices (like Nifty 50, Bank Nifty) without buying or selling the actual stocks.
- Regulatory Vigilance: Triggered by Jane Street case, where SEBI alleged market manipulation in Bank Nifty options worth ₹4,843.57 crore gains.
- Net Intraday Position Limit: ₹5,000 crore (up from existing end-of-day ₹1,500 crore).
- Earlier Rule: No intraday cap; only an end-of-day limit of ₹1,500 crore applied.
| Parameter | Net Intraday Position Limit | Gross Intraday Position Limit |
|---|---|---|
| Definition | Overall directional exposure (long or short) after adjusting for offsetting positions | Total exposure on both buy and sell sides without netting opposite positions |
| How Calculated | Long positions – Short positions | Long positions + Short positions |
| Example | ₹7,000 cr long – ₹2,000 cr short = ₹5,000 cr net long | ₹7,000 cr long + ₹2,000 cr short = ₹9,000 cr gross |
| SEBI Cap | ₹5,000 crore per entity (on Futures Equivalent / delta basis) | ₹10,000 crore per side (buy and sell separately) |
| Status from Oct 1, 2025 | Newly introduced, effective October 1, 2025 | Already applicable, remains unchanged |
No Insurance Licence to VC-backed Fintechs: IRDAI
- Venture capital (VC) = Money invested by professional investors or funds into startups that show high growth potential. These investors take risk early in the business in return for possible high profits later.
- VC-backed startups usually: Focus on fast growth. Depend on external funding. May not have long-term stability (since VCs often exit in a few years).
- May not have long-term stability (since VCs often exit in a few years).
Suryoday Small Finance Bank Launches Secured Credit Cards
- Headquarters: Mumbai, Maharashtra; serves over 2.8 million customers.
- Founded: 2008 as Suryoday Micro Finance in Chennai, Tamil Nadu.
- Transition: Became a Small Finance Bank in 2017 to promote financial inclusion.
- Collateral & Credit Limit: Cards are secured against fixed deposits. Minimum fixed deposit: Platinum: ₹1,000 Select: ₹1,11,500
The Council of Insurance Ombudsman (CIO) 2023-24 Report
- Objective: Resolve complaints for claims up to Rs 50 lakh internally within insurers.
- The Council of Insurance Ombudsman (CIO) 2023-24 report highlights rising complaints against health insurers in India. Policyholders have increasingly approached the Ombudsman due to claim delays, partial or complete repudiations, and other service issues.
- Public Sector Insurers in Top 5: National Insurance Co. Ltd – 2,196 complaints The New India Assurance Co. Ltd – 1,602 complaints
- Top Insurers by Complaints: Star Health & Allied Insurance – 13,308 complaints (10,000+ related to claim rejections) CARE Health Insurance – 3,718 complaints Niva Bupa Health Insurance – 2,511 complaints Public Sector Insurers in Top 5: National Insurance Co. Ltd – 2,196 complaints The New India Assurance Co. Ltd – 1,602 complaints
Long-Duration Debt Mutual Funds Hit by Rising G-Sec Yields
- Debt mutual funds that invest primarily in long-term fixed-income instruments like government securities (G-secs), corporate bonds, debentures, etc., with a maturity period of more than 7 years.
- Types: Treasury Bills (T-bills) – short-term (<1 year). Government Bonds – long-term (5–40 years).
- Government Bonds – long-term (5–40 years).
- Objective: They aim to generate stable, predictable returns over the long term, mainly through interest income and potential capital gains from bond price appreciation.
Variable Rate Reverse Repo (VRRR) Auction
- The Reserve Bank of India (RBI) plans to conduct an eight-day variable rate reverse repo (VRRR) auction on Thursday aimed to drain ₹ 1.5 trillion from the banking system.
- To drain ₹1.5 trillion excess liquidity from the banking system.
- Mechanism: Banks park their surplus funds with the RBI for a specified period (e.g., 7 or 14 days). The interest rate is determined through an auction (hence “variable rate”).
- Objective: To manage liquidity, control inflationary pressures, and align short-term rates with the policy repo rate.
| Feature | VRR (Variable Rate Repo) | VRRR (Variable Rate Reverse Repo) |
|---|---|---|
| Purpose | Inject liquidity into system | Absorb liquidity from system |
| Flow of Money | RBI → Banks | Banks → RBI |
| Collateral | Banks give G-secs to borrow funds | Banks deposit surplus cash |
| Impact | Eases shortage, reduces interest rates | Controls excess, supports inflation control |
Bank of Baroda Launches ‘bob Digi Udyam’ Collateral-Free Digital Financing Scheme
- State-owned Bank of Baroda (BoB) announced the launch of bob Digi Udyam – a digital, collateral-free lending platform offering Micro and Small Enterprises (MSEs) quick access to working capital loans above ₹10 lakh to ₹50 lakh.
- Loan Amount: ₹10 lakh – ₹50 lakh
- Modes of Application: Do-It-Yourself (DIY) online application. Assisted mode at bank branches.
- Tenure: 1 year
Axis Bank Launches ‘Sparsh Week 2025’
- Established: 1993
- On September 1, 2025, Axis Bank Limited launched the 3rd edition of Sparsh Week (September 1–5, 2025) under the theme “Raise the Bar”. The initiative brought together over 1 lakh employees across 5,868 branches in 40 cities to strengthen customer experience, employee engagement, and leadership visibility.
- Students: “Piggy to Prodigy Day” – Bank tours, fun learning sessions, and engagement with Axis Bank Young Bankers (ABYB).
- Farmers & Agri-entrepreneurs: Krishi Diwas advisory sessions, soil-testing kits, and rural outreach programs.
PhonePe Introduces Loans Against Mutual Funds (LAMF) with DSP Finance
- Founded: 2015
- Loan Amount: Up to ₹2 crore, secured against pledged mutual fund units.
- Headquarters: Bengaluru, Karnataka
- Repayment Structure: No EMIs or mandatory monthly principal repayment. Borrowers only pay interest on the amount withdrawn.
Bandhan AMC Gets SEBI Nod to Launch ‘Arudha SIF’ Platform
- Objective: To provide investors with advanced investment options beyond conventional MFs.
- Target Group: Sophisticated investors seeking differentiated risk-return profiles
- Key Features: Flexibility in portfolio construction. Enable non-traditional investment strategies. Offer sophisticated yet accessible solutions for both retail investors and High-Net-worth Individuals (HNIs).
- Offer sophisticated yet accessible solutions for both retail investors and High-Net-worth Individuals (HNIs).
REITs and InvITs Cross ₹9 Lakh Crore AUM in India
- Embassy Office Parks REIT (launched 2019, India’s first REIT)
- IRB InvIT Fund (first InvIT in India, 2017)
- Minimum Public Offer: At least ₹250 crore issue size, with minimum public float of 25%.
- Minimum Public Offer: At least ₹250 crore issue size, with minimum public float of 25%.
Bank of Baroda Launches ‘bob Digi Udyam’
- Founded: 1908
- Loan Range: Working capital loans from ₹10 lakh to ₹50 lakh.
- Headquarters: Vadodara, Gujarat
- Alignment with Policy: Initiative is aligned with the Union Budget 2024–25 announcement for in-house MSME credit assessment by public sector banks.
NSE and BSE Penalise MTNL for Non-Compliance with SEBI Board Norms
- Requirement: Mandatory for top 1,000 listed entities by market cap. Committee must have a majority of board members. Chairperson must be a board member. At least one independent director must be a member.
- Requirement: NRC must have at least 3 directors, all non-executive. At least 50% must be independent directors. The Chairperson of NRC must be an independent director.
- NRC must have at least 3 directors, all non-executive.
- At least 50% must be independent directors.
Bima Sugam
- Objective: Improve India’s insurance penetration (currently 3.7% vs global average of 7%). Lower transaction costs and improve consumer trust. Ensure transparency and efficiency in a sector often criticized for complexity.
- Improve India’s insurance penetration (currently 3.7% vs global average of 7%).
- Risk of market concentration, with smaller insurers fearing reduced visibility.
- Bima Vahak – Last-mile outreach through women entrepreneurs and community agents.
RBI’s New Co-Lending Guidelines
- Mandatory Retention: Each lender must retain at least 10% of the loan on its own books.
- Deadline: Guidelines take effect from January 2026. Smaller NBFCs have requested an extension.
- 15-Day Transfer Rule: Loan originator must transfer the loan to the co-lender within 15 days of origination, failing which it won’t qualify as co-lending.
- Escrow Accounts: Disbursements and collections must be routed through escrow-based mechanisms.
Deposit-Backed Credit Cards
- FD with Bank: ₹50,000 at 6% interest.
- Credit Card Limit: ₹50,000 (secured against FD).
- Usage: Shops online for ₹10,000 and pays full bill on time.
- Benefits: FD continues earning interest. Builds credit score. Can be upgraded to an unsecured card after 12 months.
India’s Central Bank Digital Currency (e-Rupee)
- Technology: Can be held in digital wallets or bank accounts. Supports peer-to-peer (P2P) and merchant payments.
- With UPI crossing 700 million daily transactions, questions arise on the need for a Central Bank Digital Currency (CBDC). Experts argue that the e-rupee can achieve financial inclusion, compliance, and efficiency in ways that UPI cannot.
- e-Rupee is the digital version of India’s fiat currency (INR), issued and guaranteed by the Reserve Bank of India (RBI). It is legal tender and functions like physical cash but exists in electronic form.
- Supports peer-to-peer (P2P) and merchant payments.
| Feature | Cryptocurrency | e-Rupee (Digital Rupee) |
|---|---|---|
| Issuer | Decentralized, created by private entities | Centralized, issued by RBI |
| Legal Status in India | Not legal tender; investment allowed | Legal tender, backed by RBI |
| Value Stability | Highly volatile; depends on market demand | Stable; 1 e-Rupee = 1 INR |
| Underlying Technology | Blockchain, decentralized ledger | Digital ledger, controlled by RBI (CBDC) |
| Purpose | Investment, trading, peer-to-peer transfer | Digital payments, financial inclusion, faster settlements |
| Regulation | Partially regulated; no government guarantee | Fully regulated; government-backed |
| Interest / Incentives | None inherently | FD or bank account may earn interest (depends on storage method) |
| Risk | High (market risk, fraud, scams) | Low (regulated, government-backed) |
SEBI Postpones Settlement for Cash and SLBM Segments
- Objective: Ensure smooth settlement operations, avoid disruptions, and maintain market integrity.
- Cash Market: Trades in the regular stock market where shares are bought/sold for immediate delivery (T+2).
- SLBM: A market that allows investors to lend or borrow securities temporarily, facilitating activities like short selling and enhancing liquidity.
SAT Asks Sebi to Explain Non-Disclosure of Documents in Jane Street Case
- SEBI Act, 1992 (Sections 11, 11B, 11C) – Provides SEBI the authority to regulate securities markets and take action against manipulative practices.
- Constituted under Section 15K of the Securities and Exchange Board of India Act, 1992.
- SEBI (Prohibition of Fraudulent and Unfair Trade Practices) Regulations, 2003 – Prevents market manipulation, deceptive practices, or artificial price movements.
- SEBI (Prohibition of Insider Trading) Regulations, 2015 – Addresses trading based on unpublished price-sensitive information.
Reinsurance India
- Established: 1999 (under IRDA Act, 1999)
- It helps share or transfer risk, especially for large or catastrophic exposures, so that no single insurance company bears the entire risk.
- Example: If an insurance company covers a huge industrial project, it may cede a portion of the premium and risk to a reinsurer like Allianz Re.
- Risk diversification for insurers.
| Type of Insurance | Description | Examples |
|---|---|---|
| Life Insurance | Covers death, disability, or survival risks. Provides financial security to dependents. | Term insurance, Endowment plans, ULIPs |
| General (Non-Life) Insurance | Covers property, health, vehicles, liability, etc. | Health insurance, Motor insurance, Home insurance, Travel insurance |
| Reinsurance | Insurance for insurance companies to share/transfer risk. Can be treaty-based (portfolio) or facultative (specific risk). | Allianz Re, Swiss Re, GIC Re (Only Indian reinsurer company in India) |
| Microinsurance | Low-cost insurance for low-income populations. | Crop insurance for small farmers, Livestock insurance |
Ujjivan Small Finance Bank Awaits RBI Nod for Universal Bank Licence
- Ujjivan Small Finance Bank (SFB) is awaiting the Reserve Bank of India’s (RBI) decision on its application for a universal banking licence, which could come by December 2025, according to CEO Sanjeev Nautiyal.
- Net Worth: The applicant bank must have a minimum paid-up capital of ₹500 crore (may vary as per RBI directions).
- Capital Adequacy: Must meet the Capital to Risk-Weighted Assets Ratio (CRAR) requirements as per Basel norms (minimum 9% for Indian banks).
- A universal bank in India is a financial institution that provides the entire spectrum of banking services, including:
SBI Launches “Dream2Demo” Startup Pitch Fest
- Founded: 1 July 1955
- In August 2025, SBI established a Centre of Excellence (CoE) for Micro, Small and Medium Enterprises (MSMEs) at the State Bank Academy (SBA) in Gurugram to further support business development and financial inclusion.
- Objective: Facilitate startup growth from grassroots to global stages, ensuring mentorship, funding, and exposure.
- Headquarters: Mumbai, Maharashtra, India
Sebi Focuses on Easing FPI Investments Amid Global Uncertainties
- FPI License Tenure Proposal: Extend tenure from 3 years to 5 years. Current SEBI Norm: As per SEBI (FPI) Regulations, 2019, FPI registration is valid for 3 years (renewable).
- Current SEBI Norm: As per SEBI (FPI) Regulations, 2019, FPI registration is valid for 3 years (renewable).
- KYC Reforms Proposal: Simplify onboarding. Current Norm: FPIs must comply with KYC norms under SEBI Master Circular on KYC (April 2023), including PAN, beneficial ownership disclosure, and FATF compliance.
- Current Norm: FPIs must comply with KYC norms under SEBI Master Circular on KYC (April 2023), including PAN, beneficial ownership disclosure, and FATF compliance.
Suryoday SFB Launches RuPay Secured Credit Cards Backed by FDs
- Incorporated: 2008; began SFB operations in 2017
- Focus: Financial inclusion and innovative credit solutions for underserved segments
- A secured credit card issued against a customer’s Fixed Deposit (FD) kept with the bank.
- The FD acts as collateral, reducing risk for the bank.
RBI Launches New Microsite for Banknote Information
- Features: 360-degree view of banknotes. Multimedia content: videos, audios, animations. Interactive games to educate users about currency. Dedicated section on the exchange of banknotes. Simple and efficient navigation for users of all ages.
- 360-degree view of banknotes.
- Interactive games to educate users about currency.
- Simple and efficient navigation for users of all ages.
PhonePe Partners with MSME Ministry & SIDBI to Boost Udyam Registrations
- Objective To register more small merchants with Udyam, the government’s official platform for MSME recognition. Formalisation will help merchants become eligible for credit, subsidies, and welfare schemes.
SEBI Eases Rules for Foreign Investors in Government Bonds
- Introduced by the RBI in April 2020.
- The Securities and Exchange Board of India (SEBI) announced that its revised regulations for foreign investors investing exclusively in Indian government securities will come into effect from 8 February 2026. The rules were initially approved at SEBI’s board meeting in June 2025.
- Applicability: Applies to Foreign Portfolio Investors (FPIs) who invest only in Indian government bonds under the fully accessible route.
- Applies to Foreign Portfolio Investors (FPIs) who invest only in Indian government bonds under the fully accessible route.
EPFO 3.0 Initiative
- What is EPFO 3.0: EPFO 3.0 is a proposed upgrade to the Employees’ Provident Fund Organisation’s digital ecosystem aimed at enabling seamless, bank-like services for subscribers.
- Enhanced Pension: The central board may consider raising the minimum monthly pension from ₹1,000 to ₹1,500–2,500, addressing a long-pending demand from trade unions.
- User Convenience: Subscribers can access and manage their PF accounts more like a regular bank account, improving financial flexibility.
RBI Approves Yes Bank Board Changes for SMBC Nominee Directors
- Nominee Directors Appointment: 2 directors to be nominated by SMBC. 1 director to be nominated by SBI.
- 2 directors to be nominated by SMBC.
- Relevance to Banks: Any change in board structure, capital, or powers of directors in a private bank requires RBI approval via AoA amendments.
- Any change in board structure, capital, or powers of directors in a private bank requires RBI approval via AoA amendments.
Decentralised Finance (DeFi)
- Origin: Rooted in Bitcoin (2009) philosophy of decentralisation and transparency. Expanded with Ethereum (2015) and DAOs (Decentralised Autonomous Organisations).
- Rooted in Bitcoin (2009) philosophy of decentralisation and transparency.
- Expanded with Ethereum (2015) and DAOs (Decentralised Autonomous Organisations).
- Aim: Democratise financial access by removing intermediaries. Offer inclusive, low-cost, borderless financial services.
Mutual Fund–Voluntary Retirement Account (MF-VRA) Scheme
- Addresses the challenge of a rapidly aging population, projected to reach 21% of the population by 2050.
- Tax Benefits: Contributions may qualify for deductions under Section 80C of the Income Tax Act.
- The Association of Mutual Funds in India (AMFI) has proposed the Mutual Fund–Voluntary Retirement Account (MF-VRA), a retirement savings scheme inspired by the U.S. 401(k) plan, to boost long-term retirement planning in India.
- Employer Contributions: Employers can contribute a portion of employees’ salaries, which can be matched by employees.
Sebi Eases Rules for Privately Placed InvITs, REITs, and Portfolio Managers
- Minimum Allotment Lot for Privately Placed InvITs Reduced to Rs 25 lakh (earlier Rs 1–25 crore depending on asset mix). Aligns primary market allotment with the secondary market trading lot size.
- Reduced to Rs 25 lakh (earlier Rs 1–25 crore depending on asset mix).
- Holdco Cash Flow Adjustments Earlier: Holding company had to distribute 100% of SPV cash flows to REIT/InvIT. Now: Holdco can offset its own negative cash flows before distribution, with proper disclosure to unitholders.
- Earlier: Holding company had to distribute 100% of SPV cash flows to REIT/InvIT.
Nabfid to Submit Infra Financing Report
- Established under NABFID Act, 2021 as a Development Finance Institution (DFI).
- National Bank for Financing Infrastructure and Development (Nabfid) will prepare a report on infrastructure financing challenges. To be submitted to the Department of Financial Services (DFS), Ministry of Finance within 15 days.
- Municipal Bonds – Barriers in issuance, low investor appetite.
- Objective: Provide long-term infrastructure financing and develop the bond/loan market.
RBI to Allow Lenders to Remotely Lock Phones for Defaulted Loans
- Secured Credit Regulations under the RBI Act, 1934 – allowing secured lending where the collateral can be digitally controlled or monitored.
- This mechanism would act as a collateral-like security without physical repossession, helping lenders recover dues efficiently.
- Digital Lending Guidelines 2023 – governing use of technology in lending, including device-based tracking or locking mechanisms, while protecting borrower data and privacy.
- The Reserve Bank of India (RBI) plans to permit lenders to remotely lock mobile phones purchased on credit if borrowers default, aiming to reduce non-performing assets (NPAs) in small-ticket consumer loans.
NABARD to Launch Centralised Digital Lending Platform for RRBs
- Established in 1975 under an Ordinance and Regional Rural Banks Act, 1976.
- Shareholding pattern: Government of India 50%, State Government 15%, Sponsoring Bank 35%.
- RRB Overview: Established in 1975 under an Ordinance and Regional Rural Banks Act, 1976. Aimed at developing rural economies and supplementing the Cooperative Credit Structure. Shareholding pattern: Government of India 50%, State Government 15%, Sponsoring Bank 35%. Network: 28 RRBs, 22,158 branches across 26 states and 3 Union Territories. 92% branches in rural or semi-urban areas, highlighting their role in financial inclusion.
- 92% branches in rural or semi-urban areas, highlighting their role in financial inclusion.
SEBI Approves Key Reforms in Public Issues, FPIs, and Mutual Funds
- Minimum Public Offer (MPO) set at ₹6,250 crore + 2.75% of post-issue market cap.
- If public shareholding <15% at listing: 5 years to reach 15% public shareholding. 10 years to achieve mandated 25% Minimum Public Shareholding (MPS).
- 5 years to reach 15% public shareholding.
- 10 years to achieve mandated 25% Minimum Public Shareholding (MPS).
SEBI Stresses Transparency on Family Settlements
- A legal agreement between family members concerning family-owned businesses, properties, or shares.
- Purpose: Resolve disputes among family members without litigation. Divide assets, shares, or responsibilities among heirs.
- Resolve disputes among family members without litigation.
- Divide assets, shares, or responsibilities among heirs.
SEBI Eases FPI Entry with Automatic Registration Window
- Objective: The reform seeks to attract more foreign capital, particularly after significant equity outflows of over ₹83,000 crore since July 2025.
- Eligibility Criteria: FPIs that are at least 75% owned by foreign governments or are regulated in their home jurisdictions can avail of this facility.
India’s Outward Foreign Direct Investment (FDI)
- Total outward FDI (2024-25): ₹3,488.5 crore.
- Regulated: The Reserve Bank of India (RBI) and the Ministry of Commerce & Industry regulate OFDI through frameworks like the Foreign Exchange Management Act (FEMA), 1999.
- Top destinations: Singapore – 22.6% Mauritius – 10.9% UAE – 9.1%
- Singapore – 22.6%
Regulatory Framework in India:
- Government Route: Requires approval for sensitive sectors or higher amounts.
Insurance Amendment Bill
- Insurance Act, 1938: Principal framework for insurance operations in India.
- Life Insurance Corporation Act, 1956: Empower LIC board for operational decisions (branch expansion, recruitment).
- Insurance Regulatory and Development Authority Act, 1999: Align regulatory provisions with the amended FDI policy.
- FDI Enhancement: Raise the foreign investment limit from the current 74% to 100%. Applicable to companies investing the entire premium in India. Review and simplify existing guardrails and conditionalities for foreign investment.
UPI-Based Cash Withdrawals to Expand Through Business Correspondents
- Currently, UPI-driven cash withdrawals are available only at UPI-enabled ATMs and certain merchants (₹1,000 per transaction in urban areas; ₹2,000 in rural areas).
- Proposed withdrawals via UPI at BCs could allow up to ₹10,000 per transaction, similar to micro-ATM limits.
- BCs act as the bank’s agents, bridging the gap between banks and customers, particularly in rural and semi-urban areas.
- Expansion Scope: Currently, UPI-driven cash withdrawals are available only at UPI-enabled ATMs and certain merchants (₹1,000 per transaction in urban areas; ₹2,000 in rural areas). Plans are underway to extend the facility to over 2 million Business Correspondents (BCs) across India.
Sebi Pushes Capital Market Reforms to Enhance Depth and Investor Participation
- A wider group of institutional investors can now act in a strategic capacity in REITs, enhancing liquidity and market depth.
- The share reserved for anchor investors during IPO listing has been increased, incentivising early participation by large investors.
- Mutual Fund and FII Adjustments: Exit load thresholds for mutual funds have been lowered, providing greater flexibility for investors. Low-risk Foreign Institutional Investors (FIIs) now face relaxed disclosure requirements, reducing compliance burdens.
- Exit load thresholds for mutual funds have been lowered, providing greater flexibility for investors.
SEBI Plans Further Relaxations for Foreign Portfolio Investors (FPIs)
- Registration renewal cycle extended to 10 years (earlier 3 years).
- Exemptions from the 50% aggregate contribution cap for NRIs and OCIs.
- Aimed at reducing duplication and easing compliance for low-risk FPIs.
- Swagat-FI Framework: Applies to trusted FPIs (sovereign wealth funds, pension funds, government-related entities). Registration renewal cycle extended to 10 years (earlier 3 years). One-time KYC fee of $2,500 for a 10-year block instead of the three-year cycle. Exemptions from the 50% aggregate contribution cap for NRIs and OCIs.
Rising Digital Fraud and Mule Accounts
- Section 35A of the Banking Regulation Act, 1949 – Empowers RBI to issue directions to banks for controlling banking operations, including KYC, monitoring, and risk management.
- Prevention of Money Laundering Act (PMLA), 2002 – Obligates banks to maintain KYC, report suspicious transactions, and prevent misuse for money laundering.
- Account holders may be unaware or complicit.
- Fraudsters transfer illegally obtained money through mule accounts to obscure its origin.
SEBI Reclassifies REITs as Equity for Mutual Fund Investments
- This could boost liquidity and inflows into the REIT market, making real estate investment more accessible to retail investors via MFs.
| Feature | Hybrid Securities | Equity Securities |
|---|---|---|
| Definition | Financial instruments combining debt and equity features (e.g., convertible debentures, preference shares) | Represents ownership in a company, value fluctuates with the company’s stock price |
| Risk Profile | Moderate; partially fixed returns from debt component | High; returns depend on market performance |
| Mutual Fund Treatment | Exposure limits often restricted to reduce risk | Treated like stocks; higher exposure allowed in equity funds |
| Income Type | Fixed interest + potential capital gains | Dividends + capital gains from price appreciation |
| Examples | Convertible bonds, certain preference shares | Equity shares, now REITs under SEBI’s classification |
Securitisation
- Securitisation activity (sale of loans through structured transactions) is projected to remain subdued in Q2FY26 (July–September 2025), with estimated volumes of ₹63,000 crore, compared to ₹70,000 crore in the same quarter last year.
- Pooling of Assets Similar loans or receivables are grouped together into a pool to diversify risk. Example: Pooling 1,000 home loans of ₹30 lakh each.
- Example: Pooling 1,000 home loans of ₹30 lakh each.
- To transfer credit risk to investors.
Offshore Non-Deliverable Forward (NDF) Market
- Reasons for Rupee Pressure: Exporters delaying dollar sales, reducing liquidity in the forex market. Importers increasing hedging activity due to US tariff risks.
- Exporters delaying dollar sales, reducing liquidity in the forex market.
- Importers increasing hedging activity due to US tariff risks.
- RBI’s Response: Resumed intervention in NDF market after a period of reduced activity. Interventions primarily visible during local trading hours, indicating a targeted approach to manage volatility.
Prepaid Payment Instrument (PPI)
- The Reserve Bank of India (RBI) has levied a fine of ₹21 lakh on PhonePe for non-compliance with regulations governing Prepaid Payment Instruments (PPIs).
- Escrow Account: A secure account where PPI operators must maintain user funds to ensure their safety and proper usage in line with RBI rules.
- Open System PPIs – Can be used for all merchant payments, ATM withdrawals, and fund transfers.
- Preloaded Value: Users load money into the instrument before use.
Under Which Act RBI Did So?
- PSS Act, 2007: Provides the legal framework for regulating payment systems in India.
- The RBI action against PhonePe for its escrow account balance falling below the mandated minimum was done under the Payment and Settlement Systems Act, 2007 (PSS Act, 2007).
- Escrow Account Requirement: Prepaid Payment Instrument (PPI) issuers are required to maintain a minimum balance in a designated escrow account, ensuring that customer funds are always secured.
ICICI Bank Extends Amazon Pay Co-Branded Credit Card Partnership
- Launch: The card was first launched in 2018.
- ICICI Bank has renewed its partnership with Amazon Pay for the co-branded “Amazon Pay ICICI Credit Card” for another 7 years.
- Co-Branded Trends: Axis Bank, the fourth-largest issuer, partners with Flipkart for its co-branded credit card.
- Market Position: ICICI Bank is the third-largest credit card issuer in India, after HDFC Bank and SBI.
RBI Issues Final Guidelines for Payment Aggregators (PAs)
- Authorization & Net Worth: Non-bank PAs must obtain RBI authorization under the Payment and Settlement Systems Act, 2007. Minimum net worth: ₹15 crore at application, rising to ₹25 crore by the end of the 3rd financial year. Banks providing PA services as part of regular operations are exempt.
- Non-bank PAs must obtain RBI authorization under the Payment and Settlement Systems Act, 2007.
- Governed by the Reserve Bank of India (RBI) under the Payment and Settlement Systems Act, 2007.
- Minimum net worth: ₹15 crore at application, rising to ₹25 crore by the end of the 3rd financial year.
SEBI Launches Swagat-FI
- Extended Validity: Registered entities under this framework will benefit from an extended registration validity of 10 years, providing greater stability and predictability for long-term investments.
- The Securities and Exchange Board of India (SEBI) unveiled the Single Window Automatic & Generalised Access for Trusted Foreign Investors (Swagat-FI) on 12 September 2025 the most comprehensive reform of foreign investment rules to date. The framework is designed to simplify onboarding, unify investment routes, and attract long-term global capital into India.
- Simplified Registration: SWAGAT-FI offers a single-window registration process, reducing the complexity and time required for foreign investors to enter the Indian market.
- Streamlined Compliance: The framework aims to ease ongoing compliance requirements, making it more efficient for trusted foreign investors to operate within India's regulatory environment.
PFRDA Allows Bespoke Pension Plans
- The Pension Fund Regulatory and Development Authority (PFRDA) has announced that individual pension fund houses can now launch tailor-made investment plans, marking a potential overhaul for India’s $175 billion pension industry.
- Account holders can now operate multiple pension programs simultaneously, giving greater flexibility to diversify across risk profiles and retirement goals.
- Pension managers can now design plans targeting specific customer segments, advertising a broader range of potential returns.
- Subscribers can choose investments across four asset classes: Equity Corporate debt Government bonds Alternative investment funds
RBI, NPCI Set to Launch Netbanking 2.0
- At least four major banks HDFC Bank, Axis Bank, SBI, and AU Small Finance Bank along with several online payment aggregators are preparing to go live on Netbanking 2.0, a new interoperable netbanking switch developed by NPCI Bharat BillPay Ltd. (NBBL). The official launch is expected by RBI Governor Sanjay Malhotra at the Global Fintech Fest 2025 (Oct 7–9).
- Enables interoperability across banks — merchants and aggregators won’t need separate bank tie-ups.
- Distinctiveness: Unlike existing systems, it removes the need for individual payment aggregators to integrate separately with each bank.
- Aims to standardise and simplify netbanking transactions.
Viyona Fintech Approved as Third-Party Application Provider (TPAP) by NPCI
- No Fund Handling: Unlike Payment Aggregators, TPAPs cannot hold or settle customer funds; the transaction settlement happens directly between the bank accounts of payer and payee.
- Unlike Payment Aggregators, TPAPs cannot hold or settle customer funds; the transaction settlement happens directly between the bank accounts of payer and payee.
- Customer Experience: Provides user-friendly interfaces, such as mobile apps, for easy UPI payments, bill payments, and collections. Supports multi-bank interoperability, eliminating the need for users to install multiple bank apps.
- Supports multi-bank interoperability, eliminating the need for users to install multiple bank apps.
RBI Approves Amendments to Yes Bank’s Articles of Association for Nominee Directors
- Legal Requirement: Required under the Companies Act, 2013 in India. Works alongside the Memorandum of Association (MoA), which defines the company’s objectives and scope of operations.
- Required under the Companies Act, 2013 in India.
- Can include provisions for nominee directors when a company receives investment from specific investors (like in Yes Bank case with SMBC).
- The Reserve Bank of India (RBI) has approved changes to Yes Bank’s Articles of Association (AoA) regarding the appointment of nominee directors following a stake acquisition by Sumitomo Mitsui Banking Corporation (SMBC), Japan.
RBI Sets Up Regulatory Review Cell and Advisory Group on Regulation
- Objective: To ensure that all RBI regulations undergo a comprehensive internal review every 5–7 years.
- Tenure: Initial 3 years, renewable for 2 more years. Provision to co-opt additional experts if needed.
- Launch Date: October 1, 2025
- Composition: Six-member panel chaired by Rana Ashutosh Kumar Singh, MD, State Bank of India.
SEBI Plans to Broaden Participation in Non-Agricultural Commodity Derivatives
- By December, commodity brokers will come under a unified reporting system to simplify compliance.
- MCX aims to expand participation in metal contracts across: Commercial participants: Large and small-to-medium metal producers and consumers Financial participants: Broker-members, investors, mutual funds, ETFs, banks
- Commercial participants: Large and small-to-medium metal producers and consumers
- Financial participants: Broker-members, investors, mutual funds, ETFs, banks
Bima Sugam India Federation Launches Official Website
- Unified Marketplace: Offers a one-stop platform for life, health, and general insurance products from various insurers.
- Transparency and Accessibility: Ensures transparency in insurance transactions and enhances accessibility for consumers.
CRED-IndusInd Bank Co-Branded Credit Card Launch
- First Card: CRED IndusInd Bank RuPay Credit Card.
- Premium Consumer Targeting: Focus on affluent, digitally-savvy users.
RBI’s New Master Direction on Payment Aggregators (2025)
- Prevent misuse of credit cards: Rent payments were functioning like disguised peer-to-peer (P2P) transfers.
- Must switch back to bank transfers, UPI, cheques, or BBPS for rent payments.
- On September 2025, RBI issued a revised Master Direction for PAs. Major fintechs like PhonePe, Paytm, and Cred have stopped offering rent payment via credit cards as a result.
- Curb fraud and money laundering: Fake “rent” payments were sometimes used for cash flow management or illicit transfers.
SEBI Gives Clean Chit to Adani Group in Hindenburg Case
- Hindenburg Report (Jan 2023): U.S.-based short-seller Hindenburg Research accused the Adani Group of stock price manipulation, accounting irregularities, and use of offshore shell companies.
- On September 18, 2025, the Securities and Exchange Board of India (SEBI) concluded its investigation into allegations by U.S.-based shortseller Hindenburg Research against the Adani Group. The case mainly involved Adani Ports & SEZ Ltd. and Adani Power Ltd.
- Impact: Adani Group companies lost over $100 billion in market capitalization within weeks. Concerns raised about transparency, corporate governance, and investor protection in Indian markets.
- Adani Group companies lost over $100 billion in market capitalization within weeks.
| Act/Regulation | Year | Purpose/Key Provisions | Exam Relevance |
|---|---|---|---|
| SEBI Act | 1992 | Establishes SEBI as market regulator; protects investors, promotes fair trading, regulates intermediaries. | Foundation of SEBI’s powers, must know sections like Section 11 (functions of SEBI). |
| Securities Contracts (Regulation) Act – SCRA | 1956 | Governs listing, recognition of stock exchanges, and trading of securities. SEBI empowered to regulate stock exchanges. | Important for listing rules, delisting, recognition of stock exchanges. |
| Depositories Act | 1996 | Provides framework for dematerialisation and working of depositories like NSDL, CDSL. | Related to demat accounts, electronic shareholding. |
| Companies Act (SEBI-linked provisions) | 2013 | Covers corporate disclosures, corporate governance, issue of securities, shareholder protection. | SEBI coordinates with MCA, exam focus on disclosure & governance norms. |
| Prevention of Fraudulent and Unfair Trade Practices (PFUTP) Regulations | 2003 | Prevents price rigging, insider trading, circular trading, misleading disclosures. | Invoked in Adani–Hindenburg type probes. |
| Listing Obligations and Disclosure Requirements (LODR) Regulations | 2015 | Prescribes disclosure norms for listed companies (quarterly results, shareholding patterns, related-party transactions, corporate governance). | Core for corporate governance & transparency. |
| Foreign Portfolio Investors (FPI) Regulations | 2019 | Regulates investment by foreign institutional investors (FIIs/FPIs). Defines categories of FPIs. | Key for exam after Adani–Hindenburg controversy. |
EPFO Launches ‘Passbook Lite’ and Online Access to Annexure K
- Statutory Body: Established under the Employees’ Provident Funds and Miscellaneous Provisions Act, 1952.
- On September 18, 2025, the Employees’ Provident Fund Organisation (EPFO) introduced two major digital reforms to improve transparency and member convenience.Union Labour Minister Mansukh Mandaviya announced the launch of “Passbook Lite” on the EPFO members’ portal and direct online access to Annexure K.
- Annexure K Online Access: Annexure K = PF transfer certificate generated when employees change jobs and accounts are shifted via Form 13. Previously, it was shared only between PF offices and available to members only on request. Now, employees can directly download Annexure K in PDF from the members’ portal. Members can also track transfer applications online, ensuring greater transparency.
- Annexure K = PF transfer certificate generated when employees change jobs and accounts are shifted via Form 13.
PhonePe Gets RBI Authorisation as Online Payment Aggregator
- RBI Regulation: Introduced in March 2020 under RBI’s Guidelines on Regulation of Payment Aggregators and Payment Gateways.
- Key Guidelines: PA/PG Framework (2020): Mandated authorisation for non-bank PAs. Minimum Net Worth Requirement: ₹15 crore at the time of application, rising to ₹25 crore by the end of the third financial year. Governance & Compliance: Fit-and-proper criteria, escrow account maintenance, grievance redressal mechanism.
- PA/PG Framework (2020): Mandated authorisation for non-bank PAs.
- Minimum Net Worth Requirement: ₹15 crore at the time of application, rising to ₹25 crore by the end of the third financial year.
RBI Conducts VRR Auctions to Infuse Liquidity
- Impact: Will release about ₹2.5 lakh crore of primary liquidity into the banking system by Dec 2025.
- RBI is targeting a system liquidity surplus of ₹1.5–2 lakh crore to ensure: Smooth monetary transmission of repo rate cuts into lending and deposit rates. Adequate short-term liquidity for banks.
- CRR Cut: To be implemented in four tranches of 25 bps each on Sept 6, Oct 4, Nov 1, Nov 29 (2025).
- Sept 6, Oct 4, Nov 1, Nov 29 (2025).
SEBI and RBI Push for Corporate Bond Index Derivatives
- SEBI cleared the way for Cash-Settled Corporate Bond Index Futures (CBIF) in January 2023 for corporate debt securities rated AA+ and above. Talks with RBI aim to reinvigorate this initiative.
- CBIF are derivative contracts based on a corporate bond index, allowing investors to take positions on the performance of a basket of high-quality corporate bonds.
- Cash-settled: No physical delivery of bonds occurs; settlements are made in cash based on the difference between contract price and the final index value at maturity.
- SEBI cleared CBIF in January 2023 for launch by stock exchanges.
PFRDA in Talks with SEBI to Allow Pension Funds in Commodity Derivatives
- Objective: Enable pension funds to access gold, silver, and potentially other metals for investment, aiming for long-term stable returns.
- SEBI has indicated interest in permitting banks, insurers, and pension funds to access non-agricultural commodity markets.
- Insurance regulators may take a cautious approach before allowing insurers to participate.
- Expands the investment avenues for pension funds and other long-term institutional investors.
PFRDA Introduces Multiple Scheme Framework for NPS
- Variants & Equity Allocation: Each scheme must have at least two variants: moderate-risk and high-risk. Equity allocation in high-risk schemes can now go up to 100% (previously 75%).
- Establishment: Initially set up as a regulatory body for pension sector; made statutory under PFRDA Act, 2013 (notified on Feb 1, 2014).
- Equity allocation in high-risk schemes can now go up to 100% (previously 75%).
- Headquarters: New Delhi, Delhi
RBI Authorizes DBS Bank India as Agency Bank
- DBS Bank India became the first wholly owned subsidiary of a foreign bank in India to be authorized by the Reserve Bank of India (RBI) as an agency bank.
- These functions include collection and disbursement of government funds, tax collections, pension payments, and issuance of savings instruments.
- Payments Makes pension payments to retired government employees. Disburses subsidies, scholarships, and government payments.
- Disburses subsidies, scholarships, and government payments.
SEBI Reintroduces B-30 Incentives and Caps Mutual Fund Exit Load
- What? SEBI will provide incentives to distributors for bringing new individual investors (new PAN) from beyond top-30 (B-30) cities.
- Structure: Lumpsum investment: Incentive = 1% of the first application amount. SIP investment: Incentive = 1% of total investment in the first year. Cap: Maximum ₹2,000 per new investor.
- Lumpsum investment: Incentive = 1% of the first application amount.
- SIP investment: Incentive = 1% of total investment in the first year.
EPFO Allows Part Payments in PF Settlements to Prevent Financial Distress
- This aligns with para 10.11 of the Manual of Accounting Procedure (MAP) Part-IIA, which allows such settlements.
- Non-receipt of Form 3A (annual contribution details).
- Partial claims where the eligible person has not claimed the full amount.
- Once the pending amount becomes available, the office should make further payments automatically, without requiring a fresh claim from members.
CBIC to Launch Advanced GST Invoice Management System
- CBIC traces its roots to older boards, it’s constituted under the Central Boards of Revenue Act, 1963.
- Prevention of Automatic Notices System will prevent auto-generation of mismatch notices triggered by minor discrepancies between GST returns. Currently, ~2 lakh notices are sent annually, covering nearly ₹10 lakh crore in disputes.
- Currently, ~2 lakh notices are sent annually, covering nearly ₹10 lakh crore in disputes.
- Earlier known as Central Board of Excise and Customs (CBEC), renamed in 2018 after introduction of GST.
FACEs Debt Collection Norms: New Benchmark for Fintechs and NBFCs
- Founded: September 2020
- Objective: Create a robust, respectful, and responsible debt collection process, ensuring fair treatment of borrowers.
- It was the only association approved under RBI’s fintech SRO framework as of August 2024.
- Fintech: Fintech (short for Financial Technology) refers to the use of digital technologies, such as software, apps, and algorithms, to provide and automate financial services and products, making them more accessible, efficient, and less costly.
Stablecoin
- Global Context: The US passed the GENIUS Act (2025), providing a regulatory framework for stablecoins. However, risks remain—as seen in the TerraUSD collapse (2022), which wiped out $60 billion.
- The US passed the GENIUS Act (2025), providing a regulatory framework for stablecoins.
- What are Stablecoins? Private cryptocurrencies like Tether (USDT) and USD Coin (USDC), pegged to the US dollar with 1:1 convertibility. Used widely in crypto trading and cross-border remittances for instant, low-cost transfers.
- Adoption in India: India reportedly has 314 million stablecoin holders, the highest in the world. Users prefer them for global acceptability and faster remittances compared to banks.
Clearing Corporation of India Ltd (CCIL)
- CCIL was set up in April 2001 following recommendations of the Sodhani Committee (1995) and subsequent committees on forex and settlement systems.
- On September 19, 2025, RBI Governor Sanjay Malhotra invited the Clearing Corporation of India Ltd (CCIL) to build infrastructure for trading and settling currency pairs beyond USD–INR, aligning with India’s broader objective of rupee internationalisation.
- Retail Direct (with RBI): Enables retail investors to invest directly in G-Secs (minimum reduced from ₹10 lakh to ₹10,000).
- Emerged after the East Asian Financial Crisis (1997) highlighted risks in weak settlement systems.
SMFG India Credit Partners with PhonePe to Offer Collateral-Free Credit
- Micro-merchants are very small business owners, usually self-employed or family-run enterprises, with low annual turnover (often below ₹50 lakh in India).
- They typically have 1–5 workers (sometimes just the owner) and operate at a neighborhood or community level.
- Target Audience: Merchants in Tier-2 and Tier-3 towns, supporting small businesses in semi-urban and rural India.
- Objective: Strengthen SMICC’s role as a leading lender in the MCA space and improve access to working capital for small merchants.
Paytm Launches UPI Credit Line ‘Paytm Postpaid’ with Suryoday SFB
- Type of Credit: Short-term, interest-free credit for up to 30 days, repayable the following month.
- Financial Inclusion: Provides easy access to short-term credit for users without the need for formal loans.
- Convenience for Consumers: Enables users to manage monthly expenses without interest, promoting responsible digital credit usage.
Tax Loss Harvesting (TLH) Code
- Suppose you sold Stock A at a ₹50,000 loss and made a ₹70,000 profit from Stock B.
- Using TLH, you can offset ₹50,000 from the profit, paying capital gains tax only on ₹20,000.
- Objective: Facilitate smooth transfer of securities upon the death of an investor, easing financial processes for legal heirs.
- Tax Loss Harvesting (TLH) is a strategy where investors sell securities at a loss to offset capital gains made elsewhere.
SEBI Proposes Changes to Technical Glitch Framework for Stockbrokers
- Applicability Threshold Applies only to brokers: Providing internet-based trading platforms Having more than 10,000 clients as of March 31 of the previous financial year Result: 457 small stockbrokers will now be excluded, reducing compliance burden.
- Applies only to brokers: Providing internet-based trading platforms Having more than 10,000 clients as of March 31 of the previous financial year
- Result: 457 small stockbrokers will now be excluded, reducing compliance burden.
- Redefinition of Technical Glitch Excludes malfunctions after trading hours and issues beyond the control of stockbrokers.
RBI Clarifies Regulations on NBFC-Peer to Peer (P2P) Lending Platforms
- Operational Guidelines: Customer funds cannot be used by the platform. All loan disbursals and repayments must go through bank accounts of registered lenders and borrowers via escrow accounts. ‘T+1’ settlement refers to one bank working day.
- ‘T+1’ settlement refers to one bank working day.
- Definition: A P2P lending platform is an online marketplace connecting borrowers (individuals/businesses) directly with investors/lenders, bypassing traditional banks.
- A P2P lending platform is an online marketplace connecting borrowers (individuals/businesses) directly with investors/lenders, bypassing traditional banks.
Baroda BNP Paribas Mutual Fund Announces Debt Fund Merger
- Unitholder Options: Investors have a 30-day notice period (17th September to 16th October 2025) to exit without any exit load.
- Investors have a 30-day notice period (17th September to 16th October 2025) to exit without any exit load.
- Baroda BNP Paribas Mutual Fund has announced the merger of its Banking & PSU Bond Fund (merging scheme) into its Short Duration Fund (surviving scheme), effective 17th October 2025.
- Regulatory Framework: The merger is classified as a change in fundamental attributes under Regulation 18(15A) of SEBI Mutual Fund Regulations, 1996. SEBI has provided a no-objection for the merger.
S&P Retains India’s GDP Growth Forecast at 6.5%
- S&P Global Ratings has maintained India’s GDP growth forecast for FY2025-26 at 6.5%, highlighting strong domestic demand and a supportive monsoon.
| Indicator | Forecast / Value | Notes / Drivers |
|---|---|---|
| GDP Growth (FY26) | 6.5% | Growth retained by S&P Global Ratings |
| Recent GDP Growth (Q1 FY26) | 7.8% | April–June 2025 quarter |
| Inflation (FY26) | 3.2% | Revised downward due to lower food inflation |
| Monetary Policy Outlook | 25 bps rate cut expected | RBI expected to adjust policy given low inflation |
| Key Growth Drivers | Strong domestic demand, benign monsoon, income tax & GST cuts, accelerating government investment | Consumption and investment expected to rise significantly |
Unclaimed Deposits
- The Reserve Bank of India (RBI) has directed all banks to launch a 3-month drive (October–December 2025) to settle unclaimed funds such as deposits, dividends, interest warrants, and pensions.
| Feature | Details |
|---|---|
| Types of Unclaimed Deposits | - Savings/Current Account Balances: Dormant accounts - Fixed/Recurring Deposits: Maturity proceeds not claimed - Interest Warrants & Dividends: Payments issued but not encashed - Pension/Gratuity Payments: Benefits unclaimed by beneficiaries |
| Time Frame | - Savings/Current Accounts: Not operated for 10 years - Term Deposits: Not claimed within 10 years from maturity - Such funds are transferred to Depositor Education and Awareness (DEA) Fund at RBI - Depositors can claim funds later with applicable interest |
| Handling by Banks | - Maintain separate ledger for unclaimed deposits - Periodic reporting to RBI is mandatory - May transfer funds to DEA Fund or Unclaimed Deposits Fund per RBI norms |
FACE: India’s First Fintech SRO Expands Beyond Digital Lending
- The Fintech Association for Consumer Empowerment (FACE) is India’s first Self-Regulatory Organisation for Fintech, recognised by the Reserve Bank of India (RBI) in July 2024.
- The Fintech Association for Consumer Empowerment (FACE), recognised by the RBI in July 2024 as India’s first Self-Regulatory Organisation for Fintech (SRO-FT), has emerged as a key industry body within just one year of recognition.
- Facilitates engagement between fintech players and regulators.
- Autonomy: Operates independently but follows RBI oversight.
Centre May Get Powers to Empanel Private ODR Firms for MSME Delayed Payments
| Aspect | Current Scenario | Proposed Changes |
|---|---|---|
| MSME ODR Portal | Launched in June 2025; allows MSMEs to file digital claims and monitor disputes with large firms, PSUs, and government agencies. | N/A |
| Authority for Empanelment | Currently, only state governments can empanel private ODR firms via MSEFCs under the MSME Development Act, 2006. | Central government to be empowered to empanel private ODR service providers, similar to states. |
| Effectiveness | State-level MSEFCs are largely ineffective: - 250,000+ claims pending - Less than 10% resolved mutually | Strengthen dispute resolution, especially in regions with limited private ADR institutions (e.g., north-eastern states, tier-II/III cities). |
| Implementation Status | Active portal, but resolution backlog exists | Proposal in progress; implementation may take time |
SEBI-Registered Investment Advisers (RIAs)
- Regulatory Oversight: Governed by SEBI (Investment Advisers) Regulations, 2013. Subject to audits, compliance checks, and penalties for violations.
- Governed by SEBI (Investment Advisers) Regulations, 2013.
- Sebi-registered investment advisers (RIAs), who provide fee-based, conflict-free financial advice, have seen their numbers shrink sharply—from 1,350 a few years ago to 962—despite growing investor demand for unbiased guidance.
- Scope of Advice: Securities including stocks, bonds, mutual funds, derivatives. Portfolio management and financial planning. Personalized recommendations based on client’s risk profile, investment horizon, and financial goals.
| Category | Challenges | Details / Impact |
|---|---|---|
| Regulatory Complexity | Registration & Membership | RIAs must obtain SEBI registration and BASL membership (BSE subsidiary) for supervision. |
| Compliance Burden | Multiple requirements: PMLA/KYC updates, record-keeping, marketing approvals; consume significant time and resources. | |
| Application Delays | Delays in processing applications and renewals leave advisers in limbo, affecting client onboarding. | |
| Operational Burden | Resource Constraints | Individual and mid-sized RIAs often lack funds or manpower to meet compliance needs. |
| Cost & Time | Monthly compliance can cost ₹2.5–3 lakh and require 15–20 hours of work per month. | |
| Impact on Advisers | Licence Surrenders | Some advisers surrender licences due to regulatory uncertainty. |
| Partial Relief | New relaxations (removal of CIBIL reports, proof of address, net worth statements) helpful, but accountability and communication gaps persist. |
Bank of Baroda Launches eRUPI P2P Digital Gifting on bob इ(e) Pay UPI
- Launch: Bank of Baroda (BoB) introduced eRUPI Person-to-Person (P2P) digital gifting on its bob इ Pay UPI app.
- Voucher Value: ₹1 to ₹10,000; users can issue unlimited vouchers subject to daily UPI transaction limits.
- Security: Vouchers are non-transferable and refunded if unredeemed within validity.
HSBC India PMI: September 2025
- HSBC India’s Flash Purchasing Managers Index (PMI) for September 2025 indicates moderation in growth momentum in both manufacturing and services sectors amid global trade tensions and domestic policy changes.
| Indicator | September 2025 | August 2025 | Trend / Observation |
|---|---|---|---|
| Manufacturing PMI | 58.5 | 59.3 | Expansion continues (PMI > 50), but growth moderated; new export orders slowest rise in 6 months due to 50% US tariffs; domestic demand resilient via festive season & GST cuts. |
| Services PMI | 61.6 | 62.9 | Continued expansion, slightly slower than August. |
| Composite PMI Output | 61.9 | 63.2 | Sustained expansion in overall economic activity. |
| Input Costs | Moderated | - | Manufacturers reported higher costs for cotton, steel, oil; services firms saw slower wage-driven expenses. |
| Output Charges | Rose at slower pace | - | Despite factory-gate prices climbing at fastest rate in 12 years. |
| Employment | Manufacturing: 3% hiring; Services: 5% hiring | - | Job creation cooling, especially in private sector. |
GST Appellate Tribunal (GSTAT) Launched
- Digital Platform: GSTAT e-Courts Portal for filing appeals, tracking cases, and participating in digital hearings. Staggered filing allowed up to 30 June 2026. Comprehensive guidance including FAQs, notes, and instructional videos available.
- Staggered filing allowed up to 30 June 2026.
| Aspect | Details |
|---|---|
| Objectives | - Provide a nationwide, specialized forum for GST disputes - Ensure jargon-free, transparent, and time-bound appellate decisions - Facilitate digital-by-default filings and virtual hearings - Reduce legal friction, enhance cash flows for MSMEs and exporters, and instill trust in the tax system - Uphold the principle of ‘One Nation, One Forum for Fairness and Certainty’ |
| Structure & Composition | Principal Bench: New DelhiState Benches: 31 Benches across 45 locations in India |
| Members per Bench | - 2 Judicial Members - 1 Technical Member (Centre) - 1 Technical Member (State) |
| Purpose of Composition | Designed to balance judicial expertise and technical knowledge from both Central and State administrations |
RBI Issues Directions for Digital Payment Transaction Authentication Mechanism
- The Reserve Bank of India (RBI) has issued new guidelines mandating two-factor authentication (2FA) for all digital payment transactions in India, effective April 1, 2026, to enhance transaction security and reduce fraud.
- Cross-Border Transactions: International card-not-present (CNP) transactions require additional authentication from October 1, 2026.
- International card-not-present (CNP) transactions require additional authentication from October 1, 2026.
- Issuer Responsibilities: Banks and non-bank payment service providers must comply with the guidelines. Systems must be robust, user-friendly, and secure.
Qatar Enables UPI Payments, Qatar Duty Free Becomes First Merchant
| Aspect | Details |
|---|---|
| Partnership | NIPL (subsidiary of NPCI) with Qatar National Bank (QNB) |
| Technology Provider | NETSTARS’ payment solution powers the integration |
| Coverage | UPI-enabled QR code payments accepted across Qatar via QNB-acquired merchants |
| First Merchant | Qatar Duty Free outlets |
| Benefit | Indian tourists can make instant, secure, and seamless payments via UPI at major tourist locations |
Sebi Compliance Rules Spotlight Social Impact Auditors Amid SSE Growth
- Launched in 2022, SSE allows non-profits and social enterprises to raise funds from the public.
- Sebi Circular (19 September 2025): Mandatory Annual Impact Report (AIR) audits now apply only to social enterprises that have successfully raised funds through the SSE.
- Non-compliance can attract penalties ranging from ₹1 lakh per day to ₹1 crore, along with potential delisting and loss of tax benefits.
- Around 1,000 social auditors are currently enrolled under ICAI, ICSI, and ICMAI-linked self-regulatory organizations.
RBI’s Supervisory Data Quality Index (sDQI) Improves in June 2025
- Index Score: Improved to 89.9 (June 2025) from 89.3 (March 2025).
- No bank scored below 80, showing improvement across the sector.
- Small Finance Banks (SFBs): Improved slightly from 90.6 (March 2025) to 90.7 (June 2025).
- Coverage: 87 Scheduled Commercial Banks.
Real-Time US Dollar Settlement Platform to Launch in GIFT City
- Standard Chartered Bank, CCIL IFSC Ltd, and the International Financial Services Centres Authority (IFSCA) are set to launch a real-time settlement platform for US dollar-denominated trades in GIFT City, Gandhinagar, Gujarat, likely on October 7, 2025.
- The platform will enable real-time settlement of USD trades, reducing current settlement times which take several hours.
- Standard Chartered Bank is the sole banking partner for the platform.
- CCIL IFSC Ltd, a subsidiary of the Clearing Corporation of India Ltd (CCIL), will act as the payment system operator (PSO) for the foreign currency settlement system (FCSS).
NBFC Retail Bad Loans Outlook for FY26
- Trend of Retail NPAs: NPAs will rise moderately in FY26 but remain below the pandemic peak of over 5% in FY22. The increase is linked to continued credit growth and rising vehicle loan exposure.
- NPAs will rise moderately in FY26 but remain below the pandemic peak of over 5% in FY22.
- Risks include: Decline in collateral values. Lower vehicle utilisation due to increased supply. Potential stress on borrowers’ cash flows.
- Potential stress on borrowers’ cash flows.
Transmission of Monetary Policy to NBFC Borrowing and Lending Rates
| Aspect | Key Highlights |
|---|---|
| Borrowing Side | - Dependence on bank and market borrowings; no direct access to LAF - Repo rate cuts don’t immediately lower NBFC funding costs- Borrowing costs depend on liquidity conditions & risk perception - Empirical finding: 1% repo rate change → 0.24% change in WABR (over 3 quarters) - Larger, profitable NBFCs borrow at lower rates |
| Lending Side | - NBFCs serve riskier borrowers, charging higher rates to cover defaults - Lending rates less responsive to policy rate changes - Empirical finding: 1% repo rate change → 0.33% change in WALR (over 3 quarters) |
| NBFC Sector Overview (Dec 2024) | - Asset quality improved: GNPA 3.4%, NNPA 1.2% - Credit portfolio: Industry + Retail = 72% of total - Retail loans growing double digits; industry & services moderate growth - Funding sources: Markets 38.7%, Banks 37.4%, ECBs rising (43% in FY25 vs 27.2% in FY24) |
| Digital & AI Integration | - NBFCs advised to proactively manage cyber risks - AI adoption to improve efficiency & service delivery |
New Development Bank (NDB) Plans First Rupee-Denominated Bond in India
- If the New Development Bank (NDB) issues a ₹-denominated bond worth ₹4,000 crore, investors buy it in rupees, and NDB must repay in rupees (interest + principal).
- The New Development Bank (NDB), a multilateral development bank established by BRICS countries (Brazil, Russia, India, China, South Africa), plans to issue its first rupee-denominated bond in the Indian domestic market before March 2026. The move is aimed at providing local currency financing for Indian projects and is seen as a step towards the internationalisation of the Indian rupee.
- Issuers: Can be issued by Indian entities (government, corporates, NBFCs, banks) in domestic markets. Also issued by foreign institutions like the International Finance Corporation (IFC) or the New Development Bank (NDB) to raise funds in rupees.
- Investor Base: Attracts both domestic and foreign investors who want exposure to India’s growth story.
RBI Stops Dollar Purchases in July 2025 Amid Rupee Depreciation
- The Reserve Bank of India (RBI) refrained from purchasing US dollars in July 2025, marking the first zero-dollar purchase month since February 2014. Instead, the central bank sold dollars to stabilise the rupee.
- Rupee Depreciation: The rupee fell 2.23% in July 2025, its sharpest monthly fall of the year. Earlier declines: May (1.21%), January (1.16%), February (1.02%).
- The rupee fell 2.23% in July 2025, its sharpest monthly fall of the year.
- External Pressures: US imposed 50% tariff on Indian goods (effective August 27, 2025). Geopolitical tensions (Russia-Ukraine, Israel-Iran). Foreign investor outflows added stress on the rupee.
| Reason | Details |
|---|---|
| Stabilise the Rupee | Rupee depreciated 2.23% in July 2025; RBI sold $2.54 billion to curb volatility. |
| Policy Priority Shift | RBI prioritized currency stability over reserve accumulation to prevent inflation, investor panic, and rising import costs. |
| External Pressures | US tariffs, foreign capital outflows, and geopolitical tensions contributed to rupee depreciation, RBI’s dollar sales eased market panic. |
Weakness of Rupee
- INR has depreciated over 3% since Jan 2025, sharper than many emerging markets.
- Against Other Majors: Weakened versus euro and pound, indicating broad-based depreciation.
| Cause | Details / Explanation |
|---|---|
| Trade Imbalance | - Exports stagnant due to global protectionism. - High imports of oil (~85% dollar-priced), electronics, fertilizers → worsens current account deficit (CAD). |
| Investment Slowdown | - Weak corporate earnings and global uncertainty → FPI and FDI inflows sluggish or negative. - Example: Net FPI outflows of $1.5 bn recently, reducing dollar supply. |
| Relative Currency Demand | - Higher global demand for USD over INR, especially amid global financial tightening. |
| Growth Concerns | - Subdued GDP growth (~6.1% in Q1 FY26) lowers investor confidence. |
| Global Financial Tightening | - Attractive US asset returns pull capital out of India. |
Bank of Baroda Gains Approval for Bullion Exchange Operations at GIFT City
- Participants: Banks, financial institutions, bullion dealers, exporters/importers, and sometimes retail investors.
- Regulation: Exchanges are usually regulated by a financial authority, ensuring fairness and transparency.
RBI Survey on International Trade in Banking Services (ITBS) 2024–25
- The Reserve Bank of India (RBI) released its annual Survey on International Trade in Banking Services (ITBS) for 2024–25, highlighting the performance of Indian banks’ overseas operations and foreign banks in India.
| Category | Indian Banks Abroad | Foreign Banks in India |
|---|---|---|
| Branch / Employee Growth | - Overseas branches ↑ 1.9% - Employee strength ↑ 6.1% | — |
| Consolidated Balance Sheet Growth | - Branches ↑ 9.1% - Subsidiaries ↑ 4.2% | ↑ 17.5% |
| Credit Growth | Lending ↑ 5.6% | ↑ 8.4% |
| Deposit Growth | Deposit mobilisation ↑ 9.4% | ↓ 6.8% (vs. 16.4% last year) |
| Income & Profitability | - Overseas branches: • Interest income ↑ 8% (vs. 72% last year) • Interest expenses ↑ 9% (vs. 87.5% last year) • Income-to-assets ratio ↓ 5.9% - Subsidiaries: • Income-to-assets ratio ↑ 7.4% | - Subsidiaries: Income-to-assets ratio ↓ 7.1% |
| Fee Income Trends | ↑ 4.3% | ↑ 9.4% |
| Main Fee Income Drivers | Credit-related services, trading, payments, trade finance | Same (credit-related, trading, payments, trade finance) |
NPCI International & QNB Enable UPI Payments for Indian Travellers in Qatar
- In September 2025, NPCI International Payments Limited (NIPL), a wholly owned subsidiary of NPCI, in partnership with Qatar National Bank (QNB), launched QR-based Unified Payments Interface (UPI) services for Indian travelers in Qatar.
- First Merchant: Qatar Duty Free, Hamad International Airport, Doha.
- UPI Integration: Qatar becomes the 8th country to adopt UPI, after Bhutan, France, Mauritius, Nepal, Singapore, Sri Lanka, and UAE.
- Payment Conversion: Transactions settle instantly, converting INR to QAR at prevailing forex rates.
RBI Renews Statement of Commitment to FX Global Code
- Review: Reviewed twice by the Global Foreign Exchange Committee (GFXC) – first in July 2021 and later in December 2024.
- First Published: The FX Global Code was first published in 2017.
- In September 2025, the Reserve Bank of India (RBI) reaffirmed its commitment to global best practices in the foreign exchange (FX) market by renewing its Statement of Commitment (SoC) to the FX Global Code.
- Objective: Sets global principles of good conduct to promote the integrity and effective functioning of the wholesale FX market.
SEBI Raises Custodian Net Worth Requirement to ₹75 Crore
- In September 2025, the Securities and Exchange Board of India (SEBI) increased the minimum net worth requirement for custodians from ₹50 crore to ₹75 crore to strengthen risk management systems.
- Regulatory Amendment: Through the SEBI (Custodian) (Amendment) Regulations, 2025, modifying the SEBI (Custodian) Regulations, 1996.
- Separate Capital Requirement: New capital adequacy must be maintained separately from other business funds. This means that custodians must keep the funds required to meet SEBI’s new minimum net worth (Rs 75 crore) distinct from any other business or operational funds.
- Custodian: In the financial markets, a custodian is a specialized financial institution that safeguards and manages financial assets on behalf of clients, such as mutual funds, banks, corporations, or individual investors.
Societe Generale expands in India with the launch of the GIFT City branch
- Leadership: Headed by Mihir Baxi, who will also continue as Director, Corporate Coverage, Societe Generale India.
- Focus Sectors: Investment-intensive sectors including: Renewable energy Roads and transportation infrastructure Transmission infrastructure Data centres Technology and telecommunications
- Location & Purpose: India’s first operational International Financial Services Centre (IFSC) in Gandhinagar, Gujarat; aims to be a global financial hub.
- Purpose: Strengthen the bank’s ability to deliver innovative and tailored structured finance solutions.
Context:
| Aspect | Details |
|---|---|
| FinTech Innovation Hub | A 1,000 sq. ft. hub to be set up at Kerala Bank’s IT Department, Kakkanad (Kochi). |
| Startup Support | Cohort-based FinTech Accelerator programmes to identify and nurture promising startups. |
| Co-Creation | Development of digital banking solutions tailored for Kerala Bank and cooperative banking sector. |
| Role of KSUM | Kerala Startup Mission (KSUM) will handle: - Setting up the hub - Designing accelerator programmes - Incubation and technical advisory - Investor relations - Access to funding schemes (innovation grants, seed loans) |
Nidhi Aapke Nikat
- The Employees’ Provident Fund Organisation (EPFO) will organise its monthly outreach initiative, Nidhi Aapke Nikat, on 29 September 2025 across multiple districts in India. The programme aims to provide pensioners and stakeholders with doorstep services and grievance redressal.
- Facilitate submission of Digital Life Certificates (DLCs) for pensioners.
- Provide on-the-spot assistance and grievance resolution for employees, employers, and pensioners.
- Camps are usually held on the 27th of every month; if the date falls on a holiday, the programme is shifted to the next working day.
RBI Issues Revised Directions for Settlement of Deceased Customers’ Accounts and Lockers
- If settlement is delayed due to the bank: Deposit accounts: Interest at Bank Rate + 4% per annum on the due settlement amount. Lockers/articles in safe custody: Rs 5,000 per day of delay.
- Deposit accounts: Interest at Bank Rate + 4% per annum on the due settlement amount.
- For safe deposit lockers and articles in safe custody, banks must process claims within 15 days and coordinate inventory with claimants.
- Threshold limits: Co-operative banks: Rs 5 lakh Other banks: Rs 15 lakh (banks may set higher limits)
India’s Shift Towards a Diversified Credit Ecosystem
- RBI open tap bank licensing policy: Continuous applications for new bank licenses Encourages entry of specialized banks (small finance, digital-first) Enhances collaboration between banks, NBFCs, and fintechs
- Diversification: Non-bank channels complement banks, making credit delivery more resilient.
- Encourages entry of specialized banks (small finance, digital-first)
- Access and Inclusion: Expands reach to underserved and thin-file borrowers.
| Category | Details / Examples |
|---|---|
| Lending Growth | - NBFC loans reached ₹6.1 lakh crore (20% YoY increase). - Crucial for MSMEs, semi-urban, and underserved segments. |
| Key Advantages | - Flexible product design and repayment terms. - Strong local presence and contextual understanding. - Use of alternative data and AI for thin-file customers. - Digital channels enable faster, tailored lending. |
| Funding Diversification | - Access to corporate bonds, securitisation, co-lending partnerships, and external borrowings. - Innovations include first-loss default guarantees, API-led digital co-lending, and retail participation in loan pools. |
| Regulatory Support | - Rollback of higher risk weights on bank lending to NBFCs lowered borrowing costs. - Enabled competitive expansion of lending portfolios. |
BNPL (Buy-Now-Pay-Later) Platforms
- Reason: Operating a payment system without RBI authorisation, which violates the Payment and Settlement Systems Act, 2007.
- 2022 Ruling: BNPL firms were barred from topping up prepaid payment instruments using borrowed funds, bringing them closer to digital lending regulations.
- BNPL (Buy-Now-Pay-Later) platforms have rapidly grown in India, offering instant credit to consumers and smooth checkout solutions for merchants.
- RBI’s concerns include: Unsecured lending risks Weak regulatory oversight Poor consumer protection
| Regulation / Act | Applicability to BNPL Providers |
|---|---|
| Reserve Bank of India Act, 1934 | Grants RBI authority to regulate both banking and non-banking financial institutions. |
| Banking Regulation Act, 1949 | Applicable if the BNPL provider functions as a bank. |
| NBFC Regulations | Applicable if the BNPL provider operates as an NBFC: • RBI (NBFC) Directions • Digital Lending Guidelines, 2022 (under RBI supervisory powers over NBFCs and digital lenders). |
| Payment and Settlement Systems Act, 2007 | Applicable if the BNPL provider issues prepaid payment instruments (PPIs). |
NaBFID Partners with World Bank & ADB for $1 Billion Credit Enhancement Facility
- Suppose an AIF scheme = ₹1,000 crore total size.
- 20% cap rule: All RBI-regulated entities together (banks, NBFCs, etc.) can invest maximum ₹200 crore in that scheme.
- 10% per entity rule: A single bank/NBFC cannot invest more than ₹100 crore in that ₹1,000 crore scheme.
- Addresses India’s infrastructure financing gap (over 5% of GDP).
Multi-Commodity Exchange of India (MCX) & Gold and Silver Exchange-Traded Funds (ETFs)
- MCX: Allows delivery of 100g Indian-made gold bars but not for 1kg benchmark contracts.
- Introduced in India: 2007.
- Introduced in India: 2021 (SEBI permitted AMCs to launch them).
- Headquartered in Mumbai, plays a key role in price discovery and risk management for commodities.
National Pension System (NPS) Reforms
- Lump-Sum Withdrawal Cap Increased: Current cap: 60% New cap: 80% Remaining 20% retained for annuity purchases. Reduces the deterrent of having a large portion locked up, enhancing scheme attractiveness.
- The National Pension System (NPS), which became available for the non-government sector in 2009, has evolved over the last 16 years, and today it is considered one of the most reliable retirement investment options.
- Non-government employees can invest 100% in equities if they wish.
- Current cap: 60%
NPS vs UPS
- Only 1.37% of eligible staff opted for UPS as of July 2025 (Finance Ministry, Lok Sabha).
- Launched 2004, for employees joining after Jan 1, 2004.
- Deadline: September 30, 2025, for central government employees to opt between NPS or Unified Pension Scheme (UPS).
- At retirement, up to 60% of corpus tax-free; remaining used to purchase annuity.
| Scheme | Employee Contribution | Employer Contribution | Withdrawals | Pension Taxability |
|---|---|---|---|---|
| NPS | Deduction under 80CCD(1) | Government: 80CCD(2) | 60% tax-free; rest used for annuity | Taxable as income (annuity portion) |
| UPS | Same as NPS | Same as NPS | 60% similar; excess taxed as salary | Pension taxable as income |
Life Insurance Industry Plans to Pass GST ITC Impact to Distributors
- Despite ITC removal, insurers passed the nil GST benefit to customers starting Sept 22, 2025.
- Denial of ITC on commissions paid to agents (18% GST) increases costs for insurers.
- To protect margins of insurers while maintaining affordability for policyholders.
- To accommodate differences in commission structures across insurers and distributors, a uniform approach may be challenging.
RBI Introduces Forward-Looking Guidelines on Digital Payment Authentication
- Technology-Agnostic Approach: Issuers and regulated entities can adopt flexible authentication methods without being limited to a specific technology.
- Enhanced Security for Vulnerable Users: First-time digital users, particularly in semi-urban and rural areas, will benefit from stronger safeguards against fraud.
- For Consumers: Safer and seamless transactions; reduced risk of phishing and fraud.
- For Payment Issuers: Flexibility to adopt modern authentication methods; enhanced operational resilience.
SWIFT and Global Banks Collaborate on Instant Cross-Border Payments
- Global Reach: SWIFT network connects 11,000+ banks across 200+ countries, handling trillions of dollars daily. Initiative leverages this existing infrastructure while adding blockchain functionality.
- SWIFT network connects 11,000+ banks across 200+ countries, handling trillions of dollars daily.
- Blockchain-Based Shared Ledger: Banks will use a secure, real-time distributed ledger to record, sequence, and validate transactions. Smart contracts will enforce rules automatically, improving efficiency and reducing errors.
- Smart contracts will enforce rules automatically, improving efficiency and reducing errors.
Agriculture · 24
Krishi Nivesh 2.0
- Launched by the Ministry of Agriculture & Farmers’ Welfare to improve ease of doing agri-business and attract private investments in Indian agriculture.
- Agriculture faces post-harvest losses of 6% annually (~₹1.2 trillion) due to gaps in storage, processing, and logistics.
- The government is expanding digital technology use in agriculture by integrating public-private partnership (PPP) schemes into the Krishi Nivesh portal, launched in September 2024. This move aims to streamline agricultural investments, improve service efficiency, and attract private sector participation.
- A single-window digital platform for investors, agri-entrepreneurs, FPOs (Farmer Producer Organisations), and start-ups.
India Produces Mono-Floral Lavender Honey in Kashmir
- Honey derived majorly from nectar of a single flower type (≥80% of nectar source).
- Confirmed with 61% lavender pollen concentration through scientific testing.
- Expanded significantly since 2014, now spread over 750 hectares across J&K.
- Over 3,000 families involved; featured in 2024 Republic Day Parade tableaux.
BHARATI Initiative
- Achieve $50 billion agri-food exports by 2030.
- Startup Cohort: Selection of 100 startups through APEDA’s website (applications open September 2025).
- The Agricultural and Processed Food Products Export Development Authority (APEDA) has launched the BHARATI initiative to support 100 agri-food startups and enhance India’s agri-food export potential.
- Support and empower 100 agri-food and agri-tech startups.
Horticulture as a Growth Engine
- Post-Harvest Losses Annual food wastage and inefficiencies valued at ₹1.5 trillion. Inadequate cold chains, storage, refrigerated transport, and agro-processing facilities.
- Annual food wastage and inefficiencies valued at ₹1.5 trillion.
- Productivity Concerns Stagnant or declining yields in crops like grapes and sapota (1992–93 to 2021–22). Vulnerability to climate variability (e.g., unseasonal rains damaging perishable crops).
- Stagnant or declining yields in crops like grapes and sapota (1992–93 to 2021–22).
Kapas Kisan App
- On 2 September 2025, Union Minister of Textiles Shri Giriraj Singh launched the Kapas Kisan mobile app, developed by the Cotton Corporation of India (CCI) under the Ministry of Textiles, in New Delhi. The app aims to digitize cotton procurement under the Minimum Support Price (MSP) scheme, empowering farmers with transparency and efficiency in the procurement process.
- Purpose: To streamline cotton procurement under the MSP scheme and protect farmers from distress sales.
- Launched by: Union Minister of Textiles, Shri Giriraj Singh
- Self-Registration: Farmers can securely register to sell cotton under MSP.
SLCM Partners with IDBI Bank and Punjab & Sind Bank
- Objective: To enable farmers, traders, and SMEs to use their stored agri-produce as collateral for loans.
- With this collaboration, SLCM now has 27 banking partners across India and Myanmar.
- In September 2025, Sohan Lal Commodity Management Limited (SLCM), India’s largest post-harvest logistics and agri-solutions company, entered into a partnership with IDBI Bank Limited and Punjab & Sind Bank to provide unified collateral management services across India.
- This marks Punjab & Sind Bank’s first venture into collateral management services.
NABARD Takes Steps to Secure GI Tag for Jharkhand’s Traditional Products
- Kuchai Silk Sarees – Seraikela Kharsawan
- Kuchai Turmeric – Seraikela Kharsawan
- Objective of GI Tagging: Prevent imitation and ensure authenticity. Enhance market credibility for traditional products. Open national and global market opportunities for artisans.
- NABARD’s Promotion Strategy: Authorized user enrollment for GI products. Branding and marketing support. Market linkages and participation in fairs.
5th Farmer Producer Organisation (FPO) Conclave by Samunnati & NABARD
- Aimed to integrate smallholder farmers into mainstream markets and promote rural entrepreneurship.
- Launch of ACCESS SAP Report on Social Procurement: Focused on responsible procurement practices. Aimed to integrate smallholder farmers into mainstream markets and promote rural entrepreneurship.
- Perspectives on Agri Marketing: Discussed the evolution from local haats to global value chains.
NCEL and APEDA Sign MoU to Boost Cooperative-Led Agricultural Exports
- Established: 25 January 2023, under the Multi-State Cooperative Societies Act, 2002.
- Headquarters: New Delhi.
- National Cooperative Exports Limited (NCEL) and Agricultural and Processed Food Products Export Development Authority (APEDA) signed a Memorandum of Understanding (MoU) to enhance agricultural exports driven by cooperatives.
- Strengthen farmers’ income through international market access.
FPO Ecosystem in India
- Low equity capital: Only 387 FPOs have paid-up capital exceeding ₹15 lakh.
- Increase farmers’ bargaining power in the market.
- Promote sustainable farming and better income for members.
- Encourage farmers to contribute equity capital to fund infrastructure and generate additional income.
FPOs Critical to Agtech Adoption in Rural India
- Collective Bargaining and Affordability: FPOs allow farmers to pool resources, making modern inputs, machinery, and digital agtech tools more affordable and accessible.
- FPOs allow farmers to pool resources, making modern inputs, machinery, and digital agtech tools more affordable and accessible.
- Access to Finance and Credit: Through FPOs, farmers gain better access to credit, subsidies, and financial products necessary for technology adoption. FPOs also help engage with banks, NBFCs, and government schemes.
- Through FPOs, farmers gain better access to credit, subsidies, and financial products necessary for technology adoption. FPOs also help engage with banks, NBFCs, and government schemes.
AI-Powered Monsoon Forecasts Transform Kharif Farming in India
- Targeted Dissemination: Forecasts were sent via m-Kisan SMS platform to 3.8 crore farmers across 13 states, providing region-specific guidance up to four weeks in advance.
- Forecasts were sent via m-Kisan SMS platform to 3.8 crore farmers across 13 states, providing region-specific guidance up to four weeks in advance.
- Real-Time Monitoring: Weekly updates informed farmers of mid-season variations, such as pauses in rainfall, enabling timely agricultural interventions.
- Weekly updates informed farmers of mid-season variations, such as pauses in rainfall, enabling timely agricultural interventions.
Corteva Agriscience Launches New Pesticides for Potato and Grapes
- Features of the New Pesticide: Fast action: Protected from wash-off within 20 minutes of spraying. Consistent protection: Active ingredients provide strong, long-lasting control. Crop benefits: Healthier crops, higher yields, and improved quality of produce.
- Fast action: Protected from wash-off within 20 minutes of spraying.
Union Government Announces Annual Opium Licensing Policy 2025-26
- In India, opium cultivation is strictly regulated under the Narcotic Drugs and Psychotropic Substances (NDPS) Act, 1985.
- Approximately 1.21 lakh farmers eligible for licenses – 23.5% increase from previous year.
- The Union Government today announced the annual licensing policy for crop year 2025-26 during the Opium Crop Year from 1st October, 2025 to 30th September, 2026, of license for cultivation of opium poppy, for the farmers in the states of Madhya Pradesh, Rajasthan and Uttar Pradesh.
- Farmers require a license from the Central Government to cultivate opium.
Agriculture Must Adapt to Changing Weather Patterns
- The 2025 southwest monsoon has started withdrawing a little earlier than usual, after recording about 7% excess rainfall. Forecasts indicate La Niña conditions by October and a colder-than-normal winter ahead. These shifting weather patterns bring both opportunities and risks for Indian agriculture.
- Strong monsoon impact: Reservoirs are filled, and soil moisture is high, which supports Kharif harvests and sets a good base for Rabi sowing.
- Cold weather benefits: Farmers in Rajasthan and North India expect better yields of wheat, barley, and mustard, which thrive in cooler conditions.
- Unseasonal Rain: Downpours at harvest can damage crops, reduce quality, and trigger food inflation (notably for perishables like fruits and vegetables).
BASAI 2025: Conference on Biologicals for Sustainable Agriculture
- The Biological Agri Solutions Association of India (BASAI) will host BASAI 2025, a two-day conference on ‘Biologicals for sustainable agriculture. A climate resilient approach’ in New Delhi on September 22–23.
- Promote climate-resilient and sustainable farming through the use of bio-stimulants, biofertilizers, and biopesticides.
- Women’s leadership in agri-biologicals
- Knowledge Sharing: Sessions and discussions to guide policymakers, farmers, and industry stakeholders.
EDII & NABARD Launch Regional GI Facilitation Centre in Gujarat
- To support artisans and entrepreneurs in Gujarat by facilitating Geographical Indication (GI) registration for traditional crafts and agro-products.
Centre for Startups and FPOs Launched in Madurai
- Objective: To provide a conducive environment for the growth and development of startups and FPOs, fostering innovation and entrepreneurship in the agricultural sector.
- Support Mechanisms: Entrepreneurs and FPOs will receive mentorship, networking opportunities, and guidance on business strategies, financial planning, and market access.
- Collaborations: The initiative involves partnerships with various stakeholders, including government agencies, educational institutions, and industry experts, to ensure comprehensive support for the beneficiaries.
BASAI Seeks Clarity on GST for Biostimulants
- At present, some authorities classify biostimulants under 5% GST, while others under 18% GST.
- Notices have recently been issued to some companies, asking them to pay 18% GST.
- BASAI argues they should be taxed at 5%, similar to fertilizers, to make them affordable for farmers.
- Invalidation of Provisional Registrations Government recently invalidated 8,000+ provisional registrations of biostimulants. Only notified products remain valid; others must align with standards to re-enter the market.
HyFarm Paathshala: Empowering Farmers with Knowledge
- Over 30 farmers and their families in North Gujarat participated in the pilot project.
- Pilot Project and Convocation Over 30 farmers and their families in North Gujarat participated in the pilot project. Farmers were honored at the first-ever Paathshala Convocation Ceremony in Ahmedabad. These trained farmers are now seen as pioneers in potato cultivation.
- Farmers were honored at the first-ever Paathshala Convocation Ceremony in Ahmedabad.
- These trained farmers are now seen as pioneers in potato cultivation.
NABARD Rural Sentiment Survey September 2025
- In July 2025, nearly 75% of rural households expected their incomes to rise in the next year.
- By September 2025, this figure fell to 72.8%.
- Inflation expectations eased further: Average perceived inflation: 4.09% (down ~150 basis points since Nov 2024). Median inflation perception: 3%.
- Average perceived inflation: 4.09% (down ~150 basis points since Nov 2024).
Brazil–India Cross-Incubation Programme in Agritech (Maitri 2.0)
- Dr. Jat highlighted the 77-year-long partnership between India and Brazil, including collaboration on BRICS and G20 platforms.
- Maitri 2.0 is envisioned as a two-way learning platform for co-creation between Indian and Brazilian innovators.
- Emphasis on commercialization as delivering public-funded innovations to end-users, not just generating revenue.
- Build resilient food systems and empower farmers
Soilification Technology
- Polymers: Cross-link sand particles to create structured soil.
- Reduced irrigation cycles (3–4 vs 5–6 in conventional desert farming).
- High yield: Wheat seed-to-harvest ratio of 1:20, double that of untreated desert soil.
India to Set Up 5 Modern Seed Breeding Facilities
- Breeding Cycle Reduction: Shortened from 6–10 years to 2–3 years, helping farmers access improved seeds faster.
- Impact: Enables multiple crop generations per year (up to four), compared to 1–2 under natural conditions.
Facts To Remember · 56
Union Minister Jyotiraditya Scindia launches India Mobile Congress- IMC 25 application
- Union Communications Minister Jyotiraditya Scindia, today launched the India Mobile Congress- IMC 25 application in New Delhi. With AI-based suggestions, improved networking, and interactive elements, the app aims to enhance users’ experience at the Expo.
Educate Girls NGO wins Ramon Magsaysay Award 2025, becomes first Indian organisation to get the honour
- An Indian non-profit organisation, ‘Foundation to Educate Girls Globally’, dedicated to mobilise community and government resources for girls’ education in rural and educationally disadvantaged areas of India, has been named a 2025 Ramon Magsaysay Awardee.
Earthquake Strikes Afghanistan
- A strong earthquake and multiple aftershocks collapsed homes onto sleeping families in a remote, mountainous region in Afghanistan, killing more than 800 people and injuring at least 2,800.
Ajay Seth takes charge as Irdai chief
- Ajay Seth, former secretary of the Department of Economic Affairs (DEA), assumed charge as the chairman of the Insurance Regulatory and Development Authority of India (Irdai) Ajay Seth has assumed charge as Chairman, Insurance Regulatory and Development Authority of India on 1st September, 2025.
Govt appoints Kalyani as new Controller General of Accounts
- The government has appointed T.C.A. Kalyani, a 1991-batch officer of the Indian Civil Accounts Service, as the country’s new Controller General of Accounts, the finance ministry said in a statement.
ISRO’s Announcement of Opportunity (AO) for Chandrayaan-3 Data Utilisation
- Chandrayaan-3 successfully achieved a soft landing on the Moon’s southern high latitudes on August 23, 2023, making India the first country to land near the lunar south pole. ISRO has invited proposals from the Indian scientific community for the scientific analysis and utilisation of Chandrayaan-3 lander and rover data.
India MedTech Expo 2025
- The second edition of the India MedTech Expo 2025 will be held in New Delhi from Thursday to showcase the country’s MedTech strength and innovation.
12-Day All India Thal Sainik Camp Inaugurated in New Delhi
- A twelve-day All India Thal Sainik Camp was inaugurated today in New Delhi. Ministry of Defence said that about 15 hundred cadets, from 17 National Cadet Corps (NCC) Directorates representing all states and union territories, will participate in the camp.
PM Modi receives first Made in India Vikram 32-bit chip
- Union Minister for Electronics & Information Technology Ashwini Vaishnaw presented Prime Minister Narendra Modi a memento containing the ‘Made in India’ Vikram 32-bit Processor Launch Vehicle Grade chip at the Semicon India 2025.
India Post Payments Bank (IPPB) Marks 8th Foundation Day
- On 1st September 2025, India Post Payments Bank (IPPB) marked its 8th Foundation Day, celebrating its role in delivering inclusive, accessible, and affordable banking services across rural, semi-urban, and remote regions.
India defeats Bahrain in AFC u-23 Asian Cup qualifiers
- India began its AFC under-23 Asian Cup qualifiers on a winning note with a 2-0 victory over Bahrain at the Suheim bin Hamad Stadium in Doha.
Union Cabinet Approves ₹1,500-Crore Incentive Scheme for Recycling of Critical Minerals
- The Union Cabinet on Wednesday approved a ₹1,500 crore incentive scheme to promote recycling of e-waste and battery waste for the extraction of critical minerals, a move aimed at strengthening India’s supply chain resilience in the sector.
Tata Capital’s $2 Billion IPO to Meet RBI Listing Mandate
- Tata Capital, the NBFC arm of Tata Group, is set to launch its ₹17,500 crore ($2+ billion) IPO in the third week of September 2025.
Karnataka Grameena Bank Adopts Common Logo for Amalgamated RRBs
- On 5th September 2025, Karnataka Grameena Bank (KGB), headquartered in Ballari, Karnataka, adopted the common logo designed for all 11 amalgamated Regional Rural Banks (RRBs) in India.
India rules Asia, books a World Cup spot
- India ended an eight year wait to be crowned the continental champion, winning 4-1 against defending champion Korea in the final of the Asia Cup here on Sunday and assuring itself of a spot at the 2026 World Cup.
PSBs Shut 1.5 Million Inoperative Jan Dhan Accounts
- Public-sector banks (PSBs) closed nearly 1.5 million inoperative zero-balance accounts under the Pradhan Mantri Jan Dhan Yojana (PMJDY) in April 2025 as a one-time exercise.
Nepal PM KP Oli Resigns!
- Nepal’s Prime Minister KP Oli resigned , officials confirmed, stepping down amid mounting pressure after one of the deadliest crackdowns in years left at least 19 people dead and reignited nationwide protests.
Sankarshan Thakur, senior journalist, passes away
- Sankarshan Thakur, Editor of The Telegraph, passed away in a Gurgaon hospital on Monday. He was 63.
Ministry of Statistics Invites Feedback on Draft National Industrial Classification (NIC) 2025
- The Ministry of Statistics and Programme Implementation has invited feedback on the draft National Industrial Classification (NIC) 2025.
India Likely to Avoid Legislation on Cryptocurrencies, Prefers Partial Oversight
- A recent government document (Sept 2025) indicates that India is unlikely to bring a dedicated law to regulate cryptocurrencies. Instead, the country will maintain partial oversight, given the risks of granting legitimacy to crypto assets and the challenge of regulating decentralised transactions.
Pooja ensures third medal for India
- Olympian Pooja Rani rallied to edge past Poland’s Emilia Koterska 3-2 in a hard-fought quarterfinal bout to move into the women’s 80kg semifinals and secure a third medal for India at the World boxing championships in Liverpool.
Govt Likely to Refocus on Marketing, Credit Support in PM Vishwakarma Scheme
- The PM Vishwakarma Scheme, launched by the Ministry of MSME to formalise and support traditional artisans and craftspeople, has already enrolled 3 million beneficiaries, surpassing its target three years ahead of FY28. The government is now shifting focus to the marketing and credit support components for the scheme’s next phase.
Public Sector Banks Manthan Summit 2025
- Public Sector Banks (PSBs) will hold a two-day Manthan Summit from September 12, 2025, focusing on strategies to transform into globally competitive institutions aligned with the vision of Viksit Bharat 2047.
Fiji ant numbers plunged after humans came
- Researchers sequenced the DNA of more than 4,000 specimens preserved in museums, representing over 120 species, and found that 79% of Fiji’s endemic ant species are now in decline, with losses starting soon after humans arrived about 3,000 years ago.
Retail Inflation Inches Up in August, Remains Below RBI Target
- Retail inflation, as measured by the Consumer Price Index (CPI), rose marginally to 2.07% in August 2025, up from 1.61% in July, according to the National Statistics Office (NSO). The second-quarter average (July-August) stands at 1.84%, lower than the RBI’s earlier projection of 2.1%. Since February 2025, inflation has remained below the RBI’s 4% target.
UPI daily payment limit set at ₹10 lakh
- India’s UPI system has enabled high-value transactions, allowing users to pay up to ₹10 lakh a day for investments, insurance, travel, credit cards and jewellery, starting today.
Unemployment Rate Slows to 4-Month Low: Govt Data
- According to the Periodic Labour Force Survey (PLFS) – August 2025, India’s unemployment rate for those aged 15 years and above fell to a four-month low, with male unemployment dipping to a five-month low, reflecting improved labour market conditions.
Swachhata Hi Seva Campaign 2025 Launched by Minority Affairs Ministry
- The Ministry of Minority Affairs has organised the Swachhata Hi Seva Campaign 2025 from today, which will continue till the 2nd of October on Gandhi Jayanti.
A change in mindset helped: Grand Swiss champion Vaishali
- India’s R. Vaishali defended her title in the Grand Swiss Chess League, which no other player in the open or women’s section had done before. But it was a tournament the 24-year-old from Chennai was not keen to play in the first place.
3 IIMs among worlds top 100B-schools: QS Global MBA Rankings
- Three Indian Institutes of Management (IIMs) Bangalore, Ahmedabad and Calcutta have figured in worlds top 100B-schools, according to QS Global MBA, Online MBA and Business Masters Rankings 2026.
Swachhata Hi Seva 2025
- The Department of Justice is observing the Swachhata Hi Seva Campaign 2025 under the Swachhotsav theme. The campaign will continue till 2 October to strengthen volunteerism and collective action for cleanliness.
Tokyo 2025: Neeraj Chopra Cruises into Final with First-Attempt 84.85m Throw
- India’s javelin star and World Champion Neeraj Chopra is once again in the spotlight as he gears up for the men’s javelin throw final at the World Athletics Championships 2025 in Tokyo, Japan, this afternoon. The match will begin at four PM indian timings.
Zeel downs Shruti in the final
- Top seed Zeel Desai recovered from being down 2-4 in the decider to beat first-time finalist Shruti Ahlawat 2-6, 6-1, 6-4 in the $15,000 ITF women’s tennis tournament at the Tennis Project, Baliawas.
Over 2.83 Lakh Health Camps Held Across India Under Swasth Nari Sashakt Parivar Abhiyaan
- The Ministry of Health and Family Welfare has said over 2.83 lakh health camps have been organized across the country under the Swasth Nari Sashakt Parivar Abhiyaan till 20th of this month. Launched on September 17th.
BIRC 2025 to Be Held at Bharat Mandapam, New Delhi
- Bharat International Rice Conference-BIRC 2025 will be held in New Delhi at Bharat Mandapam on 30th and 31st October. It is the world’s largest rice event with farmers, global buyers and stakeholders.
Tourism Ministry launches national young chef contest
- In order to promote Indian cuisine, a culinary contest is being organised for young chefs across the country by the Union Tourism Ministry for the first time.
Mohanlal to receive Dadasaheb Phalke Award
- The Ministry of Information & Broadcasting on Saturday announced that actor Mohanlal will be presented the country’s highest film honour, the prestigious Dadasaheb Phalke Award, for 2023. The award will be presented at the 71st National Film Awards ceremony on September 23.
ISLRTC organises programme to celebrate Sign Language Day 2025 in new delhi
- Indian Sign Language Research and Training Centre (ISLRTC), under the Department of Empowerment of Persons with Disabilities, will organise a programme to celebrate ‘Sign Language Day – 2025’, in New Delhi.
28th National Conference on e-Governance 2025 Kicks Off in Visakhapatnam
- The Department of Administrative Reforms & Public Grievances (DARPG) and the Ministry of Electronics & Information Technology (MeitY), in collaboration with the Government of Andhra Pradesh, are organising the 28th National Conference on e-Governance (NCeG) 2025, in Visakhapatnam.
India beats Pakistan in SAFF under-17
- The India under-17 men’s team beat Pakistan 3-2 at the Racecourse International Stadium in Colombo on Monday to go to the top of Group-B in the SAFF under-17 Championship 2025.
Ministry of Culture Hosts Three-Day Nadi Utsav Highlighting Rivers
- Indira Gandhi National Centre for Arts, under the Ministry of Culture, will hold the sixth edition of Nadi Utsav from the 25th of this month in New Delhi. Union Minister of Jal Shakti C R Patil will inaugurate the three-day event, which will highlight rivers as vital lifelines and cultural reservoirs.
World Food India 2025 Scheduled in New Delhi from September 25–28
- World Food India 2025 will be organised from 25th to 28th of September at Bharat Mandapam in New Delhi. The 4th edition of World Food India aims to promote investments in the diverse food processing sector, as well as introduce India’s rich food culture to the World.
Union Education Minister Dharmendra Pradhan launches Viksit Bharat Buildathon 2025
- Union Education Minister Dharmendra Pradhan today launched Viksit Bharat Buildathon 2025 in New Delhi. The initiative aims to nurture creativity, problem-solving, and self-reliance among youth.
Ayushman Bharat, the world’s largest govt-funded health assurance scheme, completes 7 years today
- Ayushman Bharat – Pradhan Mantri Jan Arogya Yojana completes seven years today. Launched in September 2018 from Ranchi, it is the world’s largest government-funded health assurance scheme. The scheme has transformed healthcare in India, reaching over 55 crore beneficiaries.
Dembele, Bonmati crowned the best in the world
- Ousmane Dembele won the Ballon d’Or for leading Paris Saint-Germain to its first Champions League title, and Aitana Bonmati received the women’s award for a third successive year.
Sahira prevails over Paola
- Sahira Singh kept her composure and played a strong game to outwit sixth seed Paola Lopez of USA 6-0, 4-6, 6-1 in the first round of the $15,000 ITF women’s tennis tournament at the Tennis Project, Baliawas.
World Para Athletics Championships declared open
- The 2025 World Para Athletics Championships (WPAC) was officially declared open at the Jawaharlal Nehru Stadium with a ceremony that aimed to highlight the infrastructure inclusivity at the upgraded venue.
Zeel and Akanksha in quarterfinals
- The top two seeds Zeel Desai and Akanksha Nitture were the only Indian players progressing to the singles quarterfinals of the $15,000 ITF women’s tennis tournament at the Tennis Project, Baliawas.
UPI Acceptance Expanded to Qatar
- NPCI International Payments Ltd. (NIPL), in partnership with Qatar National Bank (QNB), has enabled QR code-based UPI payments across Qatar.
Indian shooters Won Five Medals At The ISSF Junior World Cup
- In the ISSF Junior World Cup 2025, Indian shooters today clinched all three podium spots in the women’s 50m prone event at the Dr Karni Singh Shooting Range in New Delhi.
India Wins Asia Cup 2025
- Riding on Tilak Varma's incredible half-century, fancied India beat Pakistan by five wickets in the summit showdown to win their second Asia Cup title in the T20 format in Dubai.
First bullet train section to be completed by 2027
- India’s first bullet train project is progressing steadily, with the initial 50-km stretch between Surat and Bilimora in Gujarat set to open in 2027, Railway Minister Ashwini Vaishnaw announced. The entire Mumbai–Ahmedabad corridor is expected to be operational by 2029.
Dubai HDFC Bank barred from onboarding new clients
- HDFC Bank has been barred from onboarding new customers at its Dubai International Financial Centre branch by the local regulator.
India Calls for UN Reform at 80th UNGA Session
- India expressed readiness to take greater responsibilities at the UN. External Affairs Minister S. Jaishankar addressed the 80th session of the United Nations General Assembly (UNGA) in New York.
World Food India 2025
- World Food India 2025 concluded in New Delhi with investment commitments exceeding one lakh crore rupees, marking one of the largest announcements in India’s food processing sector.
Nation pays homage to revolutionary freedom fighter Bhagat Singh on his 118th birth anniversary today
- The nation pays homage to revolutionary freedom fighter Bhagat Singh on his 118th birth anniversary today. It was on this day in 1907, Bhagat Singh was born in the village of Banga in Lyallpur district of Punjab, now in Pakistan.
National Affairs · 88
Unified District Information System for Education Plus (UDISE+) Report 2024-25
- Computers available: 65% of schools, but only 58% functional.
- Internet access: 63% schools overall. Govt. schools: 58.6% Private schools: 77.1%
- Govt. schools: 58.6%
- Private schools: 77.1%
DBT–BIRAC Launch High-Performance Biomanufacturing Platforms
- 21 bio-enablers supported under BioE3 Policy.
- Policy Base: Part of the BioE3 (Bio-manufacturing to Bio-Economy by 2047) Policy.
- Foster green growth and contribute to a multi-trillion-dollar bioeconomy by 2047.
- Focus on climate alignment, Atmanirbhar Bharat, and Viksit Bharat 2047.
SEMICON India 2025
- Launched in December 2021 with an outlay of ₹76,000 crore, now nearly fully committed.
- At SEMICON India 2025, Prime Minister Narendra Modi unveiled India’s first homegrown semiconductor chip, named ‘Vikram’, marking a landmark step in India’s semiconductor ecosystem.
- Participation in SEMICON India 2025 expected to double compared to the previous edition.
- Aligns with India’s vision of becoming a global semiconductor hub by 2030.
India–US Yudh Abhyas Army Exercise 2025
- Host (2025): United States, conducted in Alaska’s subarctic conditions.
- India: Soldiers from the Madras Regiment.
- United States: 5th Infantry Regiment “Bobcats” of the Arctic Wolves Brigade Combat Team, 11th Airborne Division.
Global Peace Index (GPI) 2025
- Score: 2.229 (improved by 0.58% compared to 2024).
- Coverage: 163 states and territories, representing 99.7% of the world’s population.
- GPI evaluates countries on 23 indicators grouped into 3 domains:
- Most Peaceful Nations: 1st – Iceland (retains top spot). Followed by Ireland, New Zealand, Finland, Austria, Switzerland, Singapore, Portugal, Denmark, Slovenia.
Semiconductor & India’s Vision
- India Semiconductor Mission (ISM): Launched in December 2021 with an outlay of ₹76,000 crore. First semiconductor project cleared within 18 months of Cabinet approval.
- Micron Technology: Setting up a semiconductor assembly & test facility in Gujarat. Partnerships: Vedanta-Foxconn, ISMC, and others in talks. Target: India to become a global hub for semiconductor manufacturing & design by 2030.
- Government Push: Semicon India Programme (2021): $10B incentive scheme for fabs, ATMP (assembly, testing, marking & packaging), and design. India Semiconductor Mission (ISM): Launched in December 2021 with an outlay of ₹76,000 crore. First semiconductor project cleared within 18 months of Cabinet approval.
- Semicon India Programme (2021): $10B incentive scheme for fabs, ATMP (assembly, testing, marking & packaging), and design.
GST 2.0 Reforms
- New Structure (from 22 Sept 2025): 5% (Merit rate) – essential/common goods & services 18% (Standard rate) – general goods & services 40% (Demerit rate) – sin/super luxury goods (tobacco, cigarettes, pan masala, big cars, etc.)
- Previous Structure: 5%, 12%, 18%, 28%
- 5% (Merit rate) – essential/common goods & services
- 18% (Standard rate) – general goods & services
ARTHA Financing Framework
- Full Form: Yet to be officially expanded, but referred to as a green financing framework.
Cabinet Clears ₹1,500 Crore Incentive Scheme for E-Waste & Battery Waste Recycling
- Duration: 6 years (FY 2025-26 to 2030-31).
- Objective: Extract critical minerals from secondary sources like e-waste, lithium-ion battery scrap, catalytic converters from end-of-life vehicles.
- The Union Cabinet has approved a ₹1,500 crore incentive scheme (2025–26 to 2030–31) to promote recycling of e-waste and battery waste, aimed at strengthening India’s critical mineral supply chain under the National Critical Mineral Mission (NCMM). The initiative will serve as a bridge solution until domestic mining and exploration projects yield results, given the long gestation of mining operations.
- Approved by the Union Cabinet in January 2025, the NCMM is a flagship initiative under Atmanirbhar Bharat aimed at making India self-reliant in critical minerals—vital for high-tech manufacturing, clean energy, and defense. Its roots trace back to the Union Budget of 2024–25, when the mission was first announced.
NITI Aayog Report on Path to Atmanirbharta in Millets
- Global Share: India produces ~41% of global millets (~16 MT annually), making it the world’s largest producer.
- Regional Spread: Rajasthan, Maharashtra, Karnataka, Uttar Pradesh, and Madhya Pradesh account for over 80% of production.
- Climate Resilience: Require 70% less water than rice; suitable for drought-prone and arid regions.
- Policy Recognition: Union Budget 2023–24 renamed millets as “Shree Anna”, with funds for research, processing, and market linkages.
India Rankings 2025 by NIRF
- Aim: Promote accountability, transparency, and quality benchmarking among HEIs. Help students, parents, and policymakers with credible performance indicators. Align higher education with NEP 2020 and India’s vision of a knowledge superpower by 2047.
- Participation Growth: 7,692 institutions applied; 14,163 submissions (297% rise since 2016).
- Teaching, Learning & Resources (30%) – faculty quality, student strength, financial resources.
- Research & Professional Practice (30%) – publications, citations, patents.
India’s First Vulture Conservation Portal Launched in Assam
- On September 2, 2025 (International Vulture Awareness Day), India’s first vulture conservation knowledge portal was launched in Assam to boost awareness, data-sharing, and stakeholder collaboration in saving endangered vulture species.
- Launched by: We Foundation India (Assam-based NGO) in collaboration with Gauhati University’s Department of Zoology, supported by Assam Bird Monitoring Network, LASA Foundation, Suraksha Samitee, and independent conservationists.
- India’s vulture diversity: 9 species, of which White-rumped, Indian, and Slender-billed are Critically Endangered.
- Platform to connect researchers, NGOs, citizens, and policymakers.
Angikaar 2025 Campaign
- The Ministry of Housing and Urban Affairs (MoHUA) launched Angikaar 2025, a nationwide outreach campaign under PMAY–Urban 2.0 to accelerate housing delivery and strengthen beneficiary awareness.
- Launched to provide “Housing for All” in urban areas by 2025.
- Aim: To create mass awareness of PMAY-U 2.0. To facilitate verification of applications and expedite completion of sanctioned houses.
- Target: Completion of pending houses and delivery of 1 crore additional houses sanctioned under PMAY-U 2.0.
India’s First Port-Based Green Hydrogen Pilot Project
- Cost: ₹3.87 crore.
- Linked with a proposed Green Methanol Bunkering & Refuelling Facility (₹35.34 crore, 750 m³ capacity).
- Has seen heavy investment (₹16,000+ crore) under the Sagarmala Programme for modernisation.
- Aligned with: Viksit Bharat 2047 and the Sagarmala Programme.
India Joins Health AI Global Regulatory Network (Health AI GRN)
- Established: 2023.
- Headquarters: Geneva, Switzerland.
- On 4 September 2025, the Ministry of Electronics and Information Technology (MeitY) announced that India joined the Health AI Global Regulatory Network (Health AI GRN) to strengthen oversight of Artificial Intelligence (AI) in healthcare. The signing took place in New Delhi.
- What it is? A global platform launched by HealthAI (Global Agency for Responsible AI in Health) to bring together regulators, policymakers, and experts to ensure safe, ethical, and effective use of AI in healthcare.
Bodoland Territorial Region (BTR)
- Headquarters: Kokrajhar, Assam.
- 1993 Accord: Created Bodoland Autonomous Council.
- 2003 Accord: Established Bodoland Territorial Area Districts (BTAD) under Sixth Schedule.
- 2020 Accord: Created Bodoland Territorial Region (BTR) with greater autonomy, economic packages, and recognition of Bodo language.
National Industrial Classification (NIC-2025)
- Industrial classification first introduced in 1962, updated in 1970, 1987, 1998, 2004, and 2008.
- With the rise of OTT platforms, EV charging, AI, and gig work, the existing 2008 codes risk becoming outdated.
- Better representation of gig economy – NITI Aayog estimates gig workforce to grow from 7.7 million (2020-21) to 23.5 million (2029-30).
- Global alignment – NIC-2025 to align with International Standard Industrial Classification (ISIC), improving comparability and investor confidence.
Sample Registration System (SRS) Statistical Report 2023
- India (2023): 18.4 (↓ from 36.9 in 1971, 21.4 in 2013).
- India (2023): 6.4 (↓ from 14.9 in 1971, 7.0 in 2013).
- The Sample Registration System (SRS) Bulletin 2023 (Vol. 58 No.1) by the Office of the Registrar General of India highlights sharp declines in birth rate, death rate, infant mortality, and fertility compared to 1971 levels. While overall trends show progress in maternal-child health, family planning, and healthcare access, disparities persist across rural-urban regions and states.
- Rural: 20.3 | Urban: 14.9.
CoWIN Portal
- Launched: January 2021 (during India’s vaccination drive).
- CoWIN (COVID Vaccine Intelligence Network) is a government digital platform for: Registration Scheduling Tracking Certification of COVID-19 vaccinations.
- Certification of COVID-19 vaccinations.
- Five Modules: Orchestration module (overall management). Vaccination cold-chain module (logistics). Citizen registration module (self & bulk registration). Vaccinator module (session management). Certificate, feedback & adverse-event reporting module.
Two-Factor Authentication (2FA) and TOTP
- TOTP (Time-based OTP): A special form of OTP that changes every 30 seconds.
- Time Counter: Time is divided into 30-second intervals, each with a unique counter value.
- HMAC Function: Inputs: secret key + current time counter. Process: Run through HMAC-SHA-256, a secure cryptographic function.
- Process: Run through HMAC-SHA-256, a secure cryptographic function.
Bhil Tribe
- Launched by the Ministry of Tribal Affairs for translation between Adivasi languages and Hindi/English.
- The largest tribes in India, according to the 2011 Census, are the Bhil tribe, followed by the Gond tribe and the Santhal tribe.
- Culture: Patriarchal yet community-centric, rich oral traditions, folk tales, music, theatre, and worship of local/natural deities.
Vice President of India Election
- Article 64: Vice President is ex-officio Chairperson of the Rajya Sabha; cannot hold any other office of profit.
- Age: Minimum 35 years.
- Tenure: 5 years; continues until successor assumes office.
- Article 63: Establishes the office of the Vice President as the second-highest constitutional authority.
Swachh Vayu Sarvekshan Awards & Wetland Cities Recognition Ceremony 2025
- Launched: 15 August 2020 with target cities.
- Achievements: 103 cities improved PM10 levels. 64 cities achieved 20% reduction in PM10 levels (2017–25). 25 cities achieved 40% reduction by 2025.
- 64 cities achieved 20% reduction in PM10 levels (2017–25).
- 25 cities achieved 40% reduction by 2025.
Exercise Zapad 2025
- History: Zapad (meaning “West” in Russian) exercises have been conducted since the Soviet era, with modern iterations held quadrennially since 2009. India also participated in Zapad 2021.
- An Indian Armed Forces contingent has left for Russia to participate in Zapad 2025, a multilateral military exercise at the Mulino Training Ground, Nizhniy.
U.K.–India Infrastructure Financing Bridge (UKIIFB)
- The U.K.–India Infrastructure Financing Bridge (UKIIFB), launched in September 2024, completed its first year. On its anniversary in London, the initiative released a report recommending policy reforms to de-risk investments in India’s infrastructure sector.
- Launched in September 2024 during the India–UK Economic and Financial Dialogue.
- Address barriers like revenue risks, taxation, and capital repatriation issues.
Adi Sanskriti” Digital Platform
- On 10 September 2025, the Union Ministry of Tribal Affairs launched the beta version of “Adi Sanskriti”, a digital platform designed to preserve, promote, and commercialize tribal artforms and heritage. Officials highlighted that it is envisioned to evolve into the world’s first Digital University dedicated to tribal culture and knowledge.
- Adi Haat – A digital marketplace for tribal artisans, providing direct online access to consumers and helping expand tribal entrepreneurship.
- Digital University Vision: Designed to become a first-of-its-kind Digital University globally. Offers knowledge-sharing, training modules, and certification in tribal arts and crafts.
- Designed to become a first-of-its-kind Digital University globally.
Small Satellite Launch Vehicle (SSLV)
- Specifications: Size: ~2 meters wide, 34 meters tall (≈11-storey building) Engines & Propulsion: First Stage: Solid fuel Second Stage: Solid fuel Third Stage: Solid fuel VTM: Small liquid-fuel engines (MMH + MON-3) with 16 thrusters for precise orbit placement
- Size: ~2 meters wide, 34 meters tall (≈11-storey building)
- Engines & Propulsion: First Stage: Solid fuel Second Stage: Solid fuel Third Stage: Solid fuel VTM: Small liquid-fuel engines (MMH + MON-3) with 16 thrusters for precise orbit placement
- VTM: Small liquid-fuel engines (MMH + MON-3) with 16 thrusters for precise orbit placement
Unicef Report: "Feeding Profit: How Food Environments Are Failing Children"
- Global Trends Overweight vs. Underweight (2000 vs. 2022): 2000: 13% underweight vs. 11% overweight. 2022: 10% underweight vs. 20% overweight. Being overweight has overtaken underweight as the dominant form of malnutrition in children aged 5–19.
- Overweight vs. Underweight (2000 vs. 2022): 2000: 13% underweight vs. 11% overweight. 2022: 10% underweight vs. 20% overweight.
- 2000: 13% underweight vs. 11% overweight.
- 2022: 10% underweight vs. 20% overweight.
Fast Track Immigration – Trusted Traveller Program (FTI–TTP)
- Launched on: 22 June 2024 at Delhi’s IGI Airport.
- Vision Alignment: Part of ‘Viksit Bharat @2047’ mission for world-class infrastructure.
- On 12 September 2025, Union Home Minister Amit Shah launched the FTI–TTP facility at Lucknow, Thiruvananthapuram, Kozhikode, Tiruchirappalli, and Amritsar international airports through videoconferencing.
- Objective: To provide faster, seamless, and secure immigration using biometric authentication at automated e-gates.
New Fungal Species Discovered in the Western Ghats
- Known as “workhorses of biotechnology” due to their versatile applications.
India’s First Overseas Atal Innovation Centre Inaugurated
- The Union Education Minister of India inaugurated India’s first overseas Atal Innovation Centre at the IIT Delhi–Abu Dhabi campus during his UAE visit in September 2025.
- Objective: Promote innovation, research, and entrepreneurship among students and young professionals. Strengthen India–UAE collaboration in education, sustainability, and technology-driven solutions.
- Atal Incubation Centres (AICs): Business incubators at universities and corporates. Provide mentoring, funding, networking, and infrastructure. 72 AICs supporting 3,500+ start-ups, generating 32,000+ jobs.
- Entrepreneurial Ecosystem: Focus on sectors like HealthTech, FinTech, AgriTech, EdTech, Food Processing, Drone & Space Tech, AR/VR. Supported over 1,000 women-led start-ups.
Vultures and Pandemic Preparedness in India
- Species Diversity: India is home to 9 species of vultures, out of which 3 are Critically Endangered: White-rumped Vulture (Gyps bengalensis) Indian Vulture (Gyps indicus) Slender-billed Vulture (Gyps tenuirostris)
- Act as nature’s waste managers by consuming carcasses.
- Role in Ecosystem: Vultures are scavengers — they feed on carcasses of dead animals, preventing the spread of diseases. They are often called “nature’s cleanup crew” for their crucial role in maintaining ecological balance and public health.
- Vultures are scavengers — they feed on carcasses of dead animals, preventing the spread of diseases.
Border Wing Home Guards (BWHG)
- Currently operational only in Rajasthan (2,279 active members).
- Role: Perform constable-level duties; enlistment for 3–4 years.
- Funding: 25% training & support borne by Government of India.
- Ministry of Home Affairs (MHA) is considering raising BWHGs along the China border, similar to their deployment on the India-Pakistan border.
Great Nicobar Island Project
- Compliant with environmental safeguards under EIA Notification 2006 and Shompen Policy 2015 to protect ecology and tribal welfare.
- Phased Development (2025–2047): Spread over three phases to minimise ecological stress and allow adaptive planning.
- International Container Transhipment Terminal (ICTT): Capacity of 14.2 million TEU, reducing reliance on Colombo/Singapore and positioning India as a global shipping hub.
- 450 MVA Gas + Solar Power Plant: Ensures uninterrupted energy supply combining conventional and renewable sources.
India Flags Off ‘Samudra Pradakshina’
- Follows India’s circumnavigation legacy: Capt. Dilip Donde (2009–10) – first solo Indian circumnavigation. Cmde. Abhilash Tomy (2012–13) – first Indian non-stop circumnavigation. INSV Tarini – Navika Sagar Parikrama (2017–18) & (2024–25).
- Capt. Dilip Donde (2009–10) – first solo Indian circumnavigation.
- Cmde. Abhilash Tomy (2012–13) – first Indian non-stop circumnavigation.
- Crew: 10 women officers, led by Lt Col Anuja Varudkar (Army) & Sqn Ldr Shraddha P Raju (IAF).
All India Debt and Investment Survey (AIDIS) & Situation Assessment Survey (SAS) of Agricultural Households
- Objectives: Measure household indebtedness and asset ownership. Inform national accounts and credit policies. Aid RBI, MoSPI, NITI Aayog in financial inclusion and inequality studies.
- Origin: Began as All India Rural Credit Survey (1951-52); expanded in 1961-62 to include urban households and investments.
- Key Features: Decadal survey; last conducted in 77th NSS round (2019). Covers institutional & non-institutional credit sources. Provides disaggregated data by state, sector, income group, and asset class. Supports policymaking for financial literacy, credit penetration, and asset creation.
- Decadal survey; last conducted in 77th NSS round (2019).
PM to Launch ‘Gyan Bharatam’ Portal
- Conference: A three-day event bringing together scholars, conservationists, technologists, and policy experts.
- Objective of Portal: Accelerate digitisation of India’s vast manuscript collections. Ensure preservation of ancient knowledge resources. Provide public access to manuscripts for global knowledge exchange.
- Government Role: The Ministry of Culture is leading the initiative.
Capacity of Dams Halved Due to Sedimentation: IISER Report
- Scope: Examined government records of 300+ large reservoirs with storage capacity exceeding 100 million cubic metres.
- Findings: Several dams have already lost more than half of their designated storage. By 2050, many more—especially in the Himalayan region, Narmada-Tapi basin, Western Ghats, and Indo-Gangetic Plains—will face severe capacity loss.
- By 2050, many more—especially in the Himalayan region, Narmada-Tapi basin, Western Ghats, and Indo-Gangetic Plains—will face severe capacity loss.
PM Launches Gyan Bharatam Portal
- Launched as a digital repository of ancient manuscripts.
- Aims to accelerate digitisation, preservation, and wider access to India’s traditional knowledge systems.
- India holds the world’s largest manuscript collection: nearly one crore manuscripts.
PSB Manthan 2025
- Currently, only State Bank of India (SBI) and HDFC Bank feature in the top 100 global lenders by assets.
- Target: At least two PSBs in top 20 by 2047.
- At the PSB Manthan 2025 conclave (two-day event), the government set a long-term vision to make at least two public sector banks (PSBs) enter the world’s top 20 by 2047, aligning with the Viksit Bharat 2047 roadmap.
- Corporate Governance: Strengthening oversight and autonomy.
2nd National Conference of Anti-Narcotics Task Force (ANTF) Heads
- Key Releases & Launches: NCB Annual Report 2024 (Narcotics Control Bureau). Online Drug Disposal Campaign (digital platform for safe & transparent disposal of seized drugs).
- NCB Annual Report 2024 (Narcotics Control Bureau).
- Union Home Minister Amit Shah will inaugurate the 2nd National Conference of Anti-Narcotics Task Force (ANTF) Heads of States and Union Territories in New Delhi on September 16–17, 2025.
- Participants: ANTF Heads from all 36 States/UTs + representatives from other government departments.
PM Modi Inaugurates India’s First Bamboo-Based Ethanol Plant in Assam
- Hydrolysis: Cellulose and hemicellulose are converted into fermentable sugars using enzymes or acids.
- Fermentation: Microorganisms (like yeast) ferment the sugars into ethanol.
- Can be blended with petrol (E5, E10, or higher) for vehicles.
Purple Fest 2025
- The Indian Sign Language Research and Training Centre (ISLRTC), in collaboration with Amity University, Noida, organized Purple Fest 2025, a national-level festival focused on the empowerment and inclusion of persons with disabilities (Divyangjan).
- Entrepreneurship Stalls: 22 stalls highlighting businesses led by persons with disabilities.
- Objective: Promote inclusion, awareness, and accessibility for persons with disabilities. Empower Divyangjan through entrepreneurship, skill-building, cultural participation, and education. Celebrate creativity and talent while strengthening capacity through Indian Sign Language (ISL)-focused training.
- Promote inclusion, awareness, and accessibility for persons with disabilities.
Centre to Launch ‘Swasth Nari, Sashakt Parivar Abhiyaan’ & 8th Poshan Maah
- Poshan Maah 2025: Part of the ongoing POSHAN Abhiyaan, focusing on nutrition awareness, women’s health, and child development.
- The Central Government will launch the ‘Swasth Nari, Sashakt Parivar Abhiyaan’ (Healthy Woman, Strong Family Campaign) on 17th September 2025, alongside the 8th Poshan Maah (Nutrition Month). The initiative will be inaugurated by Prime Minister Narendra Modi.
- Objective: To strengthen women’s health as a foundation for family well-being and national development.
- Joint Initiative: Led by the Ministry of Health & Family Welfare and the Ministry of Women & Child Development.
Manki-Munda System
- A traditional, decentralized tribal governance system of the Ho community, where Mundas (village heads) and Mankis (pidh heads overseeing clusters of villages) collectively maintain social order and resolve disputes.
- Hereditary Leadership: Positions traditionally pass from father to son.
Exotic Eustoma Blooms in Odisha
- Economic Potential: Two harvests per year; potential income of up to ₹2 lakh per acre per season for farmers.
- Sustainability: Reduces dependence on imported flowers, promotes local floriculture, and supports CSIR-NBRI’s 400+ farmer clusters.
- Growth in India: First successful polyhouse cultivation in Odisha shows adaptability to hot Indian conditions.
- Premium Ornamental Value: Large, funnel-shaped blooms in pink, purple, white, blue, with long vase life (2+ weeks).
Defence Procurement Manual (DPM) 2025
- First update in 16 years, aligning with public procurement norms, technology adoption, and modern warfare requirements.
- The Ministry of Defence (MoD) approved the Defence Procurement Manual (DPM) 2025, replacing the 2009 manual. To accelerate revenue procurement for the Armed Forces and promote Aatmanirbharta (self-reliance) in defence manufacturing. Annual revenue procurement under this manual is worth ~₹1 lakh crore.
Sentient Launches Open-Source AGI Network
- Open AGI Launch: First open AGI network where multiple AI agents collaborate in real time.
- Capabilities: Generates outputs such as comprehensive investment reports, personalised daily briefings, and multi-step workflows.
- Artificial General Intelligence (AGI): Refers to AI systems capable of performing any intellectual task that a human can do, with adaptability, reasoning, and learning across domains. Unlike narrow AI, AGI is not limited to specific tasks.
- Democratization of AI: Allows small organizations, startups, and researchers to access cutting-edge AGI tools without prohibitive costs.
NITI Aayog Launches ‘AI for Viksit Bharat Roadmap’ & Frontier Tech Repository
- Objective: Harness AI to bridge 30–35% of India’s growth gap and achieve sustained 8%+ GDP growth by 2035.
Yudh Abhyas 2025
- Origins & Evolution: Started in 2002, initially focused on platoon-level peacekeeping operations. Has grown into one of the largest and most advanced bilateral exercises conducted by India. Conducted alternately in India and the US.
- Started in 2002, initially focused on platoon-level peacekeeping operations.
- Location & Duration (2025): Fort Wainwright & Yukon Training Area, Alaska, USA Sept 1–14, 2025
- Sept 1–14, 2025
First Time India’s CO2 Emissions Dip
- India added 25.1 GW of clean electricity capacity in H1 2025 (~70% higher than H1 2024).
- Carbon dioxide emissions from India’s electricity sector dropped by 1% in the first half of 2025 compared to H1 2024. First sectoral decline outside Covid years, electricity accounts for ~40% of India’s annual greenhouse gas emissions.
- Weather Factors: Milder summer temperatures reduced electricity demand. Monsoon rainfall was ~30% above normal in pre-monsoon period (March–May). Fewer and less intense heatwaves reduced air-conditioning load (~10% of summer electricity demand).
- Monsoon rainfall was ~30% above normal in pre-monsoon period (March–May).
India to Set Up First Joint Military Stations and Tri-Services Education Corps
- Announced at the three-day Combined Commanders’ Conference (CCC) 2025 in Kolkata.
- Objectives: Increase jointness, rationalise manpower, optimise administration, and foster better integration of personnel.
- Three Joint Military Stations: Announced at the three-day Combined Commanders’ Conference (CCC) 2025 in Kolkata. Will integrate logistics, infrastructure, repair, maintenance, stores, and supplies under a common lead service. Potential locations under discussion: Mumbai, Bengaluru, Ahmedabad, Gwalior, Pune, and Secunderabad. Aim: Optimise manpower, infrastructure, and assets, and test tri-service integration ahead of theatre commands implementation.
- Aim: Optimise manpower, infrastructure, and assets, and test tri-service integration ahead of theatre commands implementation.
Bharat Innovates 2026
- Showcase innovations in biotech, AI & quantum computing, Industry 4.0, smart cities, space, defence, semiconductors, agri-food, medtech, sustainable energy, advanced materials, rare-earth minerals.
- Dates & Venue: June 17–19, 2026, Nice, France.
- Applications: 430+ ventures applied, majority from healthcare, medtech, energy, AI, space & defence. Open until Sept 30, 2025.
- India is launching Bharat Innovates 2026, a flagship initiative to showcase its deeptech innovations and attract global investment, reflecting its intent to position as a reliable partner in an evolving geopolitical landscape.
CAG to Launch AI-Powered LLM and Digital Audit Platform
- First version expected by November 2025.
- Features: Provides 10 lakh audit entities with a unified digital interface. Enables entities to directly respond to audit queries, observations, and inspection reports. Ensures transparency and accountability in the audit process.
- Provides 10 lakh audit entities with a unified digital interface.
- Capabilities: Analyse large datasets efficiently. Generate documents, including inspection reports. Assist auditors in preparing comprehensive, consistent audit reports.
India’s SDG Progress: Health Gaps Remain Despite Improved Ranking
- Aligning reforms with Viksit Bharat 2047 vision requires universal healthcare + preventive education.
- Life Expectancy: 70 years (Target: 73.63 years).
- Out-of-Pocket Expenditure: 13% of total consumption (Target: 7.83%).
- Immunisation Coverage: 93.23% (Target: 100%).
Equalising Primary Food Consumption in India
- Food affordability gap: Nearly 50% of rural India cannot afford 2 thalis/day. About 20% of urban India also fall short.
- Nearly 50% of rural India cannot afford 2 thalis/day.
- About 20% of urban India also fall short.
- Pulses gap: Bottom 5% consume half the pulses of the top 5% → protein deprivation persists.
State of Global Water Resources Report 2024 – WMO
- River Flow: Only 1/3rd of global rivers had water within the normal range in 2024. Nearly 60% of rivers showed too much or too little water for the sixth consecutive year.
- Only 1/3rd of global rivers had water within the normal range in 2024.
- Nearly 60% of rivers showed too much or too little water for the sixth consecutive year.
- Just around a third of rivers across the globe had water within the normal range in 2024 and almost 60 per cent of them either showed too much or too little water for the sixth year running, according to the ‘The Status of Global Water Resources in 2024 Report’ from the World Meteorological Organisation (WMO) released.
India Re-elected to UPU Councils at 28th Congress
- Members: 192 countries, ensuring a universal postal network.
- Founded: 1874 (Treaty of Bern)
- Headquarters: Berne, Switzerland
- India has been re-elected to the Council of Administration and the Postal Operations Council (POC) of the Universal Postal Union (UPU) during the 28th UPU Congress held in Dubai.
| Body | Role |
|---|---|
| Congress | Supreme authority; meets every 4 years; sets strategy & policies |
| Council of Administration (CA) | Policy, regulatory, legal, and administrative issues between Congress sessions |
| Postal Operations Council (POC) | Technical & operational body (48 elected members); drives postal service modernization |
| International Bureau | Secretariat; provides logistical and technical support |
Indian Navy Inducts ‘Androth’ Anti-Submarine Warfare Ship
- Builder: Garden Reach Shipbuilders & Engineers (GRSE), Kolkata.
- Series: Part of an 8-ship series being inducted to enhance India’s coastal and maritime security.
- Role: Coastal security and surveillance Anti-submarine patrols in shallow waters, including Lakshadweep and strategic sea lanes Strengthening maritime border protection
- Anti-submarine patrols in shallow waters, including Lakshadweep and strategic sea lanes
| Feature | Details |
|---|---|
| Length | ~77 metres; among largest Indian naval warships with diesel engine–waterjet propulsion |
| Weapon Systems | Indigenous lightweight torpedoes, anti-submarine rockets |
| Indigenous Content | >80% of components made in India |
| Maneuverability | Optimized for littoral and shallow coastal waters |
| Surveillance | Equipped with advanced sonar and sensors for submarine detection |
INSPIRE Awards 2025
- Objective: Tap 10 lakh original science- and society-based ideas from school children.
- Recognition & Support: Financial assistance of ₹10,000 for model development Ideas first showcased at district level, then progress to state and national levels Top 60 innovations displayed at Rashtrapati Bhavan, with awards conferred by the President of India
- Financial assistance of ₹10,000 for model development
- National Innovation Rankings under INSPIRE Award-MANAK (Million Minds Augmenting National Aspiration and Knowledge) 2025.
| Rank | District | State | Ideas Submitted |
|---|---|---|---|
| 1 | Muzaffarpur | Bihar | 7,403 |
| 2 | Bengaluru Urban | Karnataka | 7,306 |
| 3 | Bagalkot | Karnataka | 6,826 |
| 6 | Jaipur | Rajasthan | 6,311 |
| 6 | Vaishali | Bihar | 6,182 |
| 6 | Lucknow | UP | 6,182 |
| 7 | Hardoi | Uttarakhand | 5,544 |
| 8 | Allahabad | UP | 5,380 |
| 9 | Pratapgarh | UP | 5,380 |
| 10 | Unnao | UP | 5,051 |
Japan’s R&I Upgrades India’s Sovereign Credit Rating to BBB+
- India’s Rating Momentum (2025): S&P Global: Upgraded to BBB from BBB– in August 2025. Morningstar DBRS: Upgraded to BBB from BBB(low) in May 2025. R&I: Third sovereign upgrade in the year, reflecting investor confidence in India’s macroeconomic stability.
- Morningstar DBRS: Upgraded to BBB from BBB(low) in May 2025.
- Global Context: Upgrade comes amid uncertain global economic environment. US tariffs on India (up to 50%) noted as a risk, but limited impact due to low dependence on US exports.
- US tariffs on India (up to 50%) noted as a risk, but limited impact due to low dependence on US exports.
UN Report: Gender Snapshot 2025
- Risk Percentage: Approximately 28% of women’s jobs are estimated to be at risk due to AI and automation, compared to 21% for men.
- Approximately 28% of women’s jobs are estimated to be at risk due to AI and automation, compared to 21% for men.
- Workforce Representation: Women constitute roughly 29% of the global tech workforce, but only about 14% of tech leadership roles.
- Women constitute roughly 29% of the global tech workforce, but only about 14% of tech leadership roles.
Kilnamandi Sarcophagus Redraws Harappan Age Trade Map
- Parallels found between Tamil Nadu graffiti and Indus Valley markings: ~90% similarity
- Graffiti Marks and Cultural Links Potsherds around the sarcophagus carry graffiti symbols: fork-like shapes, semiconcentric circles in U-formation, vertical strokes with wavering lines Parallels found between Tamil Nadu graffiti and Indus Valley markings: ~90% similarity Dating pushes the graffiti tradition in Tamil Nadu back to 17th century BCE
- Dating pushes the graffiti tradition in Tamil Nadu back to 17th century BCE
CAG’s State Finances Publication 2025
- Salary Bills: Increased 2.5 times in 10 years, touching ₹16.6 lakh crore; biggest component of committed expenditure.
- Subsidies: Tripled to ₹3.09 lakh crore. Punjab leads with subsidies at 17% of total expenditure.
- Committed Expenditure: Accounts for 43.5% of revenue expenditure. Highest in Nagaland (74%) and Kerala (63%).
- Public Debt: Jumped 3.4 times to ₹59.6 lakh crore, nearly 23% of combined GSDP, raising medium-term fiscal risk.
Logistics Ease Across Different States (LEADS) 2025
- Corridor Performance Tracking: Monitors 5–7 national corridors using journey time, truck speed, and waiting time.
- Launched by Union Commerce & Industry Minister in New Delhi during the 10-year celebrations of Make in India. Aims to benchmark and enhance the logistics ecosystem across Indian States and Union Territories (UTs).
- Full Form: Logistics Ease Across Different States.
- API-Enabled Data: Real-time section-wise speed evaluation on major road corridors.
Supreme Court Reaffirms Secularism as a Basic Structure of Indian Constitution
- It is a judicial doctrine developed by the Supreme Court in Kesavananda Bharati v. State of Kerala (1973).
- Freedom of Religion: Citizens have the right to practice, profess, and propagate any religion under Articles 25–28 of the Constitution.
- State Neutrality: The state remains neutral in religious matters but can regulate practices to maintain public order, morality, and health.
- The basic structure doctrine, established by the Supreme Court in the Kesavananda Bharati case (1973), states that certain fundamental features of the Constitution cannot be amended or destroyed by Parliament.
World Food India (WFI) 2025
- Union Minister for Food Processing Industries reflects on World Food India (WFI) 2025, highlighting its evolution into a strategic platform aligned with Prime Minister Narendra Modi’s vision of positioning India as a global food basket. WFI serves as a convergence point for government, industry, farmers, FPOs, SHGs, and global investors, enabling innovation to translate into investment and growth.
- Frontiers in Food Processing, Products & Packaging Technologies
- CEO Roundtable: Strategic dialogue among industry leaders, investors, and policymakers to foster collaboration and address sectoral challenges.
- Micro-Entrepreneurs & SHGs: Free stalls enable direct engagement with domestic and global buyers. Trade orders worth crores generated; lasting partnerships established.
CPCB Report 2023
- Polluted River Stretches (PRS): 2023 → 296 PRS across 271 rivers 2022 → 311 PRS across 279 rivers
- 2023 → 296 PRS across 271 rivers
- 2022 → 311 PRS across 279 rivers
- The Central Pollution Control Board (CPCB) released its 2023 assessment of river water quality, focusing on Biological Oxygen Demand (BOD) as a key indicator. Rivers with BOD > 3 mg/litre are deemed unfit for bathing.
National Awards for e-Governance (NAeG) 2025
- Offers 1,027 online services and ensures 100% household digital literacy
- In a historic initiative recognizing grassroots-level digital governance, Gram Panchayats were conferred with the National Awards for e-Governance (NAeG) 2025 under a newly instituted category dedicated to digital service delivery at the Panchayat level.
- First Panchayat in Maharashtra with a fully paperless e-Office system
- 10,000+ citizens access online services annually
| Award | Gram Panchayat | District/State | Sarpanch | Incentive |
|---|---|---|---|---|
| Gold | Rohini | Dhule, Maharashtra | Dr. Anandrao Pawara | ₹10 lakh |
| Silver | West Majlishpur | West Tripura, Tripura | Smt. Anita Deb Das | ₹5 lakh |
| Jury Award | Palsana | Surat, Gujarat | Shri Pravinbhai Parshottambhai Ahir | — |
| Jury Award | Suakati | Kendujhar, Odisha | Smt. Kautuka Naik | — |
Viksit Bharat Buildathon 2025
- Participants: Students from Classes 6 to 12 across six lakh schools.
- Prize Pool: ₹1 crore to be awarded to winning teams.
- The Union Education Ministry has launched the Viksit Bharat Buildathon 2025, inviting school students across India to participate in a large-scale innovation contest.
- Celebrate young innovators and make them key drivers of India’s Viksit, Samriddhi, and Atmanirbhar journey.
NITI Aayog Evaluates Innovation Indicators to Boost India’s GII Ranking
- Performance Snapshot: India improved in 8 GII indicators but worsened in 2 indicators in the short term. Year-on-year rise in GII ranking has been gradual, necessitating focused reforms.
- India improved in 8 GII indicators but worsened in 2 indicators in the short term.
- To identify weaknesses in specific indicators and propose corrective measures for faster improvement in India’s GII ranking.
| Indicator | Rank in 2023 | Rank in 2025 | Observation / Trend |
|---|---|---|---|
| Overall GII Rank | - | 38 | Improved from 81st in 2015 to 38th in 2025 |
| GDP per Unit of Energy | 71 | 76 | Decline in energy productivity |
| Domestic Industry Diversification | 10 | 19 | Reduced industrial diversification |
| Females Employed with Advanced Degrees | - | 101 / 139 | Low representation of women in advanced-degree roles |
Combined Operational Review and Evaluation (CORE) Programme
- Facilitates strategic review, leadership development, and joint problem-solving.
- Focus Areas: Strengthening civil-military synergy Enhancing strategic awareness among future leaders Encouraging holistic decision-making in complex, multidimensional threat scenarios
- Enhancing strategic awareness among future leaders
India’s First AI-Enabled Nature Experience Centre at Betla National Park
- Among the first nine tiger reserves under Project Tiger (1973)
- Notified as a National Park in 1986
- 3D holographic projections to display lifelike animals
- Augmented Reality (AR) and immersive soundscapes (waterfalls, bird calls, predator-prey interactions)
India’s First Overseas Defence Manufacturing Facility in Morocco
- Local sourcing: Initially 1/3 components from Morocco, increasing to 50% in the future
- Size: 20,000 sq. metre state-of-the-art plant
- Significance: First overseas defence manufacturing facility by an Indian private company in Africa
- Strengthen India–Morocco defence partnership
DRDO–SFC Successfully Test-Fire Agni-Prime Missile from Rail-Based Mobile Launcher
- Range: Up to 2,000 km.
- Launch Platform: First-ever test from a rail-based mobile launcher. The launcher is specially designed for rapid deployment, low-visibility operations, and cross-country mobility.
- First-ever test from a rail-based mobile launcher.
- Operational Success: Missile trajectory tracked by multiple ground stations. Test achieved all mission objectives.
India’s Forest Cover Expanded by 2.5% in a Decade
- The Government of India has released its first-ever dedicated publication on forest accounting, highlighting trends in forest cover and condition between 2010-11 and 2021-22. The study, conducted by the Ministry of Statistics and Programme Implementation (MoSPI), follows the UN System of Environmental Economic Accounts (SEEA) Framework (2018).
| Category | 2010-11 / 2001-02 | 2021-22 / 2024 | Change | Remarks |
|---|---|---|---|---|
| Total Forest Area (sq km) | 697,898 | 715,342 | +17,444 (+2.5%) | Net addition over 10 years due to afforestation, reforestation, conservation |
| Very Dense Forests (VDF, >70% canopy) | 83,502 | 102,502 | +19,000 (+22.7%) | Indicates improved forest quality and successful conservation |
| Moderately Dense Forests (MDF, 40–70% canopy) | 318,745 | 307,673 | −11,071 | Decline in medium-density forests |
| Open Forests (OF, 10–40% canopy) | 295,651 | 305,167 | +3.2% | Driven by plantations, natural regeneration, afforestation on degraded lands |
India Successfully Test-Fires Agni-Prime Missile from Rail-Based Launcher
- India successfully conducted its first-ever test of the Agni-Prime intermediate-range ballistic missile from a rail-based mobile launcher on 24 September 2025.
- Replacement Plans: Agni-Prime will gradually replace Agni-I (700 km) and Agni-II (2,000 km) in the SFC arsenal.
- Existing Missile Arsenal: Prithvi-2: 350 km Agni-3: 3,000 km Agni-4: 4,000 km Agni-5: 5,000+ km
- Prithvi-2: 350 km
World Food India (WFI) 2025
- Parallel Events: 3rd Global Food Regulators Summit (FSSAI) 24th India International Seafood Show (SEAI) Reverse Buyer-Seller Meet (APEDA)
- 3rd Global Food Regulators Summit (FSSAI)
- History: 1st edition – 2017; 2nd – 2023; 3rd – 2024; 4th – 2025
- Objective: Strengthen India’s position as the “Food Basket of the World”
Ek Din Ek Ghanta Ek Saath
- Mass Participation: Over 5 crore citizens, including local bodies, NGOs, SHGs, students, and officials.
- Target-Oriented: Focused on 7 lakh Cleanliness Target Units (CTUs) and 3 lakh public areas.
- As part of the Swachhata Hi Seva (SHS) 2025 campaign (17 Sept. – 2 Oct.), Prime Minister Shri Narendra Modi called citizens to participate in Ek Din, Ek Ghanta, Ek Saath, a one-hour nationwide voluntary cleanliness drive at 8:00 AM.
- Led by the Ministry of Housing & Urban Affairs (MoHUA) and the Department of Drinking Water & Sanitation (DDWS), MoJS.
Ministry of Ayush Launches “Prayas” Integrated Neuro-Rehabilitation Centre at AIIA Goa
- The Ministry of Ayush launched “Prayas”, India’s first integrated Neuro-Rehabilitation Centre at the All India Institute of Ayurveda (AIIA), Goa.
- Launch By: Ministry of Ayush
- Objectives: Deliver holistic, patient-centric care. Combine traditional knowledge with modern rehabilitation sciences. Develop evidence-based solutions for neuro care. Act as a research and training hub for Ayush-based innovations. Support families through comprehensive multidisciplinary therapies.
- Act as a research and training hub for Ayush-based innovations.
The Foreign Contribution (Regulation) Act, 2010 (FCRA)
- Historical Context: Initially enacted in 1976 to prevent foreign interference in domestic affairs.
- Exemption for Relatives (2022 Update): Contributions from relatives abroad up to ₹10 lakh need not be notified, penalty applies only for non-intimation.
- The Foreign Contribution (Regulation) Act, 2010 (FCRA) regulates the acceptance and utilisation of foreign donations by individuals and NGOs in India.
- Governing Body: Union Ministry of Home Affairs (MHA).
Sabki Yojana, Sabka Vikas
- The Ministry of Panchayati Raj (MoPR) will launch the People’s Plan Campaign (PPC) “Sabki Yojana, Sabka Vikas” from 2nd October 2025 to kickstart the preparation of Panchayat Development Plans (PDPs) for FY 2026–27.
Cold Desert Biosphere Reserve (CDBR) Gains UNESCO Recognition
- Established under UNESCO’s Man and the Biosphere (MAB) Programme in 1971.
- The inclusion was part of 26 new biosphere reserves across 21 countries, the largest addition in 20 years.
- With this, India now has 13 biosphere reserves listed in the WNBR.
- Decision taken at the 37th session of UNESCO’s International Coordinating Council of the Man and the Biosphere (MAB) in Paris.
Ethambutol Hydrochloride
- Chemical nature: Ethambutol Hydrochloride is a first-line anti-tuberculosis (TB) drug.
- Objective: To check whether imported Ethambutol Hydrochloride is being sold at below-market or unfairly low prices (i.e., dumped) in India.
- Reason: Dumping can hurt domestic manufacturers, threaten local production, and affect drug security for TB treatment.
Ganga River Experiencing Worst Dry Spell in 1,300 Years
- Significance: Supports over 600 million people, contributes ~40% of India’s GDP, crucial for agriculture, industry, and drinking water.
- The Ganga River supports over 600 million people and contributes around 40% of India’s GDP. Recent studies indicate an unprecedented decline in river flow since the 1990s.
- Length: ~2,525 km.
- Basin Area: ~1,08,000 sq km in India; 252,000 sq km including Nepal and Bangladesh.
| Category | Details |
|---|---|
| Methodology | - Streamflow reconstruction using tree -ring data (Monsoon Asia Drought Atlas) and hydrological models. - Validated against historical droughts, famines, and modern observations. |
| Key Findings | - Post-1990s droughts are more frequent and severe than any in the past 1,300 years. - 2004–2010 drought ranks as the worst in over a millennium. - Post-1990s drying ~76% more intense than 16th-century drought. |
| Causes | - Weaker summer monsoons due to Indian Ocean warming and aerosol pollution. - Groundwater depletion, reducing baseflows. - Land-use changes and increased human water consumption. |
| Implications | - Water security threat for 600+ million people in India, Nepal, and Bangladesh. - Agriculture, irrigation, and livelihoods severely affected. - Reveals limitations of current global climate models in predicting regional drying. |
| Recommendations | - Adopt adaptive water management policies considering natural and anthropogenic factors. - Strengthen river basin management and sustainable water-use practices. - Enhance climate and hydrological models for accurate forecasting. |
AstroSat Completes 10 Years
- Date of Launch: September 28, 2015Operator: Indian Space Research Organisation (ISRO)Mission Type: Multi-wavelength space observatoryOrbit: Near-equatorial, low Earth orbitInstruments: UVIT (Ultraviolet Imaging Telescope), LAXPC (Large Area X-ray Proportional Counter), CZTI (Cadmium Zinc Telluride Imager), SXT (Soft X-ray Telescope)Mission Duration: Planned for 5 years; currently operational beyond 10 years
- Launch Details: AstroSat was launched aboard the PSLV-C30 rocket from the Satish Dhawan Space Centre on September 28, 2015.
Digital Competition Law
- Alternative Approach: Adding a new chapter to the existing Competition Act, 2002, but this is less preferred as it acts post-breach and is considered too slow for digital markets.
- Aims to prevent dominance from being established before regulators can intervene.
- India is exploring a standalone Digital Competition Act to regulate Big Tech with upfront rules of conduct, rather than relying solely on the Competition Act, 2002 which acts only after breaches occur.
- Focus Areas: Use of consumer data Treatment of smaller competitors Maintaining fair competition for startups Segments covered: search, social networking, e-commerce, operating systems, cloud services
Ivermectin
- Global malaria deaths in 2023: ~6 lakh, 95% in Africa.
- India has achieved >80% reduction in malaria cases in the past decade, but some districts in Odisha, Chhattisgarh, Jharkhand, and Northeast India still face persistent transmission.
Economy · 1
Small Business Spotlight Report
- Total outstanding credit: ₹15.3 lakh crore (YoY growth 19.3%)
- Active loans: 6.9 crore (YoY growth 8.7%)
- Small business definition: Businesses with aggregate credit exposure ≤ ₹5 crore
| Segment | Contribution / Growth | Key Insight |
|---|---|---|
| Enterprises | Portfolio growth 24.7% YoY | Highest growth in outstanding credit |
| Sole Proprietors with Entity Presence | Borrower count growth 9.3% YoY | Fastest increase in number of borrowers |
| Sole Proprietors | >75% of outstanding credit, >85% of active loans | Dominant segment in terms of volume |
Awards · 1
71st National Film Awards (2023)
- Praised Mohanlal’s versatile contributions to Indian cinema.
- Appreciated encouragement for children’s films; six child actors won awards.
| Category | Winner(s) |
|---|---|
| Best Feature Film | 12th Fail (Hindi) |
| Best Male Actor (tie) | Shah Rukh Khan (Jawan), Vikrant Massey (12th Fail) |
| Best Female Actor | Rani Mukerji (Mrs. Chatterjee vs Norway) |
| Best Director | Sudipto Sen (The Kerala Story – Hindi) |
| Best Popular Film Providing Wholesome Entertainment | Rocky Aur Rani Kii Prem Kahaani (Hindi, Karan Johar) |
| Best Feature Film Promoting National/Social/Environmental Values | Sam Bahadur (Hindi, Meghna Gulzar) |
| Best Children’s Film | Naal 2 (Marathi) |
| Best Animation/VFX/Gaming/Comic Film | Hanu-Man (Telugu) |
Swipe for all 5 courses →
You are writing NABARD Grade A in 2026 NABARD Grade A 2026 Mentorship & Test Series
The whole thing — ARD, ESI, descriptive, mocks, mentors.
544 lessons 18 free to try
₹3,500
₹6,000 42% off
Enrol now
Try 18 lessons free
You are targeting RBI Grade B RBI Grade B Mentorship 2026
Phase 1 and Phase 2 together, with descriptive marked by hand.
576 lessons 41 free to try
₹2,999
₹6,000 50% off
Enrol now
Try 41 lessons free
You have studied — you need practice NABARD Test Series Phase I 2026
Phase I test series only. No lectures, just papers and analysis.
48 lessons 2 free to try
₹1,499
₹2,500 40% off
Enrol now
Try 2 lessons free
Your descriptive paper is the weak one NABARD English Descriptive 2026
Essay and précis, written and rewritten until it scores.
18 lessons
₹1,499
₹3,000 50% off
Enrol now
You are starting early for 2027 NABARD Foundation & Advanced Programme 2027
Foundation first, advanced later. A year, planned.
18 lessons 2 free to try
₹3,999
₹6,999 43% off
Enrol now
Try 2 lessons free
Clarity 4 Sure · c4scourses.in · +91 87086 52887 · compiled 25 September 2026