Clarity 4 Sure · Revision Sheet
October 2025 — exam-ready facts
511 items from 25 days · NABARD Grade A · RBI Grade B · SEBI Grade A
Names, numbers and tables only — the narrative is stripped out. Prints two columns to a page. For the full write-up of any item, open the full version.
Want this month’s PDF on WhatsApp?
Tap below — WhatsApp opens with the message already written. Just press Send and the link arrives straight away.
Get the October 2025 revision sheet on WhatsApp25days covered
511topics
21topics a day
9hto revise once
1
Cover the right column
Read only the topic name and try to recall the facts before you look.
2
Mark what you missed
Anything you could not recall is what the exam will find first.
3
Write one answer
Pick one topic and write 150 words on it. That is what converts marks.
50%Risks: Weak global demand, US tariffs on India (50%), and excess rains impacting agriculture…
13%Around 13% of India’s land area (0.42 million sq. km) is landslide-prone, per the Geological…
5 lakh5 lakh pumps targeted by 2022-23.
₹1.5 lakhCelestia: For high-value customers, benefits up to ₹1.5 lakh.
$1.7 billionIndia remains a reliable partner in Mongolia’s development; $1.7 billion line of credit for…
US$ 8 billionOnly US$ 8 billion was invested globally in 2023 (91% public, 9% private).
55%Significant Reduction: Multidimensional poverty dropped from 55% (2005–06) to 16.4% (2019–21…
₹10PARAM JAL Model: Treats multi-level mine water and dispenses 10 litres for ₹10 via coins or…
70%First Instalment: 70% on approval of the annual budget.
₹11,440 croreMission Duration & Funding: Six years (2025–26 to 2030–31) Outlay: ₹11,440 crore Target: 45%…
0.3%Rate Structure: The current rates range from 0.3% to 4.3% of the export value, depending on…
18%FPIs hold ~16–18% of Indian market capitalization, making their flows crucial for market sen…
Pulled straight out of this month's own facts. If a figure here is new to you, go back and read that item in full.
National Affairs · 111
India’s Industrial Growth Slows to 4% in August 2025
- Risks: Weak global demand, US tariffs on India (50%), and excess rains impacting agriculture.
- India’s industrial output, measured by the Index of Industrial Production (IIP), grew 4% in August 2025, easing slightly from July’s upwardly revised 4.3% growth. The slowdown was led by weaker manufacturing activity, despite a recovery in mining and electricity.
- GST Council’s sharp tax rate cuts on autos, textiles, packaged foods, kitchenware, and services (life & health insurance, restaurants) announced in Sept 2025 as a “GST savings festival” are expected to stimulate demand.
| Category | July 2025 | August 2025 | Remarks |
|---|---|---|---|
| Overall IIP Growth | 4.3% (revised from 3.5%) | 4% | Slight slowdown, but rebound from Jan–Jun weakness |
| Manufacturing | 5.38% | 3.8% | Slowed due to postponed purchases before Sept GST cuts |
| Mining | Contracted (monsoon impact) | 6% | Strong recovery |
| Electricity | Negative (May–June contraction) | 4.15% | Continued recovery |
| Capital Goods | 6.8% | 4.4% | Moderation in investment activity |
| Infrastructure/Construction Goods | 13.7% | 10.6% | Still robust despite slowdown |
| Consumer Durables | 7.2% | 3.5% | GST wait-and-watch sentiment hit demand |
| Consumer Non-durables | Negative trend | -6.3% | Continued contraction since start of FY25 |
India Adds Two New Ramsar Sites in Bihar
- Rich in biodiversity: 280+ plant species, including endemic Alysicarpus roxburghianus.
- Total Sites: 93 (covering 13.6 lakh hectares).
- Wetlands of international importance under the Ramsar Convention (1971).
- Origin: Signed in Ramsar, Iran (1971); came into force in 1975 under UNESCO.
Sahyog Portal
- The Sahyog portal is an online platform created by India’s Ministry of Home Affairs (MHA), maintained via the Indian Cyber Crime Coordination Centre (I4C).
- It was launched in October 2024 to automate and streamline the issuance of content takedown notices by government agencies, police, and other authorized bodies under Section 79(3)(b) of the Information Technology (IT) Act, 2000.
- The portal covers multiple agencies—central, state, police, ministries—and many intermediaries (e.g. Google, YouTube, Apple) have been onboarded.
- IT intermediaries receive notices and are required to act—either remove content or respond with reasons or request further evidence.
NCRB Crime in India Report 2023
- Established: 1986 (based on Tandon Committee, National Police Commission 1977-81, and MHA Task Force 1985).
- Overall Crime: Total: 6.24 million cases (↑7.2%). Crime rate: 448.3 per lakh population (vs. 422.2 in 2022). A crime every 5 seconds in India.
- Crime rate: 448.3 per lakh population (vs. 422.2 in 2022).
- Cybercrime: ↑ 31.2% in 2023. Majority linked to fraud (68.9%), followed by sexual exploitation and extortion. Reflects risks of rapid digitalization without adequate cyber hygiene.
India–EFTA Trade and Economic Partnership Agreement (TEPA)
- Signed on: 10th March 2024 in New Delhi
- 10th March 2024 in New Delhi
- The India–European Free Trade Association (EFTA) Trade and Economic Partnership Agreement (TEPA) came into effect on 1st October 2025. It is India’s first FTA with four developed European countries, promising $100 billion investments and 1 million jobs in the next 15 years.
- What it is? A comprehensive Free Trade Agreement (FTA) between India and the European Free Trade Association (EFTA). First Indian FTA linking trade, investment, and job creation.
| Key Area | Provisions / Highlights |
|---|---|
| 1. Investment & Employment | • $100 billion FDI commitment over 15 years • 1 million direct jobs in manufacturing & services |
| 2. Market Access for Goods | • EFTA offers zero-duty access on 92.2% tariff lines • Covers 99.6% of India’s exports |
| 3. Services & Mobility | • Commitments in 100+ sub-sectors (IT, education, audiovisual, business services) • Mutual Recognition Agreements (MRAs) in nursing, architecture, chartered accountancy • Facilitates: Mode 1 (Digital delivery), Mode 3 (Commercial presence), Mode 4 (Personnel mobility) |
| 4. Intellectual Property Rights (IPR) | • TRIPS+ standard with safeguards for generic medicines • Prevents patent evergreening while protecting innovation |
| 5. Sustainable Development | • Focus on green growth, social inclusion, and environmental protection • Encourages technology collaboration in renewable energy, precision engineering, and health sciences |
Dugong Conservation in India
- First Dugong Reserve of India: Declared in September 2022 under the Wildlife Protection Act, 1972.
- The International Union for Conservation of Nature (IUCN) has recognised Tamil Nadu’s Dugong Conservation Reserve in Palk Bay as a global model for marine biodiversity conservation during the IUCN World Conservation Congress 2025.
- IUCN Recognition: Motion proposed by Omcar Foundation, supported by 98% of countries/agencies and 94.8% NGOs/research bodies.
- Ecological Role: Seagrass meadows provide feeding grounds, support biodiversity, and act as carbon sinks.
Female Labour Force Participation in India
- The Female Labour Force Participation Rate (FLFPR) measures the share of women who are employed or actively seeking work. While India’s FLFPR fell from 31.2% in 2011-12 to 23.3% in 2017-18, it rose sharply to 41.7% in 2023-24, driven mainly by rural women.
- Female Labour Force Participation Rate (FLFPR) is the proportion of women (aged 15 years and above) who are either employed (working) or actively seeking employment.
| Dimension | Key Findings (2017-18 / 2018-19 vs 2023-24) |
|---|---|
| Earnings vs Participation | • Female Labour Force Participation Rate (FLFPR) rose, but real earnings declined for most women (except casual workers). • Increased participation ≠ better-paid or secure jobs. |
| Sectoral Composition | • Share of rural women in agriculture increased: 71.1% (2018-19) → 76.9% (2023-24). • Decline in women’s employment in secondary (industry) and tertiary (services) sectors. |
| Shift from Domestic Duties | • Women reporting domestic duties fell: 57.8% (2017-18) → 35.7% (2023-24). • Helpers in household enterprises: 9.1% → 19.6%. • Own account workers/employers: 4.5% → 14.6%. • Indicates shift mainly to self-employment, not wage employment. |
| Vulnerabilities | • Helpers in household enterprises often unpaid/low-paid, blurring line between employment & domestic labour. • Even among self-employed women, real earnings declined, showing persistent income insecurity. |
Beti Bachao, Beti Padhao Completes a Decade
- Awareness impact: Surveys (e.g., Madhya Pradesh) show 89.5% people aware of BBBP, with 63.2% motivated to send daughters to school.
- The Beti Bachao, Beti Padhao (BBBP) scheme, launched in 2015, has completed 10 years, registering progress in sex ratio at birth and girls’ education outcomes across India. The initiative has been implemented as a convergence of Women & Child Development (WCD), Health, and HRD Ministries.
- Launch: 22 January 2015 by the Government of India at Panipat, Haryana.
- Sex Ratio at Birth (SRB): Improved from 919 (2015–16) to 929 (2019–21).
ANRF launches SARAL Tool to Simplify Scientific Research
- Full Form: Simplified and Automated Research Amplification and Learning.
- Purpose: To make scientific knowledge inclusive and accessible for citizens, policymakers, academia, and industry.
- AI-driven Summaries: Extracts key insights from research papers and converts them into simplified versions.
- Multi-Format Outreach: Generates videos, podcasts, posters, and presentations to increase reach.
Cyclone Shakthi
- Emerged from a low-pressure area formed over the warm Arabian Sea waters in early October 2025.
- The India Meteorological Department (IMD) has officially confirmed the formation of Cyclone Shakthi over the northeast Arabian Sea, marking one of the early post-monsoon cyclonic events of 2025.
- A tropical cyclonic storm that developed in the northeast Arabian Sea, around 340 km west of Dwarka, Gujarat.
- Intensified into a Cyclonic Storm (CS) on October 3, and is forecast to strengthen into a Severe Cyclonic Storm (SCS) as it moves west-southwestwards.
| Factor | Bay of Bengal | Arabian Sea |
|---|---|---|
| Sea Surface Temperature | Warmer (29–30°C) throughout the year | Cooler due to strong winds and high evaporation |
| Moisture Availability | High moisture from river inflows and monsoon winds | Dry winds from Oman and Yemen reduce moisture |
| External Atmospheric Triggers | Frequently receives remnants of Pacific typhoons that re-intensify | Rarely influenced by external low-pressure systems, leading to fewer cyclones |
Snow Leopards
- Indian Wildlife (Protection) Act, 1972: Listed in Schedule I, offering the highest level of protection.
- Project Snow Leopard (2009): A central government initiative promoting landscape-level conservation across five Himalayan states.
- SECURE Himalaya Project: Jointly implemented by the Government of India and UNDP, focusing on sustainable livelihoods and biodiversity conservation in snow leopard habitats.
- Jointly implemented by the Government of India and UNDP, focusing on sustainable livelihoods and biodiversity conservation in snow leopard habitats.
India–UK Conduct Bilateral Naval Exercise KONKAN-2025
- Harbour Phase (5–8 October): Includes professional interactions, cross-deck visits, sports fixtures, and cultural exchanges. Joint Working Group meetings and Subject Matter Expert (SME) exchanges to strengthen operational understanding.
- Duration & Phases: Conducted in two phases (5–12 October 2025) — Harbour Phase and Sea Phase.
- Conducted in two phases (5–12 October 2025) — Harbour Phase and Sea Phase.
- Sea Phase (9–12 October): Involves complex maritime operations, including: Anti-Air, Anti-Surface, and Anti-Submarine Warfare drills. Flying operations and seamanship evolutions. Focus on interoperability and joint mission capability across domains.
Landslides in India
- Around 13% of India’s land area (0.42 million sq. km) is landslide-prone, per the Geological Survey of India (GSI).
- The Northeast alone accounts for 42% of the total hazard zone due to: Steep gradients, fragile geology, and intense monsoon rainfall. Unregulated construction and deforestation.
| Aspect | Details |
|---|---|
| Geographical Factors | • Located in the Eastern Himalayas, composed of young, unconsolidated rocks highly prone to erosion. • Intense monsoon rains cause waterlogging and weaken soil cohesion. • Unscientific infrastructure projects (road cutting, tunneling for hydropower, etc.) disturb natural drainage systems. • The region is seismically active, increasing the risk of slope failure and landslides. |
| Policy Implications | • The crisis calls for a pan-Himalayan sustainable development policy that integrates land-use planning, ecological zoning, and climate adaptation. • Focus on geo-hazard mapping, early warning systems, and green infrastructure for long-term resilience. |
Unified National Employment Framework
- Demographic Advantage: India is expected to add 133 million workers by 2050, forming 18% of the global workforce. The demographic window will peak by 2043, demanding urgent job creation strategies.
- India is expected to add 133 million workers by 2050, forming 18% of the global workforce.
- Rise of Informal and Gig Sectors: Gig economy jobs projected to reach 9 crore by 2030, but most lack social security and formal benefits.
- Gig economy jobs projected to reach 9 crore by 2030, but most lack social security and formal benefits.
IUCN World Conservation Congress 2025
- Previous Edition: Held in Marseille, France (2021), focusing on post-pandemic recovery and climate resilience.
- The first IUCN Congress was convened in 1948, the same year IUCN was established.
- India has been an IUCN State Member since 1969 and has consistently contributed to global biodiversity and conservation dialogues.
- Objective: To determine global priorities for biodiversity protection, climate action, and sustainable development.
Arunachal Pradesh Launches First Commercial Coal Mine at Namchik-Namphuk
- Origin: Introduced under the Coal Mines (Special Provisions) Act, 2015. Operationalised in 2020 as part of the AatmaNirbhar Bharat reforms.
- Introduced under the Coal Mines (Special Provisions) Act, 2015.
- Reserves: Estimated 1.5 crore tonnes of coal reserves, enabling long-term production.
- Operationalised in 2020 as part of the AatmaNirbhar Bharat reforms.
NCRB Data on Crimes Against Children 2023
- Overall crimes against children in India rose by 25% in 2023 compared to the 2018–2022 average.
- However, Assam, Rajasthan, and Kerala saw exceptional increases ranging from 70% to over 100%, each driven by different underlying factors.
- The National Crime Records Bureau (NCRB) data for 2023 revealed that crimes against children recorded the sharpest increase in Assam, Rajasthan, and Kerala, even as the national average rose by 25%. These trends reflect both policy-driven interventions and improvements in classification and reporting of offences against minors.
| State | Increase & Key Drivers (2023) | Interpretation |
|---|---|---|
| Assam | Cases nearly doubled (~5,100 → 10,000). Surge driven by strict enforcement of the Prohibition of Child Marriage Act, 2006; child marriage cases rose from ~150/year to 5,267. | Reflects state-led crackdown, not necessarily higher incidence. |
| Rajasthan | Cases up ~70% (~6,200 → 10,500). Driven by reclassification of offences (Section 376 IPC → POCSO provisions) and rise in child kidnapping/abduction. | Rise reflects both better categorisation and a genuine increase in child-related crimes. |
| Kerala | Cases up ~106% (~2,800 → 5,900+). Surge linked to POCSO cases and improved reporting. | Indicates enhanced law enforcement responsiveness and greater social awareness of child protection laws. |
Indian Navy Commissions INS Androth
- Length: 77 meters | Weight: ~1,500 tonnes
- Built with over 80% indigenous content by Garden Reach Shipbuilders and Engineers (GRSE).
- Designed for anti-submarine operations in coastal and shallow waters.
- Equipped with advanced weapons, sensors, and communication systems.
PM Modi to Inaugurate India Mobile Congress (IMC) 2025
- Cybersecurity for 1.2 billion telecom users
- International Bharat 6G Symposium – Showcasing India’s 6G leadership.
- IMC Aspire Programme – Networking for 500 startups with 300 investors.
- Prime Minister Shri Narendra Modi to inaugurate Asia’s Premier Telecom & Tech Event IMC 2025
People’s Plan Campaign (PPC) 2025–26
- The planning process is participatory, transparent, and inclusive, involving Gram Sabhas, frontline workers, Self-Help Groups (SHGs), and community organizations.
- Plans align with the 29 subjects in the Eleventh Schedule of the Constitution and are linked to Sustainable Development Goals (SDGs).
- Promote gender-responsive governance through active involvement of Women Elected Representatives (WERs) and women community members.
- The People’s Plan Campaign (PPC) is an annual initiative launched by the Ministry of Panchayati Raj to strengthen participatory, transparent, and accountable local governance. It seeks to ensure comprehensive planning and effective delivery of development schemes at the Gram Panchayat, Block Panchayat, and District Panchayat levels. The 2025–26 edition was formally launched on 2nd October 2025 across all States and Union Territories under the theme: “Sabki Yojana, Sabka Vikas”.
PM-SETU (Prime Minister’s Scheme for Empowerment through Technology Upgradation)
- Total Outlay: ₹60,000 crore (shared by Centre and States)
- Full Form: Prime Minister’s Scheme for Empowerment through Technology Upgradation (PM-SETU)
- Nodal Ministry: Ministry of Skill Development and Entrepreneurship (MSDE)
- Project Duration: 2025–2028
Indian Radio Software Architecture (IRSA) Standard 1.0 Launched
- IRSA 1.0 is India’s first national software architecture standard for Software Defined Radios (SDRs) used by the Indian Armed Forces.
- Scalability: Designed to integrate advanced technologies like AI, 5G, and cognitive radio systems for next-generation warfare.
- Designed to integrate advanced technologies like AI, 5G, and cognitive radio systems for next-generation warfare.
Draft National Labour and Employment Policy, 2025
- Based on the 3Ps Framework: Protection, Productivity, and Participation.
- Strives to balance workers’ welfare with enterprise growth and sustainable livelihoods.
- Promotion of green and decent jobs and just transition pathways for affected workers.
- The Union Ministry of Labour and Employment released the draft National Labour and Employment Policy (NLEP) titled Shram Shakti Niti, 2025 for public consultation on October 8, 2025. The policy envisions a fair, inclusive, and future-ready world of work, aligned with India’s aspiration to become a developed nation by 2047.
PM-KUSUM (Pradhan Mantri Kisan Urja Suraksha evam Utthan Mahabhiyan)
- Launch: 2019 (by Ministry of New & Renewable Energy, Government of India)Aim: Promote solar energy adoption in the agriculture sector, ensure energy security for farmers, and provide additional income through renewable energy.
- Component A – Solarization of Grid-Connected Agriculture Pumps: 17.5 lakh pumps targeted by 2022-23. Farmers get subsidy of up to 60–90% of pump cost (depending on landholding).
- 17.5 lakh pumps targeted by 2022-23.
- Farmers get subsidy of up to 60–90% of pump cost (depending on landholding).
NITI Aayog Report: Roadmap on AI for Inclusive Societal Development
- Massive Workforce Base: ~490 million Indians (~90% of workforce) engaged in informal work, contributing ~50% of GDP (MoLE, 2024).
- Rising Urban Informality: ~7.5 million gig/platform workers without labour protection (NITI Aayog, 2022).
- Rural Dominance: 80%+ rural workers lack formal contracts or social security; concentrated in agriculture, construction, retail, handicrafts.
- Gendered Informality: Women constitute >55% of informal workforce, especially in home-based work and agriculture.
India Launches National Red List Assessment for Flora and Fauna
- Objective: To assess the conservation status of India’s flora and fauna and fulfil obligations under the Convention on Biological Diversity and the Kunming-Montreal Global Biodiversity Framework.
- Framework: India’s Vision 2025-2030 prepared by Zoological Survey of India (ZSI) and Botanical Survey of India (BSI) in collaboration with IUCN-India and the Centre for Species Survival.
- Outcome: Publication of National Red Data Books for both flora and fauna by 2030 using IUCN-aligned scientific guidelines.
- India has initiated a landmark National Red List Assessment of Indian Flora and Fauna, aimed at evaluating the extinction risk of nearly 11,000 species of plants and animals by 2030. This first-of-its-kind national exercise will provide a comprehensive picture of species vulnerability and guide evidence-based conservation planning.
India to Host 8th International Solar Alliance (ISA) Assembly
- 124 members & signatory countries (2025)
- Launch: 2015, during COP21 Climate Summit, Paris
- India will host the 8th ISA Assembly from October 27–30, 2025, at Bharat Mandapam, New Delhi. The event will bring together governments, industry players, and financial institutions to accelerate global solar energy deployment.
- Headquarters: Gurugram, India (first international organisation headquartered in India)
AMRAAM Missile
- Developer: U.S. Air Force & Raytheon (1980s)
- Range: Up to 160 km (C8/D3 variants)
- Speed: Up to Mach 4
- Platforms: F-15, F-16, F-35, Eurofighter Typhoon, Gripen, etc.
Gharial Classified as “Critically Depleted” in IUCN’s First Green Status Report
- Population: About 681 adults remain in the wild, with 80% in the Chambal River (UP, MP, Rajasthan).
- About 681 adults remain in the wild, with 80% in the Chambal River (UP, MP, Rajasthan).
- Assessment: First-ever IUCN Green Status assessment.
India Upgrades Kabul Mission to Embassy Status
- India closed its Kabul Embassy in August 2021 after the U.S.-led withdrawal and Taliban’s takeover.
- A technical mission was established later to oversee humanitarian and consular work.
- Objective: To strengthen cooperation in Afghanistan’s national development, regional stability, and counterterrorism efforts.
India–U.K. Bilateral Maritime Exercise KONKAN 2025
- Objective: To enhance coordination and cooperation in complex maritime operations and strengthen the long-standing naval partnership between India and the U.K.
- The Indian Navy and the Royal Navy of the United Kingdom commenced the bilateral maritime Exercise KONKAN 25 on 5 October 2025 off the western coast of India. Over the past two decades, this exercise has evolved in scale and complexity, enhancing interoperability and mutual understanding between the two navies.
- Exercise Name: KONKAN 25
Demographic Mission 2025
- In his Independence Day 2025 address, Prime Minister Narendra Modi announced the launch of a high-powered Demographic Mission, aimed at countering illegal infiltration and addressing India’s emerging demographic challenges.
- Cross-Sector Integration: Coordination between ministries handling home affairs, labour, health, and rural development.
CCRAS Launches SPARK–4.0
- Aim: Cultivate scientific curiosity among young Ayurveda scholars. Develop a research mindset while bridging classical Ayurvedic knowledge with modern scientific methods.
- Studentships: 300 BAMS students to receive ₹50,000 each (₹25,000 per month for 2 months).
- The Central Council for Research in Ayurvedic Sciences (CCRAS), under the Ministry of Ayush, has launched SPARK–4.0 (2025–26), the fourth edition of its flagship program aimed at encouraging research orientation among BAMS undergraduates.
- Full Form: Studentship Program for Ayurveda Research Ken
Global Fintech Fest 2025 (GFF 2025)
- Premium Credit Cards: Celestia: For high-value customers, benefits up to ₹1.5 lakh. Lakshmi Card: Women-focused premium card.
- Celestia: For high-value customers, benefits up to ₹1.5 lakh.
- What: 6th edition of Global Fintech Fest (GFF 2025)
- When: October 7–9, 2025
Iron Age Culture Near Western Ghats in Tamil Nadu
- Unearthed artefacts include: A rectangular stone slab chamber with urn burials, a first-of-its-kind discovery in Tamil Nadu. The chamber was made of 35 stone slabs and filled with cobblestones up to a depth of 1.5 metres.
- The site is located about 10 km northwest of Thirumalapuram village, between two seasonal streams originating from the Western Ghats near the Kulasegarapereri tank.
- Conducted by TNSDA archaeologists during the first season beginning last year.
- A total of 37 trenches were excavated across a 35-acre burial site.
IUCN Recognises Indian Wolf as a Potential Distinct Species
- Estimated Population: Around 3,093 (range: 2,877–3,310) individuals across India and Pakistan.
- Primary Threats: Habitat loss and fragmentation Human persecution and retaliatory killings Conflict in agrarian and pastoral landscapes
- Human persecution and retaliatory killings
Shift to Non-Communicable Diseases (NCDs) in India: GBD 2023 Report
- 1990: Diarrhoeal diseases were the leading cause of death (ASMR: 300.53 per lakh).
- 2023: NCDs dominate: Ischaemic heart disease – ASMR 127.82 per lakh (1st) Chronic obstructive pulmonary disease (COPD) – ASMR 99.25 per lakh (2nd) Stroke – ASMR 92.88 per lakh (3rd)
- All-cause ASMR: Dropped from 1,513.05 per lakh in 1990 to 871.09 per lakh in 2023, showing improvement in overall mortality.
- Life Expectancy Trends (1990–2023): Overall: 58.46 → 71.56 years (+13 years) Males: 58.12 → 70.24 years Females: 58.91 → 72.96 years Despite NCD prevalence, life expectancy has significantly increased.
India’s Retail Inflation Falls to 8-Year Low of 1.54% in September 2025
- Retail inflation (CPI-based): Fell to 1.54% in September 2025, the lowest in over eight years.
- Comparison: June 2017: 1.46% (last time inflation was lower) August 2025: 2.1% July 2025: Below 2%
- June 2017: 1.46% (last time inflation was lower)
- August 2025: 2.1%
India’s Civil Registration System (CRS) Report 2023
- There was no major spike in death registration during 2022–2023, despite the Ministry of Health’s COVID-19 dashboard reporting 5.33 lakh pandemic-related deaths as of May 2025.
- The Registrar-General of India (RGI) released the Vital Statistics of India based on the Civil Registration System (CRS) 2023 report, which provides official data on births, deaths, and sex ratio at birth across the country.
- India registered 2.52 crore births in 2023, which is 2.32 lakh fewer than the 2.54 crore births recorded in 2022.
- Institutional births accounted for 74.7% of total registered births in 2023.
Dr. Sonali Ghosh Wins IUCN WCPA Kenton Miller Award 2025
- Established: 1999, by IUCN World Commission on Protected Areas (WCPA)
- Award: IUCN Kenton Miller Award 2025
- Significance: First Indian to receive this prestigious international award
- Announced at: IUCN World Conservation Congress, Abu Dhabi, October 2025
IUCN World Heritage Outlook 4 Launched
- Policy integration: Wildlife (Protection) Amendment Act, 2022, and LiFE Mission support global biodiversity goals (KM-GBF 2030).
- About 65% of sites show stable or improving conservation outlooks. Examples: Galápagos Islands, Yellowstone National Park.
- Climate threats affect over 80% of natural sites (coral bleaching, glacier melt, wildfires). Example: Great Barrier Reef.
- Biodiversity pressures like invasive species and habitat loss impact around 60% of sites. Example: Hawaiian Volcanoes National Park.
PM Surya Ghar Yojana (PMSGY)
- The scheme aims to achieve 1 crore rooftop solar connections by FY2027, providing capital subsidies and low-cost loans to households.
- Delayed approvals: Processing time between 45–120 days, mainly due to: Shortage of net meters. Poor coordination among consumers, installers, and DISCOMs. Utility-level procedural inefficiencies.
- High cost of DCR-compliant modules: Indian-made modules cost ₹12/watt more than imported ones, making large installations less economically attractive.
- Indian-made modules cost ₹12/watt more than imported ones, making large installations less economically attractive.
Government Launches Fixed-Fare Scheme for Alliance Air to Boost Regional Air Connectivity
- It aims to bring pricing transparency and affordability, especially for passengers from Tier-2 and Tier-3 cities.
- Scheme Name: “Fare Se Fursat”
- Duration: October 13 – December 31, 2025
- Objective: To test the operational feasibility and passenger response to fixed ticket pricing on select routes.
PM Gati-Shakti Portal
- The web-based platform offers regulated access to selected datasets from the PM GatiShakti National Master Plan (NMP).
- Data Coverage: – Provides access to 230 approved datasets covering:- Physical infrastructure: Highways, railways, airports, ports, warehouses, multimodal logistics parks, and telecom towers.- Social infrastructure: Schools, healthcare facilities, water bodies, and forest areas.– Also includes track length details, district layers, freight corridors, and land records for better project planning.
- – Provides access to 230 approved datasets covering:- Physical infrastructure: Highways, railways, airports, ports, warehouses, multimodal logistics parks, and telecom towers.- Social infrastructure: Schools, healthcare facilities, water bodies, and forest areas.– Also includes track length details, district layers, freight corridors, and land records for better project planning.
GalaxEye to Launch India’s Largest Private EO Satellite – Mission Drishti
- GalaxEye, an Indian space-tech startup, announced the launch of ‘Mission Drishti’, the world’s first multi-sensor Earth observation (EO) satellite, in Q1 2026. The satellite weighs 160 kg and is India’s largest privately built satellite. It is also the highest-resolution EO satellite developed in the country.
India Hosts First Chiefs’ Conclave of UN Troop Contributing Countries (UNTCC)
- India hosted the Conclave of Chiefs of UN Troop Contributing Countries (UNTCC) for the first time, in New Delhi from October 14-16, 2025, under the aegis of the Indian Army.
- Over 30 military chiefs and senior officials from 32 nations, including key troop-contributing countries: Bangladesh Ethiopia Nepal Kenya
- Purpose of the Forum: Provide a platform to deliberate operational challenges, share best practices, and develop a common understanding of the future of peacekeeping. Focus on interoperability, technology adoption, and capacity building.
- Provide a platform to deliberate operational challenges, share best practices, and develop a common understanding of the future of peacekeeping.
PM Modi Strengthens India–Mongolia Strategic Partnership
- Symbolic milestone: Joint release of commemorative stamps marking 70 years of India-Mongolia relations.
- Sponsorship of annual visits of young Mongolian cultural ambassadors to India.
- Strengthening historic Buddhist ties: linking Nalanda University with Gandan Monastery; continued promotion of Buddhist heritage.
- India remains a reliable partner in Mongolia’s development; $1.7 billion line of credit for Oil Refinery Project to boost energy security.
Logistics Excellence, Advancement, and Performance Shield (LEAPS) 2025
- Objective: Recognize leadership, innovation, and best practices across logistics in India. Enhance the global competitiveness of India’s logistics ecosystem. Align industry standards with the National Logistics Policy 2022 and PM GatiShakti vision for integrated, sustainable, and resilient infrastructure.
- Scope and Criteria: Covers air, rail, road, and maritime freight operators, warehousing (industrial and agricultural), MSMEs, startups, academic institutions, and e-commerce logistics providers. 13 award categories promote diversity, inclusion, and innovation.
- 13 award categories promote diversity, inclusion, and innovation.
- Align industry standards with the National Logistics Policy 2022 and PM GatiShakti vision for integrated, sustainable, and resilient infrastructure.
Vital Statistics of India Report on Civil Registration System (CRS) 2023
- Births: Total registered: 2.52 crore, a decline of 2.32 lakh from 2022. Indicates continuing fertility decline and demographic transition.
- Total registered: 2.52 crore, a decline of 2.32 lakh from 2022.
- Deaths: Total registered: 86.6 lakh, slightly higher than 86.5 lakh in 2022. Shows post-pandemic stabilization, after the spike in 2021 (102.2 lakh).
- Total registered: 86.6 lakh, slightly higher than 86.5 lakh in 2022.
ISRO Highlights Crew Escape System (CES) for Gaganyaan Mission
- Located at the forward end of the LVM3 rocket.
- Types of CES: Puller Type (used by ISRO): Solid motors pull the crew module away (used in Gaganyaan, Soyuz, Saturn V). Pusher Type: Liquid-fuel engines push the module away (used in SpaceX Falcon 9).
- Working Mechanism: Located at the forward end of the LVM3 rocket. Uses high-burn solid motors to accelerate the crew module faster than the rocket. Triggered by Integrated Vehicle Health Management (IVHM) in case of an emergency. Crew module separation is followed by multi-stage parachute deployment for controlled splashdown.
- Uses high-burn solid motors to accelerate the crew module faster than the rocket.
India Elected Unopposed to United Nations Human Rights Council (UNHRC) for 2026–2028
- Established: 2006 by the UN General Assembly, replacing the former UN Commission on Human Rights.
- Headquarters: United Nations Office, Geneva, Switzerland.
- Previous UNHRC tenures: 2006–2007, 2011–2014, 2014–2017, 2017–2020, 2022–2024, and now 2026–2028.
- India has been elected unopposed to the UN Human Rights Council (UNHRC) for the 2026–2028 term, marking its seventh tenure on the global body.
The India Justice Report 2025
- The India Justice Report 2025 has once again highlighted the glaring under-representation of women in India’s higher judiciary. Despite progress in other public institutions, gender diversity in the Supreme Court and High Courts remains alarmingly low.
- Supreme Court: Women constitute only 3.1% of the total judges, with just one woman among 34 judges.
- High Courts: Women account for 14% of the total strength, with only one woman Chief Justice among 25 High Courts.
- Article 312 empowers Parliament to create new All-India Services, including the AIJS, ensuring uniform standards for recruitment, training, and service.
PM GatiShakti Public
- Launched: 2021
- Objective: Enhance multi-modal infrastructure planning and coordination across sectors such as transport, energy, logistics, and urban development.
- The Government of India has launched PM GatiShakti Public, a public version of the national master plan for infrastructure, marking a key step towards transparent, data-driven, and integrated infrastructure development. This initiative extends the GatiShakti framework, launched in 2021, to the public and private sectors for improved planning and coordination.
- Purpose: Democratizes access to geospatial and infrastructure data for private entities, researchers, consultants, and citizens.
IUCN Elects Vivek Menon as Chair of Species Survival Commission (SSC)
- Significance: The SSC advises the IUCN Secretariat on issues related to biodiversity conservation and species protection.
- Plays a pivotal role in preparing the IUCN Red List of Threatened Species, a critical global index for assessing extinction risks.
India Conducts Multiple Bilateral Military Exercises – 2025
- Aim: Enhance naval interoperability, strengthen maritime partnership, and promote Indo-Pacific regional stability.
- India conducted the inaugural India–South Korea naval exercise at Busan Naval Harbour, marking a key step in Indo-Pacific maritime cooperation. Simultaneously, India began AUSTRAHIND 2025 with Australia and INDRA 2025 with Russia, highlighting its expanding defence partnerships.
- Aim: Strengthen cooperation and interoperability in sub-conventional warfare and urban operations.
- Aim: Enhance counter-terrorism coordination and operational readiness.
Forest Declaration Assessment 2025
- India’s role: Green India Mission, CAMPA, National Afforestation Programme – targeting 26 M ha by 2030.
- Forest Loss & Degradation: 8.1 M ha deforested and 8.8 M ha degraded, with tropical regions accounting for 94% of loss. Primary forests at risk: 6.7 M ha lost, mainly in Latin America and Africa.
- 8.1 M ha deforested and 8.8 M ha degraded, with tropical regions accounting for 94% of loss.
- Carbon & Biodiversity Impact: Deforestation and degradation emitted 3.1 Gt CO₂e (150% of U.S. energy sector emissions). Forested Key Biodiversity Areas (fKBAs) lost 2.2 M ha, increasing extinction risks.
2030 Centenary Commonwealth Games
- The 2030 edition will mark the 100th anniversary of the Games, first held in Hamilton, Canada (1930).
- The Commonwealth Sport Executive Board (2025) has recommended Ahmedabad, Gujarat, as the proposed host city for the 2030 Centenary Commonwealth Games, bringing the prestigious multi-sport event back to India after 20 years.
- India last hosted the Games in 2010 (New Delhi).
- The bid aligns with India’s “Viksit Bharat 2047” vision and aims to position Gujarat as a global sports capital.
Su-57 Fighter Jets
- Capabilities: Stealth technology for reduced radar detection. Supersonic speed and high maneuverability. Advanced avionics and sensor fusion for air superiority and strike missions. Multirole functions: Air-to-air, air-to-ground, and electronic warfare.
- Supersonic speed and high maneuverability.
- Armament: Equipped with guided missiles, precision bombs, and a 30mm cannon.
IUCN Flags Western Ghats, Manas, and Sundarbans as ‘Significant Concern’ Sites
- The share of sites under “Significant Concern” has increased from 26% (2020) to 30% (2025), reflecting rising threats from climate change, tourism, and invasive species.
- Published every 3–4 years, it assesses the conservation status of natural World Heritage sites.
- Out of 7 Indian natural World Heritage sites: 1 site (Khangchendzonga NP, Sikkim) – Good 4 sites (Kaziranga, Nanda Devi, Valley of Flowers, Keoladeo, Great Himalayan NP) – Good with Some Concerns 3 sites (Western Ghats, Manas, Sundarbans) – Significant Concern
- 4 sites (Kaziranga, Nanda Devi, Valley of Flowers, Keoladeo, Great Himalayan NP) – Good with Some Concerns
| Site | Location | Key Issues |
|---|---|---|
| Western Ghats | Maharashtra, Goa, Karnataka, Kerala, Tamil Nadu | Loss of evergreen forests (−5%), urbanisation, tourism, infrastructure projects |
| Manas National Park | Assam (India–Bhutan transboundary) | Habitat degradation, poaching, flood damage, invasive species |
| Sundarbans National Park | West Bengal (India–Bangladesh transboundary) | Climate change, sea-level rise, erosion, tourism pressure |
UNEP’s State of Finance for Forests (SFF) 2025 Report
- Severe Underfunding of Forests Only US$ 8 billion was invested globally in 2023 (91% public, 9% private). An estimated US$ 24 billion per year is needed by 2030 to meet climate and biodiversity targets.
- Only US$ 8 billion was invested globally in 2023 (91% public, 9% private).
- An estimated US$ 24 billion per year is needed by 2030 to meet climate and biodiversity targets.
- Dominance of Public Finance Governments contributed US$ 7.3 billion, mainly China and the U.S. Tropical forest nations contributed only 17% of their domestic spending, showing regional disparities.
COP30 in Belém, Brazil
- Baku–Belém Roadmap to Trillion: A proposed US$ 1 trillion climate finance roadmap by 2035 aims to mobilize funds through public–private partnerships, green bonds, and carbon markets.
- A proposed US$ 1 trillion climate finance roadmap by 2035 aims to mobilize funds through public–private partnerships, green bonds, and carbon markets.
- Overshoot pathway: Temporary exceedance (~1.7°C) may occur, but rapid emission cuts and carbon removal could restore limits later.
- COP as a ‘Summit of Solutions’: COP30 is branded the “COP of Action,” emphasizing practical implementation and financing mechanisms over new promises. The focus is on deploying funds and operationalizing solutions.
Tejas Mk1A
- Reduced maintenance downtime and better mission reliability.
Synchronous All India Elephant Estimation (SAIEE) 2021–25
- Decline: Jharkhand (–68%) and Odisha (–54%) due to mining activities and habitat loss.
- Jharkhand (–68%) and Odisha (–54%) due to mining activities and habitat loss.
- Increase: Chhattisgarh (+82.6%) and Madhya Pradesh due to elephant migration from disturbed eastern habitats.
- Chhattisgarh (+82.6%) and Madhya Pradesh due to elephant migration from disturbed eastern habitats.
NITI Aayog, DP World Launch ‘We Rise’ Initiative for Women Entrepreneurs
- Global Expansion Support: 100 women entrepreneurs will be mentored for international business operations and export readiness.
- Public-Private Partnership Model: Integrates WEP’s network of 90,000+ women entrepreneurs with DP World’s global trade infrastructure.
- Type: Public–private partnership under WEP’s Award to Reward (ATR) framework.
- Objective: Identify and scale high-potential women-led MSMEs for global trade and sustainable growth.
UNTCC Chiefs’ Conclave 2025
- Participants: UNTCC Chiefs from 32 countries, senior UN officials, policymakers, and industry leaders
- Interactive Session: “Leveraging Technology in UN Peacekeeping” with 15 industry leaders
- Defence Expo: 41 exhibitors across 9 operational domains showcasing indigenous weapon systems and technologies
- Dates: 14–16 October 2025
Scheme for Innovation and Technology Association with Aadhaar (SITAA)
- Launched by: Unique Identification Authority of India (UIDAI)
- Promote indigenous research and development in biometrics, artificial intelligence, and cybersecurity
India’s Balancing Act Between the Quad and BRICS Ahead of ASEAN Summit 2025
- Founded: 8 August 1967 (Bangkok Declaration)
- Founded: 2009 (as BRIC); South Africa joined in 2010, forming BRICS.
- Headquarters: Jakarta, Indonesia
- India’s foreign policy priorities are being tested at the upcoming ASEAN Summit (October 26–28, 2025, Kuala Lumpur) and the associated East Asia Summit (EAS). Prime Minister Narendra Modi is expected to attend, with key leaders from the Quad (U.S., Japan, Australia) and BRICS (Brazil, Russia, India, China, South Africa) either present or observing.
Delhi-NCR Implements Stage II of GRAP as AQI Crosses 300
- Established: Introduced in 2017 under Supreme Court directives and the Environment (Protection) Act, 1986.
- Launched in India: 2014, under the Swachh Bharat Abhiyan, with the slogan “One Number – One Colour – One Description.”
- Latest Revision: December 2024 by CAQM to include predictive measures based on IMD and IITM forecasts.
- 2014, under the Swachh Bharat Abhiyan, with the slogan “One Number – One Colour – One Description.”
| Stage | Category | AQI Range | Key Actions |
|---|---|---|---|
| I | Poor | 201–300 | Dust control, waste removal, vehicle norms enforcement |
| II | Very Poor | 301–400 | Mechanical sweeping, C&D (construction & demolition) monitoring, DG set regulations |
| III | Severe | 401–450 | Restrictions on BS-III/IV vehicles, construction limits |
| IV | Severe+ | Above 450 | Truck entry bans, work-from-home orders, halting C&D projects |
Chandrayaan-2’s CHACE-2 Makes First-Ever Observation of Solar CME Impact on Moon
- Successor to CHACE (Chandrayaan-1) and MENCA (Mars Orbiter Mission) instruments
- On 10 May 2024, CHACE-2 recorded the first evidence of a CME-induced increase in lunar exosphere pressure
- Mission: Part of Chandrayaan-2 orbiter
- Launch Date: 22 July 2019, aboard GSLV Mk-III M1
Global Multidimensional Poverty Index (MPI) 2025 Report
- Significant Reduction: Multidimensional poverty dropped from 55% (2005–06) to 16.4% (2019–21), lifting ~414 million people out of deprivation
- Population in MPI Poverty: 1.1 billion (18.3%) live in acute multidimensional poverty
- Severity: 43.6% of poor people (~501 million) experience severe poverty (deprived in ≥50% of MPI indicators)
- Children: Represent 51% of global poor, highlighting intergenerational poverty
INS Vikrant
- Named after the historic INS Vikrant that played a key role in the 1971 Indo-Pak War.
- Officially commissioned on 2 September 2022 by the Prime Minister at Cochin.
- First indigenously built aircraft carrier of India.
| Feature | Details |
|---|---|
| Dimensions | 262 m long, 62 m wide, 18 decks high (≈ 2 football fields) |
| Displacement | ~45,000 tonnes — largest warship built in India |
| Aircraft Capacity | 30 aircraft, including MiG-29K jets, Kamov-31, MH-60R Seahawk helicopters, future indigenous aircraft |
| Crew & Facilities | 1,600 personnel, 16-bed hospital, 2,400 compartments (functions as “city at sea”) |
| Operational Status | Achieved full operational clearance in 2024; part of Western Naval Command |
| Propulsion | Four gas turbines, speeds up to 28 knots (52 km/h) |
UNFPA Report 2025
- Computation: Derived from Age-Specific Fertility Rates (ASFRs) for seven age cohorts — 15–19, 20–24, 25–29, 30–34, 35–39, 40–44, and 45–49 years.
- Urban Areas: Fertility is increasingly postponed to older cohorts (25–34 years), indicating career and education priorities rather than a true decline in reproductive intent.
- Definition: TFR measures the average number of children a woman would bear if she experienced current age-specific fertility rates throughout her reproductive life (ages 15–49).
- Age-Cohort Gaps: Births among women below 15 or above 49 are excluded, despite such cases being non-negligible in some rural or traditional communities.
UNESCO Global Education Report 2025
- The World Bank (2024) estimates closing the global gender education gap could boost global GDP by $15–30 trillion.
- Sub-Saharan Africa & Oceania: Lagging due to poverty, rural isolation, and conflict. Example: In Mali and Guinea, fewer than 20% of girls complete lower secondary education.
- Example: In Mali and Guinea, fewer than 20% of girls complete lower secondary education.
- Women dominate teaching professions, but only 30% of higher education leadership positions globally are held by women.
NITI Aayog’s Roadmap for Climate Action and Energy Transition
- India is approaching its 2030 target of 500 GW non-fossil electricity capacity and aims to achieve net-zero carbon emissions by 2070 under its Nationally Determined Contributions (NDCs). India also targets a 45% reduction in emission intensity of GDP by 2030 (from 2005 levels). NITI Aayog’s draft roadmap outlines institutional and financial measures to achieve these goals.
- Functions: Policy support and data analysis on emissions. Mobilize $100 billion annually in climate finance. Assist in national communications on climate change and manage national emission inventories.
- Mobilize $100 billion annually in climate finance.
- Purpose: Guide policy, coordinate multi-ministry climate action, and develop bankable project pipelines for mitigation and adaptation.
UDAN Scheme
- Launched: 21 October 2016 under the National Civil Aviation Policy (NCAP).
- First Flight: 27 April 2017 (Shimla–Delhi).
- Anniversary: MoCA celebrated the 9th anniversary in 2025.
- Civil Aviation Secretary Samir Kumar Sinha announced that the Regional Connectivity Scheme known popularly as UDAN (Ude Desh Ka Aam Nagrik) will be continued beyond 2027 and its nework will extend to 120 new destinations.
India Ranks 9th Globally in Total Forest Area: FAO Report
- India’s Improved Global Ranking: Current Rank: 9th globally in total forest area (up from 10th in the previous assessment). Issued By: Food and Agriculture Organisation (FAO) of the United Nations. Report Released: Global Forest Resources Assessment 2025.
- Report Released: Global Forest Resources Assessment 2025.
- Latest Edition (2025): Focused on forest resilience, climate adaptation, and sustainable land-use planning.
- Current Rank: 9th globally in total forest area (up from 10th in the previous assessment).
Global Forest Resources Assessment (GFRA) 2025
- 2025 edition marks 80 years of continuous monitoring.
- Total Forests: 4.14 billion hectares; tropical forests make up 45%.
- Planted Forests: 8% of global forests; Asia contributes 23%.
- Protected Areas: 813 million hectares (20% of forests) legally protected.
India’s Critical Mineral Recycling Scheme
- The scheme, approved in September 2025, has started accepting applications.
- Feedstock Availability: India generates 1.75 million tonnes of e-waste and about 60 kilotonnes of spent LIBs annually. The Centre expects feedstock availability to increase manifold over the next 4–5 years, reducing dependency on exports of black mass.
- The Centre expects feedstock availability to increase manifold over the next 4–5 years, reducing dependency on exports of black mass.
- Customs duty elimination on LIB scrap (2025–26 budget) will facilitate imports.
Water ATM Initiative
- PARAM JAL Model: Treats multi-level mine water and dispenses 10 litres for ₹10 via coins or UPI.
- 24×7 Operation: Ensures constant access to clean water in rural and mining-affected areas.
- Community Empowerment: Encourages women-led entrepreneurship and self-help group (SHG) participation for local management.
Draft Labour Policy ‘Shram Shakti Niti’
- Only 7% of jobs in South Asia are highly exposed to automation.
- Around 15% of jobs are AI-human complementary, meaning productivity increases when technology supports human work.
- AI-related roles offer a 30% wage premium over other white-collar positions.
- According to the World Bank’s South Asia Development Update (October 2025):
Skilling for AI Readiness (SOAR)
- Centre of Excellence in AI: ₹500 crore allocated in Union Budget 2025–26
- Support Economic Self-reliance Equip youth with skills for high-demand AI-driven sectors, supporting Atmanirbhar Bharat. Complement PMKVY 4.0 by focusing on emerging technologies to enhance employability and entrepreneurship.
- Complement PMKVY 4.0 by focusing on emerging technologies to enhance employability and entrepreneurship.
- Structured Learning Modules: 3 × 15-hour AI modules for students 1 × 45-hour advanced module for educators
NFR Introduces Intrusion Detection System to Protect Elephants
- Launched by: Northeast Frontier Railway (NFR), under the Ministry of Railways
- Expansion: Additional 146.4 km by April 2026, totaling 210 km
- Real-time signals are sent to control rooms and train drivers
- Coverage: 4 pilot sections across Alipurduar, Lumding, Rangiya, and Tinsukia, covering 64.03 km
Coast is Clear for Doing Business Sustainably – NITI Aayog Report
- Green Cover Norms for Industrial Zones: Existing requirement: 33% green cover. Proposal: Reduce to 10%, similar to Taiwan, Indonesia, and Vietnam. Exception: Polluting industries must maintain up to 25% green cover based on a graded index.
- Exception: Polluting industries must maintain up to 25% green cover based on a graded index.
- Carbon Sequestration & Emissions: Industrial expansion will increase emissions. Existing higher green cover norms (33-40%) act as natural carbon sinks. Simply adopting lower norms of other countries may not suit India’s distinct emissions profile.
- Existing higher green cover norms (33-40%) act as natural carbon sinks.
Blackbuck Makes Comeback in Chhattisgarh’s Barnawapara Sanctuary
- Topography: Gently undulating plains, elevations up to 640 m, crisscrossed by rivers Balmedhi, Jonk, and Mahanadi
- Climate: Annual rainfall ~1,200 mm; pleasant winters Nov–Feb
- The blackbuck, declared locally extinct in Chhattisgarh in 2017, has made a remarkable recovery under ax five-year revival plan (2021–2026) in Barnawapara Wildlife Sanctuary.
- Tourism Infrastructure: Watchtowers, eco-camps, and patrol stations promoting eco-tourism and conservation awareness
India Endorses Transboundary Conservation Plan under CAMI
- Established in: 2014, during COP11 of CMS held in Quito, Ecuador.
- Updated at: COP13 (2020) in Gandhinagar, India, to expand scope and align with global biodiversity goals.
- Coverage: Protects 17 flagship migratory species, including: Saiga antelope Snow leopard Wild camel Urial (mountain sheep) Argali (wild sheep) Bukhara deer Persian leopard
- 2014, during COP11 of CMS held in Quito, Ecuador.
India Re-elected as Vice-Chairperson of UNESCO Anti-Doping Bureau
- Location: Paris, marking the 20th anniversary of the Convention.
- Adoption: 33rd UNESCO General Conference, 19 October 2005
- Entry into Force: 1 February 2007
- Governance Reforms: COP sessions elect a Bureau and Approval Committee to oversee compliance and financing.
‘23for23’ Initiative and National Snow Leopard Census
- India observed International Snow Leopard Day (23 October 2025) with the nationwide ‘#23for23’ campaign. The government unveiled the first-ever National Snow Leopard Census, recording 718 individuals across the Indian Himalayas.
- Global Habitat: 12 countries including India, Nepal, China, Mongolia, Pakistan, Afghanistan, Kazakhstan Found at 3,000–5,000 meters in cold, arid, rocky terrains
- Found at 3,000–5,000 meters in cold, arid, rocky terrains
- Launched by: Ministry of Environment, Forest and Climate Change (MoEFCC)
PM SHRI Scheme
- Launched in September 2022, the PM Schools for Rising India (PM SHRI) scheme aims to upgrade existing schools into model institutions demonstrating National Education Policy (NEP) 2020 principles — focusing on experiential learning, digital education, and holistic development.
- It is jointly funded by the Centre and States (60:40 ratio).
- Targets to develop 14,500 schools across India.
Gyan Bharatam Mission
- Funding Structure: Funds will be disbursed in phased instalments: First Instalment: 70% on approval of the annual budget. Second Instalment: 30% after submission of progress and financial reports, utilisation certificates, and relevant documentation.
- Funds will be disbursed in phased instalments: First Instalment: 70% on approval of the annual budget. Second Instalment: 30% after submission of progress and financial reports, utilisation certificates, and relevant documentation.
- First Instalment: 70% on approval of the annual budget.
- Second Instalment: 30% after submission of progress and financial reports, utilisation certificates, and relevant documentation.
Indian Coast Guard Launches Two Indigenous Fast Patrol Vessels
- Length: 52 metres
- Propulsion System: Equipped with Controllable Pitch Propellers (CPP) — the first in this class in India, ensuring superior manoeuvrability, propulsion efficiency, and operational flexibility.
- Operational Area: Indian Exclusive Economic Zone (EEZ) and island territories, enhancing 24x7 maritime vigilance.
- The Indian Coast Guard (ICG) achieved a major milestone in its maritime security mission with the launch of two advanced Fast Patrol Vessels (FPVs) — ICGS Ajit and ICGS Aparajit — at Goa Shipyard Limited (GSL) on October 24, 2025. These vessels are the 7th and 8th in a series of eight indigenously built FPVs, marking a significant stride in India’s coastal surveillance and defence readiness.
Western Ghats Listed Under “Significant Concern” in IUCN World Heritage Outlook 4
- Recognised as a UNESCO World Heritage Site (since 2012), the Ghats are one of the eight “hottest biodiversity hotspots” globally.
- Formation: Older than the Himalayas, the Western Ghats were formed around 150 million years ago during the breakup of Gondwanaland.
- Fauna: Habitat for 325 globally threatened species. Supports ~30% of the world’s Asian elephant population and ~17% of the global tiger population. Endemic species include the Lion-tailed macaque, Nilgiri tahr, and Malabar civet.
- Supports ~30% of the world’s Asian elephant population and ~17% of the global tiger population.
Lokpal of India
- An independent statutory body established under the Lokpal and Lokayuktas Act, 2013, the Lokpal investigates corruption allegations against public functionaries including the Prime Minister, Ministers, Members of Parliament, and government officials.
- Constitution: The first Lokpal was appointed in March 2019, marking a milestone in institutionalising accountability mechanisms at the central level.
- Chairperson: Justice A.M. Khanwilkar (former Supreme Court judge) – as of 2025.
- Legal Foundation: The Act came into force on 16 January 2014, creating a national-level anti-corruption authority.
Government Plans Integration of RNI, CBC, and PIB for Unified Media Communication Framework
- Registrar of Newspapers for India (RNI): Regulates newspaper registration and publication details in India.
| Institution | Key Function | Administered By |
|---|---|---|
| RNI (Registrar of Newspapers for India) | Registers and monitors newspapers and periodicals, maintains publisher data | MIB |
| CBC (Central Bureau of Communication) | Handles government publicity, campaigns, and advertising | MIB |
| PIB (Press Information Bureau) | Issues press releases, conducts media briefings, and facilitates official communication | MIB |
Trishul Military Exercise
- Indian Air Force: High-tempo “Mahagujraj Operations” using Rafale and Sukhoi-30MKI fighters, IL-78 refuellers, AWACS, helicopters, and drones for precision missions.
- Duration: October 30 – November 10, 2025
- India has commenced a major tri-service military exercise named ‘Trishul’ along the western front with Pakistan, involving coordinated participation of the Army, Navy, and Air Force. The exercise is being conducted from October 30 to November 10, 2025, with a NOTAM (Notice to Airmen) issued for large sections of airspace over Rajasthan and Gujarat.
- Aim: To test and enhance joint operational readiness, interoperability, and tri-service coordination in a high-intensity combat environment.
Pradhan Mantri Kaushal Mudra Yojana (PMKMY)
- Launched by: Launched in 8 April 2015 Ministry of Skill Development and Entrepreneurship (MSDE) in collaboration with the Ministry of Finance.
- Parent Schemes: Pradhan Mantri Mudra Yojana (PMMY) – for collateral-free loans up to ₹10 lakh to small entrepreneurs. Skill India Mission (PMKVY) – to provide employable skill training.
- Pradhan Mantri Mudra Yojana (PMMY) – for collateral-free loans up to ₹10 lakh to small entrepreneurs.
- Objective: To provide financial support for skills training, ensuring access to high-quality government and private training providers, particularly where training costs are high.
Maha MedTech Mission
- Funding Range: ₹5–25 crore per project (up to ₹50 crore in exceptional cases).
- Disbursement Model: Milestone-linked funding, ensuring accountability and innovation outcomes.
- Mentorship: Guidance from industry experts and policymakers for commercialization readiness.
ISRO to Launch GSAT-7R (CMS-03)
- Launch Vehicle: LVM-3 (used previously for Chandrayaan-3 mission in 2023)
- Replaces: GSAT-7A, launched in 2018, which primarily served the Indian Air Force.
- Weight: Approximately 4,400 kg, the heaviest Indian communication satellite to be launched to Geosynchronous Transfer Orbit (GTO) from Indian soil.
Janjatiya Gaurav Divas 2025
- First Observed: 15 November 2021
- Awareness on Government Initiatives: Display ongoing and new tribal welfare schemes under the Ministry of Tribal Affairs.
- Tribal Health and Nutrition Mission to improve socio-economic indicators in remote tribal belts.
- The Union Government has instructed all States and Union Territories to actively prepare for the fifth Janjatiya Gaurav Divas on November 15, 2025, which will mark the culmination of Birsa Munda’s 150th birth anniversary celebrations. The initiative aims to celebrate tribal heritage, showcase cultural contributions, and highlight government schemes targeted at tribal welfare.
Great Nicobar Project
- Strategic Importance: The island’s location near the Malacca Strait, one of the world’s busiest sea lanes, gives it high geostrategic value. The project aligns with India’s “Maritime Vision 2030” and Sagarmala initiatives.
- The project aligns with India’s “Maritime Vision 2030” and Sagarmala initiatives.
Electronics Components Manufacturing Scheme (ECMS)
- Tenure & Incentives: Turnover-linked incentives: 6 years (1-year gestation). Capital expenditure (Capex) incentives: 5 years. Types of incentives: Turnover-linked, Capex-linked, and hybrid to offset manufacturing disadvantages.
- Turnover-linked incentives: 6 years (1-year gestation).
- Capital expenditure (Capex) incentives: 5 years.
- The Government of India has approved the first batch of seven projects under ECMS worth ₹5,532 crore, expected to generate ₹36,559 crore in production. The scheme is part of India’s strategy to strengthen domestic electronics manufacturing and reduce dependence on imports.
Mission for Aatmanirbharta in Pulses (2025–31)
- Mission Duration & Funding: Six years (2025–26 to 2030–31) Outlay: ₹11,440 crore Target: 45% increase in production and 13% expansion in area
- Raise pulse production from 242 lakh MT (2023–24) to 350 lakh MT (2030–31).
- Six years (2025–26 to 2030–31)
- Cluster-based approach: District clusters of 10+ hectares (2 hectares in hilly areas) for focused interventions.
Global Multidimensional Poverty Index Report 2025
- In South Asia, 99.1% of poor people are exposed to at least one climate hazard, and 91.6% face two or more—the highest globally.
- The 2025 Global Multidimensional Poverty Index (MPI) report, titled Overlapping Hardships and Climate Hazards, highlights the intersection of climate change and global poverty. The report overlays climate-hazard data with multidimensional poverty indicators—including health, education, and living standards—for the first time.
- Findings are expected to inform the COP30 agenda in Brazil (Nov 10–21, 2025).
- 8 out of 10 people living in multidimensional poverty (~887 million people) are directly exposed to climate hazards such as extreme heat, floods, drought, or air pollution.
Cloud-Seeding
- Technology & Method: Silver iodide or sodium chloride (salt) particles are dispersed into clouds using aircraft, drones, or ground-based generators. Particles act as nuclei for water condensation, promoting rain formation.
- Mixed results: Some trials report modest increases in precipitation, others inconclusive.
- Cloud seeding is an artificial weather modification technique aimed at enhancing rainfall by dispersing substances into clouds to encourage precipitation.
- Silver iodide or sodium chloride (salt) particles are dispersed into clouds using aircraft, drones, or ground-based generators.
India and the ASEAN Summit
- India–ASEAN Relations: India became a Dialogue Partner of ASEAN in 1995. Partnership was upgraded to Summit level in 2002. These summits offer India a platform to strengthen ties with Southeast Asian nations and discuss key Indo-Pacific issues.
- Partnership was upgraded to Summit level in 2002.
- The revival of the Quad (Australia, India, Japan, U.S.) in 2017 occurred on the sidelines of an ASEAN summit, underscoring ASEAN’s diplomatic centrality.
- Founded: 8 August 1967
Climate Inequality Report 2025
- Climate Inequality and Wealth Concentration: If wealthy individuals make and own all climate-related investments, top 1% wealth share could rise from 38.5% → 46% by 2050. Wealth concentration and climate damage exacerbate both social and economic inequality.
- If wealthy individuals make and own all climate-related investments, top 1% wealth share could rise from 38.5% → 46% by 2050.
- Ownership-based emissions (linked to wealth/capital): Top 1% globally → 41% of emissions. Top 10% in US, Germany, France → 3–5× higher than consumption-based estimates.
- Top 1% globally → 41% of emissions.
8th Central Pay Commission
- The 8th Central Pay Commission is a temporary body constituted by the Union Government of India to review and recommend revisions to the salary structure, allowances, and pension benefits of Central Government employees and pensioners.
- Constitution and Leadership: The 8th CPC was announced in January 2025 and has now been officially constituted. Chairperson: Justice Ranjana Prakash Desai (Retd.) Part-time Member: Prof. Pulak Ghosh, Indian Institute of Management (IIM) Bangalore Member-Secretary: Pankaj Jain, Petroleum Secretary
- The 8th CPC was announced in January 2025 and has now been officially constituted.
- Chairperson: Justice Ranjana Prakash Desai (Retd.)
UN Report Warns Global Emission Reductions are Insufficient for Paris Goals
- Emission Reduction Gap: Countries are projected to reduce emissions by only 17% by 2035 (from 2019 levels). Required reductions to meet Paris targets: 37% by 2035 to limit warming to 1.5°C 57% by 2035 to limit warming to 2°C
- Countries are projected to reduce emissions by only 17% by 2035 (from 2019 levels).
- Required reductions to meet Paris targets: 37% by 2035 to limit warming to 1.5°C 57% by 2035 to limit warming to 2°C
- 37% by 2035 to limit warming to 1.5°C
Elderly in India
- Atal Pension Yojana (APY): Launched: May 9, 2015. Target: Citizens 18–40 years (excluding income-tax payers from Oct 2022). Benefits: Monthly pension INR 1,000–5,000 after age 60; same for spouse; nominee gets accumulated wealth.
- Rashtriya Vayoshri Yojana (RVY): Launched: April 1, 2017. Provides assistive devices (wheelchairs, walkers, hearing aids, dentures) to BPL/low-income seniors. Devices delivered via camps; doorstep delivery for 80+ seniors.
- Established: Finance Act 2015.
- Maintenance and Welfare of Parents and Senior Citizens Act, 2007 (amended 2019): Obligates children/guardians to provide maintenance; removes ₹10,000 ceiling. Mandates nodal officers, special police units, homecare services, and hospital prioritization.
RoDTEP and RoSCTL Schemes
- Extension: The scheme has been extended till March 2026 to continue supporting exporters amid global trade challenges.
- Objective: To refund taxes, duties, and levies incurred by exporters during the manufacturing and distribution process that are not reimbursed under any other mechanism at the central, state, or local level.
- Rate Structure: The current rates range from 0.3% to 4.3% of the export value, depending on the product category.
- It is part of India’s broader strategy to boost merchandise exports and maintain momentum under the Foreign Trade Policy (FTP) 2023.
NITI Aayog Proposes IP and Technology Push to Strengthen India’s Manufacturing Sector
- Increase Manufacturing’s GDP Share: From 15–17% to 25% by 2035.
- Global Leadership: Position India among the top three hubs for advanced manufacturing by 2035.
- Alignment with Viksit Bharat 2047: Strategic milestone for long-term industrial growth.
- Job Creation: Generate over 100 million jobs.
National Blockchain Framework (NBF)
- Launched in September 2024 with a budget of ₹64.76 crore, NBF provides a unified, secure, and scalable architecture for blockchain adoption in governance and public services. India is leveraging blockchain to improve transparency, accountability, efficiency, and trust in government operations, moving beyond its early association with cryptocurrencies.
- Certificates & Document Chain Over 34 crore documents verified, including academic, caste, income, ration card, birth & death certificates. Ensures secure storage, verification, and retrieval of documents.
- Over 34 crore documents verified, including academic, caste, income, ration card, birth & death certificates.
- Property Chain Over 34 crore property documents verified. Provides transparent ownership history and reduces litigation risks.
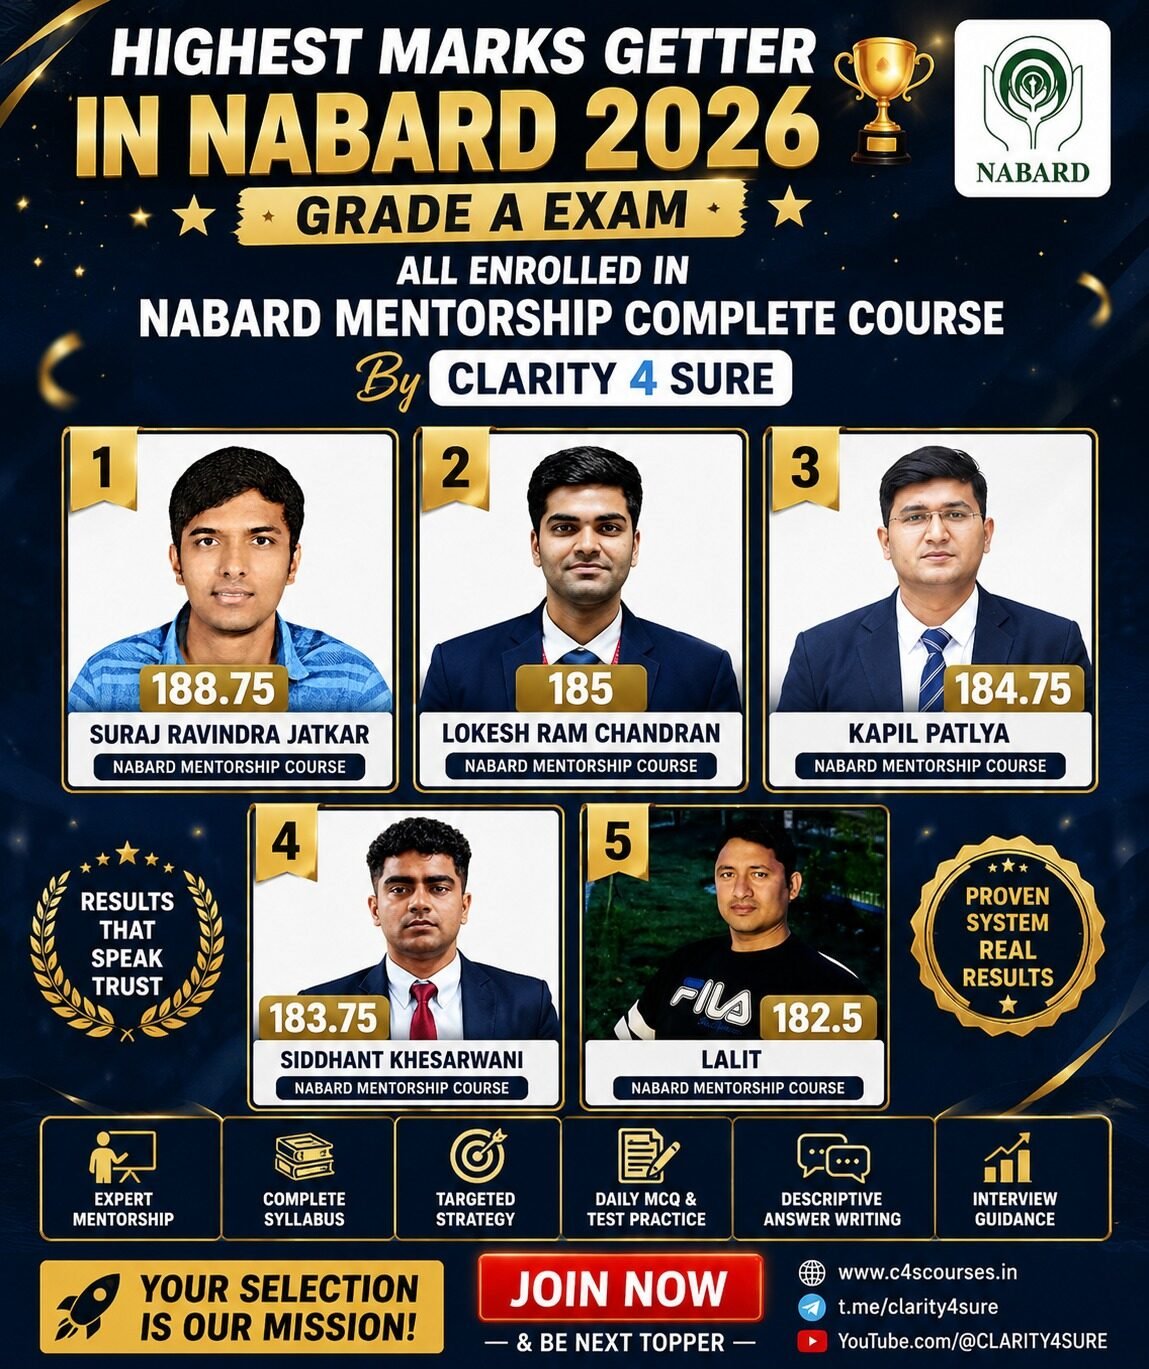
Results that speak
The six highest scorers in NABARD Grade A 2026 were all in one classroom
Every one of them was enrolled in the NABARD Mentorship Complete Course at Clarity 4 Sure. The same descriptive training and the same current affairs notes you are reading now.
- 1Suraj Ravindra Jatkar188.75
- 2Lokesh Ram Chandran185
- 3Vivek Kumar185
- 4Kapil Patlya184.75
- 5Siddhant Khesarwani183.75
- 6Lalit182.5
Banking/Finance · 178
RBI Revised Liquidity Management Framework
- 14-day Variable Rate Repo (VRR) and Variable Rate Reverse Repo (VRRR) will be discontinued as primary liquidity management tools.
- Banks must maintain at least 90% of prescribed CRR daily.
- They will be replaced primarily by 7-day liquidity operations, with additional operations ranging from overnight to 14 days depending on liquidity conditions.
- All existing instruments for durable liquidity management—like Open Market Operations (OMOs), long-term variable rate repos/reverse repos, and forex swap auctions—will continue.
| Term | Definition | Significance |
|---|---|---|
| WACR | Weighted Average Call Rate — average overnight interbank lending rate | Operating target of RBI’s monetary policy |
| Policy Repo Rate | Rate at which RBI lends to banks for short term against government securities | Benchmark for market rates; controls inflation & growth |
| SDF | Standing Deposit Facility — banks can park excess funds without collateral | Floor of policy corridor; absorbs liquidity |
| MSF | Marginal Standing Facility — banks borrow overnight from RBI against securities | Ceiling of policy corridor; lender of last resort |
| VRR / VRRR | Variable Rate Repo / Reverse Repo — liquidity operations with variable interest rate | Discontinued as main tools |
| 7-day Liquidity Operations | RBI injects or absorbs liquidity for 7 days | New primary tool for short-term liquidity management |
| OMOs | Open Market Operations — buying/selling government securities | Manages durable liquidity |
| Forex Swap Auctions | RBI swaps rupees for foreign currency with banks | Manages forex liquidity & market stability |
| CRR | Cash Reserve Ratio — % of NDTL banks must maintain with RBI | Ensures liquidity & financial stability |
RBI Revises Guidelines for Small Business Loans
- Capital rules eased: Banks can use foreign-currency and overseas-rupee bonds as Additional Tier 1 (AT1) capital, facilitating access to global markets.
- Seven directions issued: Three mandatory Four open for consultation (feedback until October 20, 2025)
- Four open for consultation (feedback until October 20, 2025)
- Previous rule: Banks could revise the spread (additional interest over the base rate linked to borrower credit risk) only once every three years.
| Term | Definition | Significance |
|---|---|---|
| Spread | Additional interest rate charged over the base/reference rate based on borrower credit risk | Determines cost of borrowing; now adjustable before 3-year period |
| Fixed-rate loan | Loan with interest rate fixed for the tenure | Provides interest stability to borrowers |
| Working Capital Loan | Short-term loan to meet daily operational expenses | Supports liquidity needs of businesses |
| Additional Tier 1 (AT1) Capital | Capital instruments that absorb losses while the bank remains a going concern | Helps banks meet regulatory capital requirements; can be raised via foreign/overseas-rupee bonds |
| CKYC (Central Know Your Customer) | Centralized database of customer identity information | Ensures accurate borrower data and faster reporting |
| Urban Co-operative Banks | Local banks serving urban areas, often MSMEs | Expanded role increases credit access for small businesses |
Moody’s Affirms India’s Sovereign Rating
- Local-currency bond ceiling A2: Higher than sovereign rating, indicates scope for stronger performance of domestic borrowers relative to government.
- Long-term issuer ratings (local & foreign currency): Baa3 (affirmed).
- Local-currency senior unsecured rating: Baa3 (affirmed).
- Short-term local-currency rating: P-3 (affirmed).
| Aspect | Details |
|---|---|
| Strengths | - Large, fast-growing economy - Sound external position (adequate forex reserves, manageable external debt) - Stable domestic financing base for fiscal deficits - Resilience against external shocks (e.g., high U.S. tariffs, global trade headwinds) |
| Weaknesses | - High government debt burden - Weak debt affordability - Slow fiscal consolidation; revenue base eroded by measures to boost private consumption - Long-standing structural fiscal weaknesses |
Sebi Bars Man Industries & Top Executives Over Fund Diversion
- Diversion of funds to subsidiaries.
| Aspect | Key Points |
|---|---|
| Prohibition on Misuse | Funds raised via IPO, preferential allotment, or debt must be used as disclosed; diverting to promoters/directors without approval is banned. |
| Disclosure Requirements | All material transactions and related-party dealings must be reported to stock exchanges and in annual financial statements; deviations in fund usage must be disclosed promptly. |
| Corporate Governance | Independent directors oversee fund use and approve related-party transactions; audit committees review fund allocation and financial statements. |
| SEBI Investigation & Enforcement | SEBI can inspect, audit, and requisition data; violations can lead to capital-raising bans, board prohibitions, and monetary penalties. |
| Investor Protection | SEBI can direct recovery of misused funds; companies must refund diverted funds to investors. |
RBI Warns NBFCs Against Aggressive Business Growth
- RBI urged NBFCs to: Adopt a compliance-first culture. Follow Fair Practices Codes strictly. Address customer grievances effectively. Review compensation and incentive structures to prevent poor service and unethical practices.
- Adopt a compliance-first culture.
India Phasing in Secured Overnight Rupee Rate (SORR) to Replace MIBOR
- Benefits: Provides a robust benchmark for domestic and foreign investors. Facilitates foreign participation in India’s debt markets by improving hedging and risk management. Average SORR has been ~10 basis points lower than MIBOR since July 2025.
- MIBOR underpins ~$1 trillion in interest-rate swaps but is based on only ~2% of the funding market.
- Average SORR has been ~10 basis points lower than MIBOR since July 2025.
- Need for Transition: MIBOR underpins ~$1 trillion in interest-rate swaps but is based on only ~2% of the funding market. Secured rates provide a more accurate reflection of borrowing costs, improving transparency for derivatives, consumer loans, and hedging instruments.
| Feature | Mumbai Interbank Outright Rate (MIBOR) | Secured Overnight Rupee Rate (SORR) |
|---|---|---|
| Type of Rate | Unsecured interbank rate | Secured overnight rate |
| Underlying Market | Banks’ lending to each other without collateral | Banks’ overnight lending collateralized by government securities |
| Tenor | Typically short-term, overnight, or term | Overnight only |
| Benchmark Usage | Reference for loans, floating-rate bonds, derivatives, and money market instruments | Will replace MIBOR as a risk-free benchmark for pricing loans, bonds, derivatives, and other financial contracts |
| Risk Profile | Higher credit risk (reflects interbank default risk) | Lower credit risk (secured by government securities, virtually risk-free) |
| Global Alignment | Similar to LIBOR (London Interbank Offered Rate), which is being phased out | Similar to SOFR (US), SONIA (UK), and €STR (Eurozone) – risk-free overnight rates |
| Calculation Method | Based on quotes submitted by banks in the interbank market | Based on actual transactions in the secured overnight repo market |
| Regulatory Aim | Traditional benchmark for Indian rupee money markets | Enhance transparency, reliability, and align with global risk-free rate standards |
TATA AIG Partners with Equitas Small Finance Bank to Expand Insurance Access
- Aims to increase insurance penetration in underserved semi-urban and rural regions.
- Nature of Partnership: Customers of Equitas Bank can now purchase TATA AIG’s general insurance products through the bank’s network. Products offered include motor, health, personal accident, travel, and other non-life insurance solutions.
- Customers of Equitas Bank can now purchase TATA AIG’s general insurance products through the bank’s network.
- TATA AIG General Insurance Company Ltd has entered into a bancassurance partnership with Equitas Small Finance Bank to enhance the distribution of non-life insurance products, particularly in semi-urban and rural India.
FPI Outflows from Indian Equities
- Foreign Portfolio Investors (FPIs) withdrew ₹23,885 crore from Indian stocks in September 2025, marking the third consecutive month of net outflows, according to NSDL data.
- FPIs hold ~16–18% of Indian market capitalization, making their flows crucial for market sentiment.
- Governed by SEBI FPI Regulations, 2019.
- FPIs are investors (institutions, hedge funds, individuals) registered with SEBI who invest in Indian financial assets like: Stocks Bonds Mutual funds
| Feature | Foreign Portfolio Investment (FPI) | Foreign Direct Investment (FDI) |
|---|---|---|
| Nature | Investment in financial assets (stocks, bonds, etc.) | Investment in physical assets/companies (factories, infrastructure, JV) |
| Duration | Short-term, liquid | Long-term, stable |
| Control | No control over management | Provides management control/ownership |
| Volatility | Highly volatile (quick entry & exit) | Stable and less volatile |
| Regulation | SEBI (Securities market regulator) | DPIIT + RBI (FEMA guidelines) |
ADB Downgrades India’s Growth Outlook for FY26
- The Asian Development Bank (ADB) has lowered India’s economic growth forecast for the current financial year (2025-26) to 6.5% from the earlier 6.7%, mainly due to the impact of 50% U.S. tariffs on imports from India. The growth outlook for 2026-27 has also been revised downward to 6.5% from 6.8%.
| Dimension | Key Highlights |
|---|---|
| Growth Forecast | • Developing Asia’s growth for 2025 revised: 4.9% → 4.8%. • 2026 forecast cut: 4.7% → 4.5%. • Downgrades due to global uncertainty, especially in India & Southeast Asia. |
| Impact of U.S. Tariffs | • Elevated tariffs cover ~60% of exports to the U.S. • Key affected sectors: textiles, garments, jewellery, shrimp, chemicals. • Likely to weigh on growth in H2 2025-26 and 2026-27. • Merchandise export growth modest, but services exports remain strong. • Investment growth subdued amid trade uncertainty. |
| Domestic Demand & Consumption | • Consumption demand expected to grow faster, aided by lower food prices and tax cuts. • Public investment continues to support growth momentum. |
| Inflation Outlook | • FY26 inflation revised down to 3.1% due to low oil & falling food prices. • FY27 inflation projected at 4.2% as food prices normalize. |
India’s Fiscal Deficit
- The Centre’s fiscal deficit for April–August 2025 stood at 38.1% of the full-year Budget Estimate (BE), as per data released by the Controller General of Accounts (CGA).
- Use of Reserves: Dividend transfers from RBI/PSUs.
- External Aid/Loans: From multilateral institutions (World Bank, ADB, AIIB).
| Type of Deficit | Formula | Meaning | Implication |
|---|---|---|---|
| Fiscal Deficit | Total Expenditure – (Revenue Receipts + Non-debt Capital Receipts) | Borrowing requirement of govt. | Indicates debt burden. |
| Revenue Deficit | Revenue Expenditure – Revenue Receipts | Govt borrowing to meet daily expenses. | Fiscal imprudence. |
| Primary Deficit | Fiscal Deficit – Interest Payments | Borrowings excluding past debt interest. | Shows fresh burden of current policies. |
| Effective Revenue Deficit | Revenue Deficit – Grants for capital creation | Refines revenue deficit by excluding productive transfers. | Used in Budget targets. |
| Monetised Deficit | Part of Fiscal Deficit financed by RBI printing new money | Direct monetisation of deficit. | Highly inflationary, rarely used now. |
RBI Launches Scheme to Activate Inoperative Accounts and Settle Unclaimed Deposits
- A bank savings/current account that has had no customer-initiated transactions for 2 years (as per RBI guidelines).
- Banks will receive 5%–7.5% of amounts (up to ₹25,000) for: Reactivating inoperative accounts. Settling unclaimed deposits with legitimate owners.
- Objective: Reduce the stock of dormant/inoperative accounts in the banking system. Ensure depositors receive their rightful funds, improving customer trust in banks.
- The Reserve Bank of India (RBI) has launched a one-year incentive scheme (October 2025 – September 2026) to encourage banks to reactivate inoperative accounts and repay unclaimed deposits to rightful claimants.
SEBI Seeks Disclosures on Promoters’ In-Laws and Related Entities
- Entities where these relatives hold over 20% shareholding, even if they do not own shares in the listed company
- Now, listed companies must also disclose relationships with: Promoters’ in-laws (beyond immediate family). Entities where such relatives hold beneficial interest or control.
- Promoters’ in-laws (beyond immediate family).
- Current loophole: Some promoters route money through relatives (like in-laws) or associated entities to avoid RPT scrutiny.
RBI Governor to Chair New Payments Regulatory Board (PRB)
- The committee suggested amendments to the Payment and Settlement Systems Act, 2007 and proposed an independent regulatory board to handle payment-related issues.
- RBI Members (3): Deputy Governor Executive Director in charge of Payment and Settlement Systems Governor
- Government Nominees (2): Secretary, Department of Financial Services (DFS) Secretary, Ministry of Electronics and Information Technology (MeitY)
- The move follows recommendations from an inter-ministerial committee headed by the Economic Affairs Secretary.
RBI Raises Overseas Perpetual Debt Limit for Banks
- Limit for AT1 Inclusion: Banks can now include up to 1.5% of Risk-Weighted Assets (RWA) through perpetual debt.
- Foreign Issuance: Debt issued in foreign currency or in Indian rupees overseas can now be fully counted towards the 1.5% AT1 limit.
- Earlier Norms: Previously, only less than half of the 1.5% AT1 limit could be raised overseas, the rest had to be domestic.
- Regulator: Reserve Bank of India (RBI) issued a circular allowing banks to raise perpetual debt overseas and include it in their core capital.
PhonePe and Mastercard Launch Tap-and-Pay Feature
- Mastercard users can tap their smartphones at NFC-enabled payment terminals to complete purchases.
- Cardholders can save their Mastercard credit, debit, and prepaid cards on their smartphones for seamless payments.
Major Rule Changes Effective from October 1, 2025
- Deadline: Government employees cannot switch from Unified Pension Scheme (UPS) to NPS after September 30, 2025.
- From October 1, 2025, several important regulatory and policy changes across banking, pensions, ticketing, and postal services will take effect. These changes aim to improve efficiency, enhance transparency, and provide greater flexibility to consumers.
- 100% equity option allowed for non-government subscribers.
- Phased implementation: Phase 1: October 4, 2025 – January 2, 2026. Phase 2: Full roll-out after January 2, 2026.
RBI Raises Limit for Perpetual Debt in Banks’ Core Capital
- New Rule (Sept 2025): Entire 1.5% of RWA can now be raised overseas, either in foreign currency or in rupees issued abroad.
- The Reserve Bank of India (RBI) has revised rules on perpetual debt inclusion in banks’ capital structure, allowing a higher share of such debt raised overseas to count towards Additional Tier-1 (AT1) capital.
- Earlier Rule: Perpetual debt up to 1.5% of Risk-Weighted Assets (RWA) could be counted in AT1 capital, but less than half was allowed from foreign currency or rupee-denominated bonds issued overseas.
- Additional Tier-1 (AT1) Capital: The core capital of banks, consisting of equity and perpetual instruments, used to absorb losses while the bank is still a going concern.
RBI MPC Meeting – October 1, 2025
- Cumulative Rate Cuts in 2025: 100 bps (Feb, Apr, Jun) → from 6.5% to 5.5%
- Basel III Norms Revised capital adequacy framework to be implemented from April 1, 2027. Strengthens resilience of banks through higher buffers.
- Repo Rate: Unchanged at 5.50% (second consecutive pause)
- GDP Growth (FY26): Revised upward to 6.8% (from 6.5%)
| Term | Definition | Impact / Purpose |
|---|---|---|
| Repo Rate | Rate at which RBI lends short-term funds to commercial banks against government securities as collateral. | ↑ Repo → Loans costly → Inflation control. ↓ Repo → Loans cheaper → Boosts growth. |
| Reverse Repo Rate | Rate at which RBI borrows money from commercial banks. | ↑ Reverse Repo → Absorbs liquidity → Controls inflation. ↓ Reverse Repo → Banks lend more → Boosts growth. |
| ECL (Expected Credit Loss) Framework | Forward-looking provisioning system where banks estimate expected loan losses instead of waiting for defaults. | Strengthens banking sector resilience by reducing risk of sudden shocks. |
| Basel III Norms | International banking reforms focusing on capital adequacy, leverage, and liquidity standards. | Ensures financial stability, prevents systemic risks, enhances risk management. |
RBI MPC October 2025 – Key Takeaways
- Cumulative rate cuts in 2025: 100 bps (Feb, Apr, Jun) from 6.5% → 5.5%.
- Merchandise exports: +2.5%, imports: +2.1% (April–August 2025).
- The Reserve Bank of India (RBI) conducted the 57th Monetary Policy Committee (MPC) meeting from 29 September – 1 October 2025.
- Revised upward to 6.8% from 6.5% in August projection.
| Instrument | Rate | Remarks |
|---|---|---|
| Repo Rate | 5.50% | Unchanged (second consecutive pause) |
| Reverse Repo (SDF) | 5.25% | By convention, 25 bps below repo |
| Bank Rate & MSF | 5.75% | No change |
RBI Withdraws System-Level Lending Cap for Large Corporates
- Previous Circular: Set credit exposure limits at the banking system level: ₹25,000 crore in FY18 → ₹15,000 crore in FY19 → ₹10,000 crore from FY20. Aimed to reduce concentration risk across the banking system.
- Set credit exposure limits at the banking system level: ₹25,000 crore in FY18 → ₹15,000 crore in FY19 → ₹10,000 crore from FY20.
- ₹25,000 crore in FY18 → ₹15,000 crore in FY19 → ₹10,000 crore from FY20.
- Current Framework: Large Exposure Framework continues: Single borrower: ≤20% of Tier-1 capital Corporate group: ≤25% of Tier-1 capital
RBI Proposes Lower Risk Weights for NBFC Infrastructure Loans
- Objective: Reduce the cost of infrastructure financing, improve risk assessment, and optimise capital allocation.
- Market participation: Could attract new players to infrastructure lending.
- Supervisory oversight is essential to avoid underestimation of risks.
RBI to Consider Issuance of New Urban Cooperative Bank (UCB) Licences
- 2004 Freeze: Fresh licenses for UCBs were stopped due to weak financial health and governance issues in the sector.
- Consolidation Drive (2004–24): Amalgamation of unviable UCBs. Closure of non-viable entities. Suspension of new licenses.
- As a result, the number of UCBs fell from 1,926 (2004) to 1,472 (March 2024).
- Urban Cooperative Banks (UCBs) are cooperative banks operating in urban and semi-urban areas, primarily catering to small borrowers, traders, low- and middle-income groups.
| Aspect | Legal Framework / Authority | Scope of Regulation |
|---|---|---|
| Banking Regulation Act, 1949 | Applied to UCBs since 1966; regulated by RBI | Banking activities such as deposit mobilization, lending, capital adequacy, prudential norms, and supervision. |
| State Cooperative Societies Act | Registration under respective State Act | Governance, management elections, audit, and administrative control at the state level. |
| Multi-State Cooperative Societies Act, 2002 | Registration if UCBs operate in more than one state | Governance, management elections, audit, and administration under Central Registrar of Cooperative Societies. |
RBI Eases Bank Lending to Boost Corporate Growth and Capital Markets
- Withdrawal of the 2016 lending cap framework will allow banks to lend more flexibly.
- Banks can now finance mergers and acquisitions, reducing the cost of corporate takeovers.
- Revised ECB norms will expand the pool of eligible borrowers and lenders, relax borrowing limits, and simplify reporting.
- Bank credit growth has lagged behind economic growth; these measures aim to expand banks’ corporate lending books.
Nuvama Wealth Gets SEBI Approval to Set Up Mutual Fund Business
- The sponsor is the promoter who sets up the mutual fund and AMC. According to SEBI (Mutual Funds) Regulations, 1996, the following conditions must be fulfilled:
| Criteria | Key Requirements |
|---|---|
| Track Record & Reputation | • Minimum 5 years of business track record in financial services. • Positive net worth in each of the last 5 years. • Net worth > ₹50 crore in the immediately preceding year. • Profitability in at least 3 out of 5 years. |
| Fit & Proper Criteria | • Must satisfy SEBI’s “fit and proper person” norms. • No record of fraud, conviction, or regulatory violations. |
| Shareholding & Contribution | • Sponsor must contribute ≥ 40% of AMC’s net worth. • Minimum AMC net worth: ₹50 crore (as per latest SEBI amendments). • Contribution ensures “skin in the game”. |
| Professional Setup | • AMC & Trustee Co. must have ≥ 50% independent directors/trustees. • No conflict of interest with the sponsor. |
| Regulatory Approval | • SEBI conducts due diligence on financial strength, governance, compliance history, and risk management before granting approval. |
Fin-Influencers
- Finfluencers are social media content creators who provide advice or opinions on stocks, mutual funds, crypto, insurance, trading strategies, and personal finance.
- Influence: Large following among young, first-time investors.
- Misinformation: Many finfluencers provide unverified or fraudulent advice.
- Lack of Registration: Most are not registered with SEBI as investment advisers (IA) or research analysts (RA).
External Commercial Borrowings (ECBs)
- Minimum Maturity Period: ECBs must have a defined tenure (e.g., 3–5 years or more depending on end-use).
- Mandatory Reporting: Borrowers must obtain a Loan Registration Number (LRN) and report transactions via Form ECB to the RBI.
- Borrowers: Indian corporates, Public Sector Undertakings (PSUs), Non-Banking Financial Companies (NBFCs), trusts, and institutions.
- Lenders: International banks, multilateral financial institutions, export credit agencies, foreign equity holders, and other recognised entities.
Basic Savings Bank Deposit (BSBD) Accounts
- Over 566 million PMJDY accounts have been opened, holding deposits of approximately ₹2.67 trillion.
- Provides a standardised, cost-free, and accessible account for low-income and first-time bank users.
- A Basic Savings Bank Deposit (BSBD) account is a no-frills savings account designed to provide basic banking facilities to every individual without requiring a minimum balance.
- Accounts opened under the Pradhan Mantri Jan Dhan Yojana (PMJDY) are treated as BSBD accounts.
| Feature | Description |
|---|---|
| 1. Zero Minimum Balance | No minimum balance requirement. All basic facilities are provided free of charge. |
| 2. Unlimited Deposits | Deposits allowed through cash, ATMs, cash deposit machines, and electronic channels without any limit. |
| 3. Free Core Services | • Minimum four free withdrawals per month (including ATM & fund transfers) • Free debit card and ATM facilities • Cheque book with at least 25 leaves per year • Free passbook or monthly statement • Free internet and mobile banking access |
| 4. Unlimited Digital Transactions | No cap or charge on UPI, NEFT, RTGS, IMPS, or PoS transactions. |
| 5. Optional Paid Services | Banks may offer additional services with or without charges, but must follow transparent and non-discriminatory practices with prior disclosure to customers. |
| 6. Single Account Restriction | • Only one BSBD account allowed per customer across all banks. • Customers must declare they do not hold another BSBD account. • If another savings account exists, it must be closed within 30 days of opening a BSBD account. • BSBD holders may also open term deposit accounts. |
| 7. Conversion and Switching | Existing savings account holders can convert their accounts to BSBD within seven days upon request. |
Scale-Based Regulation (SBR) Framework
- The Reserve Bank of India (RBI) has directed 15 Upper Layer Non-Banking Financial Companies (NBFCs), including Tata Sons (a Core Investment Company - CIC), to list on stock exchanges by 30 September 2025.
- To strengthen financial stability and regulatory oversight in the NBFC sector.
- Governance and Board Oversight Upper Layer NBFCs must adopt enhanced corporate governance, independent board composition, and risk management frameworks comparable to banks.
- Listing Requirement (for Upper Layer NBFCs) RBI mandates that NBFCs identified in the Upper Layer must be listed on a recognised stock exchange within three years of classification. This enhances market discipline and transparency.
| Layer | Category Name | Description / Entities Covered | Regulatory Intensity |
|---|---|---|---|
| 1. Base Layer (NBFC-BL) | Smaller NBFCs | Non-systemically important NBFCs (e.g., small loan companies, investment firms) | Light |
| 2. Middle Layer (NBFC-ML) | Larger systemically important NBFCs | Includes deposit-taking NBFCs, large housing finance companies, infrastructure debt funds, etc. | Moderate |
| 3. Upper Layer (NBFC-UL) | Top 10–15 large and systemically critical NBFCs | Identified by RBI based on size, leverage, interconnectedness, complexity, and risk profile | High |
| 4. Top Layer (NBFC-TL) | Possible future category | To be used if RBI observes extreme risk concentration in certain NBFCs | Very High |
RBI Proposes Overhaul of ECB Framework
- Companies may raise funds up to the higher of $1 billion in outstanding ECBs or total external and domestic borrowings up to 300% of net worth, based on the latest audited balance sheet.
- Operational Guidelines: ECB proceeds must be repatriated immediately and credited to an INR account with a bank in India. Pending deployment, funds can be held in fixed deposits for up to 12 months. Funds meant for permissible foreign currency expenditure can be held in foreign currency accounts in India or invested in high-quality overseas deposits until use. Restructuring or insolvency cases may raise ECBs only if permitted under their resolution plan.
- Borrowing Limits Linked to Net Worth: Companies may raise funds up to the higher of $1 billion in outstanding ECBs or total external and domestic borrowings up to 300% of net worth, based on the latest audited balance sheet. The move ties borrowing capacity to the borrower’s financial resilience rather than a uniform cap.
- Market-Determined Interest Rates: The RBI proposes to remove the all-in-cost ceiling (currently capped at 450 bps over benchmark). Borrowing costs will instead be aligned with prevailing market conditions, improving pricing efficiency and flexibility.
Multi-Asset Allocation Funds
- Tax Efficiency If equity allocation exceeds 35%, the fund is taxed as a hybrid-debt fund (post-April 2023 norms). Earlier, some funds maintained >65% equity to avail equity taxation benefits, but SEBI’s latest rules ensure clearer classification.
- If equity allocation exceeds 35%, the fund is taxed as a hybrid-debt fund (post-April 2023 norms).
- Earlier, some funds maintained >65% equity to avail equity taxation benefits, but SEBI’s latest rules ensure clearer classification.
- As per the Securities and Exchange Board of India (SEBI), MAAFs must invest a minimum of 10% in each of at least three asset classes at all times.
| Feature | MAAFs | Equity Funds |
|---|---|---|
| Asset Mix | Equity + Debt + Commodities | Primarily Equity |
| Volatility | Moderate | High |
| Return Potential (3–5 yrs) | 9–12% (approx.) | 11–14% (approx.) |
| Downside Protection | High (diversified assets) | Low |
| Best Suited For | Moderate-risk, long-term investors | High-risk, growth-focused investors |
Kiwi Launches Interest-Backed EMI Option on UPI
- Objective: To promote credit-based UPI transactions while reducing the effective cost of borrowing for consumers.
RBI Tightens Related Party Lending Rules, Introduces Unified Framework
- Shareholders holding over 5% equity
- Loans to directors backed by government securities, life insurance, or FDs are permitted (LTV ≤ 100%).
- Promoters and Key Managerial Personnel (KMPs)
- Earlier, the restrictions were limited only to directors and entities in which they held interests.
| Bank Asset Size | Maximum Loan to Related Party (Before Board Approval) |
|---|---|
| Over ₹10 lakh crore | ₹50 crore |
| ₹1–10 lakh crore | ₹10 crore |
| Below ₹1 lakh crore | ₹5 crore |
RBI Recognises FIDC as Self-Regulatory Organisation (SRO) for NBFCs
- Established: 2004
- Objective: To promote best governance practices, industry ethics, and collaborative engagement between NBFCs and regulators.
- Formal Role in Self-Regulation As an SRO, FIDC will now play an official supervisory and coordination role for NBFCs. It will help bridge communication between the RBI and NBFCs on policy, compliance, and operational matters.
- It will help bridge communication between the RBI and NBFCs on policy, compliance, and operational matters.
NITI Aayog Moves to Simplify Tax for Foreign Firms
- Optional Scheme: Foreign companies may opt in for simplicity or opt out to file a regular return if their actual profits are lower.
- Alignment with Global Norms: The scheme would align with OECD principles and avoid retrospective amendments.
India Considers Early Warning Framework to Prevent Corporate Insolvency
- Statutory Authority Under: Insolvency and Bankruptcy Code (IBC), 2016
- Headquarters: New Delhi
- Mandatory risk reporting: Directors and auditors may need to report distress signs to regulators and creditors.
- The Insolvency and Bankruptcy Board of India (IBBI) is the key regulatory authority overseeing India’s insolvency resolution framework under the Insolvency and Bankruptcy Code (IBC), 2016. It plays a critical role in maintaining creditor confidence, improving the ease of doing business, and strengthening the financial system’s stability.
RBI’s AI Committee Report Sets Roadmap for Ethical, Responsible, and Inclusive Use of AI in Indian Banking
- Governance and Accountability: Strong governance mechanisms for AI adoption in banks. Clear accountability for AI models and policy oversight. Banks expected to monitor, report, and mitigate algorithmic bias to ensure fairness, diversity, and inclusivity.
- Banks expected to monitor, report, and mitigate algorithmic bias to ensure fairness, diversity, and inclusivity.
- Clear accountability for AI models and policy oversight.
- Integration with India’s Digital Public Infrastructure (Aadhaar, UPI, account aggregators) to expand credit availability and financial inclusion.
DARPG Rankings Spotlight Customer Service Improvements in Indian Banking and Insurance
| Category | Key Highlights |
|---|---|
| Overall DFS Performance | • Banking Division: Ranked 14th (↑ from 24th in April 2025). • Insurance Division: Ranked 12th (↑ from 30th in April 2025). • Pension Reforms Division: Achieved Top Rank (↑ from 14th in April 2025). • Grievances Addressed: 74.38% • Appeals Resolved: 60.22% |
| Complaint Volume & Resolution | • Total Banking Grievances: 22,013 • Resolved: 16,985 cases (≈77%). • Turnaround Time (TAT): Majority resolved within 21 days; only 155 exceeded TAT. • PSBs: Only 24 complaints exceeded TAT. • NBFCs/Private Banks: 89 complaints exceeded TAT. • Appeals: PSBs had no appeals pending beyond 30 days; NBFCs/private banks had 20 pending. |
| GRAI Index Metrics (Revised 2025 Framework) | • Efficiency (55%) – Resolution within 21 days, average resolution time, and pending grievances. • Feedback (35%) – Customer satisfaction levels and appeal trends. • Organisational Commitment (10%) – Adequacy of grievance-handling staff vs. complaint volume. • Note: Domain knowledge parameter was removed in the revised assessment. |
| Top-Ranked Banks (August 2025) | Public Sector Banks (PSBs): • 1st – Indian Overseas Bank • 2nd – Bank of India Private Sector Banks: • 1st – Yes Bank • Lowest – IndusInd Bank • Karur Vysya Bank – Best among smaller private banks. |
| Insurance Companies Rankings (August 2025) | • 1st: New India Assurance (↑ from 7th in July 2025). • 2nd: Life Insurance Corporation of India (LIC) – consistent rank for July & August 2025. |
RBI’s Digital Payment Authentication Overhaul to Enhance Security and User Convenience
- Shift from OTP-centric system: Maintains mandatory two-factor authentication (2FA). Moves away from a static one-time password (OTP) approach to dynamic, risk-based checks.
- Maintains mandatory two-factor authentication (2FA).
- Additional verification applied only when transactions appear suspicious (e.g., new device, odd timing, overseas).
- Alternative Authentication Methods: Banks can offer biometrics, device-binding, or other methods as one of the two authentication factors. Supports a layered, zero-trust approach, improving security without creating friction.
RBI May Allow Real Estate Projects to Access Offshore Loans to Boost Dollar Inflows
- Lender Relaxation: Current rule: ECB lenders must comply with FATF or IOSCO regulations. Draft proposal: Any person resident outside India can be a “recognised lender,” simplifying cross-border lending.
- Current rule: ECB lenders must comply with FATF or IOSCO regulations.
- Draft proposal: Any person resident outside India can be a “recognised lender,” simplifying cross-border lending.
- Land Acquisition: Builders can use ECBs to purchase land for commercial or residential projects, reducing reliance on Joint Development Agreements (JDAs).
India Expands UPI Reach to Qatar
- Launched: 2016 by the National Payments Corporation of India (NPCI).
- Beneficiaries: Around 8.3 lakh Indians living in Qatar, who will now experience faster and cheaper money transfers.
- Partnership: NPCI International Payments Ltd (NIPL), Qatar National Bank (QNB), and Japanese payment gateway NETSTARS.
- Function: Enables instant, real-time fund transfers between bank accounts through mobile platforms using QR codes or phone numbers.
Private Banks Lag Public Banks in Market Capitalisation
- IndusInd Bank: Worst performer among top 20 lenders, losing 15.7%, partly due to accounting lapses reported earlier in 2025.
- HDFC Bank: mcap declined by 4.8%.
- ICICI Bank: mcap declined by 6.7%.
- SBI (State Bank of India): mcap gained 10%.
SEBI Launches Validated UPI Handles to Secure Investor Payments
- Unique UPI IDs: Every SEBI-registered intermediary (brokers, mutual funds, etc.) will now use a UPI handle ending with @valid. Suffixes like .brk (broker) or .mf (mutual fund) indicate the type of intermediary.
- Every SEBI-registered intermediary (brokers, mutual funds, etc.) will now use a UPI handle ending with @valid.
- Trust Symbols: Payments via @valid handles display a green triangle with a thumbs-up symbol to confirm authenticity. QR codes with the same symbol allow investors to verify the entity before making payments.
- QR codes with the same symbol allow investors to verify the entity before making payments.
Indian Banks to Overhaul Business Correspondent (BC) Network
- NIBM (National Institute of Bank Management) was established by the RBI in 1969.
- Proposal for a minimum fixed allowance/incentive of ₹5,000/month, independent of account openings/transactions.
- Facilitating cash deposits, withdrawals, and fund transfers.
- Disbursing government benefits through Direct Benefit Transfers (DBT).
RBI Allows Banks to Fund Corporate Acquisitions
- The Reserve Bank of India (RBI), on 1 October, proposed allowing banks to finance corporate acquisitions. This is a big change, as banks were previously restricted from this area. The move is expected to make capital cheaper and more available for companies and investors.
- The rule was originally introduced to prevent speculative takeovers and limit credit exposure to high-risk acquisition deals.
- Permission for Banks: Scheduled commercial banks (excluding RRBs) may be allowed to extend loans for corporate acquisitions, including mergers and buyouts.
- Scheduled commercial banks (excluding RRBs) may be allowed to extend loans for corporate acquisitions, including mergers and buyouts.
SEBI Considers Bringing Family Offices Under Regulatory
- Multi-Family Office (MFO): Offers services to multiple wealthy families, operating more like a financial advisory firm.
- Disclosure Requirements: Family offices may need to reveal their entities, assets, and investment returns for the first time.
- Family offices may need to reveal their entities, assets, and investment returns for the first time.
India Launches Foreign Currency Settlement System at GIFT IFSC
- Regulated Environment: Operates under the supervision of the International Financial Services Centres Authority (IFSCA).
Zoho Payments to Launch Physical POS Devices in India
- Receipts GenerationPrints or sends digital receipts to customers.
RBI Slaps Penalties on American Express and HDB Financial Services
- HDB Financial Services Ltd: Penalty: ₹4.2 lakh Violation: Breach of RBI’s Know Your Customer (KYC) Directions, 2016. Issue: Failed to obtain mandatory PAN or Form 60 for certain loan accounts.
- Credit Card and Debit Card – Issuance and Conduct Directions, 2022 Mandates timely refund/reversal of failed transactions and transparent customer communication.
- Penalty Framework under Banking Regulation Act, 1949 RBI can impose monetary penalties after inspection and due process (including show-cause notice and response evaluation).
- Penalty: ₹31.80 lakh
Bandhan Bank Integrates with Bharat Connect for Digital EMI Repayment
- Digital Channels: Customers can repay through: Bandhan Bank Mobile App (mBandhan) Retail Internet Banking (RIB) 700+ apps and websites connected via Bharat Connect.
- 700+ apps and websites connected via Bharat Connect.
- Financial Inclusion: The collaboration leverages Bharat Connect’s 5 million offline agents nationwide, improving accessibility to digital repayment channels.
- Bandhan Bank Mobile App (mBandhan)
RBI Holds Back Nationwide Launch of CBDC
- The Reserve Bank of India (RBI) has stated it is in no hurry to roll out the Central Bank Digital Currency (CBDC) nationwide for retail users, preferring to observe how other countries implement their digital currencies first. The announcement was made by Deputy Governor Rabi Sankar during the Global Fintech Fest 2025 in Mumbai.
- Learning from Others: The Bank intends to observe how other central banks — such as the People’s Bank of China (Digital Yuan) and European Central Bank (Digital Euro) — manage implementation challenges.
- The CBDC pilot project was launched by RBI in December 2022, beginning with wholesale and retail trials in select cities.
- It is broadly classified into: Retail CBDC (e₹-R): For individual consumers and merchants. Wholesale CBDC (e₹-W): For interbank and institutional settlements.
World Bank Upgrades India’s Growth Outlook to 6.5%
- The World Bank, in its South Asia Development Update (October 2025), has revised India’s GDP growth forecast upward to 6.5% for FY2025-26, up from the earlier 6.3%, citing strong domestic demand and the positive impact of GST rate cuts.
- Regional Outlook: South Asia’s growth projected to moderate from 6.6% (2025) to 5.8% (2026).
- Revised Projection: India’s growth for FY26 raised to 6.5% (from 6.3% earlier).
- FY27 Outlook: Trimmed to 6.3%, reflecting tariff uncertainties and weaker external demand.
RBI Proposes Granular Risk Weighting Norms for Bank Exposures
- ₹100 crore loan to a central government → Risk weight = 0% Bank need not keep any capital because sovereign debt is considered risk-free.
- ₹100 crore loan to a corporate → Risk weight = 100% Bank must keep capital against the full ₹100 crore exposure.
- Bank must keep capital against the full ₹100 crore exposure.
- For 0% risk weight → Required capital = 0
RBI Draft Frameworks on Bank Provisioning and Capital Requirements
- Implementation timeline: Begins April 1, 2027; banks get four years (till March 31, 2031) to make additional provisions on the existing book.
- On 7 October 2025, the Reserve Bank of India (RBI) released two important draft frameworks aimed at strengthening prudential regulation and improving credit risk management in banks:
- Frameworks are proposed to take effect from April 1, 2027.
- Transitional Adjustment: The difference between new ECL-based provisions and current provisions (as of March 31, 2027) will be added back to Common Equity Tier 1 (CET1) capital.
RBI Prioritises Use Cases Over Mass Rollout of Digital Rupee
- No Mass Rollout Yet:The e-rupee currently has around 7 million users.The RBI will wait for other countries to advance their own CBDC systems to ensure cross-border interoperability before scaling up.
- Mobile-Linked Wallet Payments:CBDC wallets can now be linked to mobile numbers, allowing users to make peer-to-peer payments without a bank account.
- Integrated CBDC Access Platform:A unified platform under NPCI allows users to access CBDC wallets across multiple banks in one place.
- Solar Credit Trading via e-Rupee:Retail users of solar rooftops can now trade energy credits directly through the e-rupee ecosystem.
SEBI to Review ‘Fit and Proper Person’ Rule
- The ‘fit and proper person’ framework was first introduced in 2004, and later subsumed under the SEBI (Intermediaries) Regulations, 2008.
- This development follows petitions filed in 2023 by leading brokerage firms, including Motilal Oswal Financial Services and Anand Rathi Shares and Stock Brokers, challenging the rule as unconstitutional.
- In November 2021, SEBI amended the regulations, introducing automatic trigger-based disqualifications in place of case-by-case assessments.
- The rule determines eligibility and integrity standards for entities and individuals associated with SEBI-regulated intermediaries such as brokers, mutual funds, investment advisers, and rating agencies.
RBI Draft Ombudsman Scheme 2025
- Comparison with current scheme: The Integrated Ombudsman Scheme currently has a dispute value limit of ₹50 lakh, which will be removed under the new draft.
- Compensation limits: Up to ₹30 lakh for consequential loss. Up to ₹3 lakh for harassment, time lost, or mental anguish.
- Up to ₹30 lakh for consequential loss.
- Up to ₹3 lakh for harassment, time lost, or mental anguish.
PhonePe and Utkarsh Small Finance Bank Launch “Wish Credit Card”
- Instant Digital Issuance: Customers can apply and get the card instantly through the PhonePe app with 100% digital onboarding.
- Objective:To expand credit inclusion by offering customised, flexible, and digital-first credit card solutions for both urban and semi-urban users.
- Digital payments platform PhonePe and Utkarsh Small Finance Bank (SFB) have jointly launched the “Wish Credit Card”, aimed at providing affordable and accessible credit to a wider section of users, especially those new to formal credit.
- Rewards and Cashback: Offers reward points and cashback on digital payments, shopping, and bill payments.
PayPal Launches “PayPal World” – Global Interoperable Wallet Platform
- At the Global Fintech Fest 2025 in Mumbai, PayPal CEO Alex Chriss announced the launch of “PayPal World”, a globally interoperable digital wallet platform that connects domestic digital wallets across countries. The platform’s first payments partner is India’s Unified Payments Interface (UPI).
Fino Payments Bank Settles SEBI Case for ₹5.8 Lakh
- Fino Payments Bank has settled a securities law violation case with the Securities and Exchange Board of India (SEBI) by paying a settlement amount of ₹5.8 lakh.
- Violation: Fino Payments Bank allegedly failed to promptly inform the stock exchanges about incidents of internal fraud — a material event that could impact investor decisions.
- Fino Payments Bank allegedly failed to promptly inform the stock exchanges about incidents of internal fraud — a material event that could impact investor decisions.
RBI Unveils Unified Markets Interface (UMI) to Tokenise Financial Assets
- Physical assets: Real estate, gold, or artwork can also be tokenised so that multiple investors can hold small digital shares of a high-value asset.
- At the Global Fintech Fest 2025, the Reserve Bank of India (RBI) announced the conceptualisation of a Unified Markets Interface (UMI) a new digital infrastructure aimed at tokenising financial assets and enabling settlements via wholesale Central Bank Digital Currency (CBDC). The initiative marks another milestone in India’s ongoing digital finance transformation.
PFRDA Plans to Expand Pension Coverage to Agriculture, SHGs, and Gig Workers
- Agriculture Sector: Collaborating with 50,000+ Farmer Producer Organisations (FPOs), each with 300–500 members, to provide pension coverage.
- The Pension Fund Regulatory and Development Authority (PFRDA) is targeting significant expansion of pension coverage in India, with a focus on underserved sectors such as agriculture, self-help groups (SHGs), and gig/platform workers. The announcement was made by PFRDA Chairman S. Ramann at the Global Fintech Fest 2025.
- Target Groups: Agriculture Sector: Collaborating with 50,000+ Farmer Producer Organisations (FPOs), each with 300–500 members, to provide pension coverage. Self-Help Groups (SHGs): Encouraging institutional savings and long-term financial planning. Gig/Platform Workers: Exploring schemes tailored for workers on digital platforms like Uber and Urban Company.
- Gig/Platform Workers: Exploring schemes tailored for workers on digital platforms like Uber and Urban Company.
RBI Launches Four New UPI Initiatives
- The Reserve Bank of India (RBI) launched four new digital payment initiatives at the Global Fintech Festival 2025, aimed at enhancing convenience, interoperability, and digital adoption in the UPI ecosystem.
- IoT-Based UPI Payments Enables payments through connected devices such as cars, smart TVs, smart glasses, and EV chargers. Expands UPI beyond smartphones, making transactions more seamless in the Internet-of-Things ecosystem.
- Enables payments through connected devices such as cars, smart TVs, smart glasses, and EV chargers.
- Banking Connect (Interoperable Net Banking Solution) Facilitates interoperability between banks and payment aggregators. Payment Aggregators (PAs) gain access to all participating banks via single integration, reducing technical complexity.
NPCI’s Credit Line on UPI (Clou)
- The National Payments Corporation of India (NPCI) launched Credit Line on UPI (Clou) in 2023 to make credit as frictionless as digital payments, enabling users to access a pre-approved credit line directly through their UPI app.
- A 1% increase in UPI transactions was associated with a 0.73% increase in credit.
- Research by the National Bureau of Economic Research (Shashwat Alok et al.) shows: Between 2015–2019, fintech loans in subprime/new-to-credit segments increased tenfold. A 1% increase in UPI transactions was associated with a 0.73% increase in credit. UPI-enabled digital footprints did not increase defaults, helping lenders identify creditworthy but underserved borrowers.
- Between 2015–2019, fintech loans in subprime/new-to-credit segments increased tenfold.
RBI Urges Inclusive & Innovative Fintechs to Leverage Digital Public Infrastructure
- At the Global Fintech Fest 2025, RBI Governor Sanjay Malhotra called on Indian fintechs to design inclusive, accessible, and innovative financial products, particularly for underserved populations such as senior citizens, individuals with limited digital literacy, and the specially-abled.
- Inclusivity and Accessibility Develop products that are easy-to-use and assistive for vulnerable groups. Ensure no segment is left behind even while serving affluent customers.
- Ensure no segment is left behind even while serving affluent customers.
- AI Integration AI will be integrated into DPI layers to improve user experience, efficiency, and conversational payment systems.
RBI Proposes Revision of Loan Risk Weights
| Loan Category | Key Changes / Criteria | Revised Risk Weight | Previous Risk Weight | Expected Impact / Rationale |
|---|---|---|---|---|
| 1. Credit Cards | • Transactors: Customers repaying dues in full for past 12 months classified under retail portfolio. • Other users: No change. | • Transactors: 75% • Others: 125% | 125% (uniform) | Encourages banks to acquire high-quality, low-risk customers. |
| 2. Home Loans | • Risk weight now linked to Loan-to-Value (LTV) and number of loans. • Up to 2 loans: 20% (LTV ≤50%) → 40% (LTV >80%). • Third loan: up to 60%, with 5% surcharge for loans above ₹3 crore. | 20%–60% (plus surcharge, where applicable) | 35%–50% (uniform earlier) | Introduces risk-based differentiation; supports competitive pricing while maintaining prudence. |
| 3. Personal Loans | Excludes housing, education, and vehicle loans. | 125% | 125% | Retained due to high-risk nature of unsecured credit. |
| 4. Corporate Loans | • BBB-rated: reduced to 75% • AA-rated: reduced to 20% • Unrated (>₹200 crore exposure): remains 150% | 20%–150% (based on rating) | 30%–150% | Improves capital efficiency for well-rated corporates, incentivising better-rated lending. |
| 5. MSME Lending & Real Estate | Risk weights linked to borrower risk profiles. | Not specified (dynamic) | Varied | Aims to improve capital allocation efficiency and align risk with borrower quality. |
RBI Digital Payments Initiatives
- Supported Devices: Cars, smart TVs, smart glasses, wearables.
- Functionality: Payments can be initiated using contextual triggers, routines, voice, or text commands. Works across devices or cloud environments within user-defined limits. Ideal for instant payments for fuel, EV charging, and other services.
- Payments can be initiated using contextual triggers, routines, voice, or text commands.
- Features: Enables seamless transactions across banks and payment aggregators. Standardizes merchant onboarding and simplifies digital payment integration.
Aditya Birla Capital Launches AI-Powered Personal Finance Assistant “SimpliFi”
- It offers 7 AI-powered features under the “MyTrack” section of the ABCD platform.
- 360° Protection Suite:Includes health-track tools, health-saver card, and benefits such as dental & eye check-ups, pharmacy discounts, and nutrition assistance. Also offers comprehensive personal insurance and a digital will for legacy planning.
- Aditya Birla Capital Ltd (ABCL), a leading diversified financial services group, has launched “SimpliFi”, an AI-powered personal finance assistant on its omnichannel D2C platform — ABCD, to enhance customer experience through personalized financial guidance.
- SimpliFi is an AI-driven personal finance assistant designed to help customers manage their finances more intelligently.
Gnani.ai Launches Self-Cloned Digital Human at Global Fintech Fest 2025
- At the Global Fintech Fest 2025, Gnani.ai, a leading Indian conversational AI company, unveiled a self-cloned Digital Human, marking a major leap in human–AI interaction. The innovation aims to humanize digital communication through realistic, multilingual avatars for financial and enterprise applications.
- Real-Time Expressive Avatars: Offers realistic lip-sync, micro-expressions, and gaze tracking for authentic engagement.
Razorpay, NPCI, and OpenAI Partner to Launch Agentic Payments on ChatGPT
- Banking Partners: Supported by Axis Bank and Airtel Payments Bank, leveraging UPI innovations like UPI Circle and UPI Reserve Pay.
- Feature: Agentic Payments allows users to shop and pay seamlessly within ChatGPT without leaving the chat interface.
- Pilot Launch: The feature is currently in its pilot phase, with early partnerships and limited access.
- Technology Base: Built on Razorpay’s payment infrastructure and integrated with ChatGPT’s conversational capabilities to facilitate AI-native UPI transactions.
RBI Governor Urges Fintechs to Drive Inclusive Growth Using India’s Digital Public Infrastructure
- Reserve Bank of India (RBI) Governor Sanjay Malhotra urged India’s fintech ecosystem to leverage the country’s Digital Public Infrastructure (DPI) to deliver responsible innovation, promote inclusion, and strengthen India’s journey toward becoming a developed nation by 2047.
| Theme | Key Points (Simplified) |
|---|---|
| Responsible & Inclusive Innovation | - Fintechs should make easy-to-use services, especially for seniors and people not familiar with digital tech. - Earn profits by reaching new users, not just richer or already-served people. - India has around 10,000 fintech companies innovating in payments, loans, and financial inclusion. |
| Extending Digital Public Infrastructure (DPI) Success | - Use the success of UPI (Unified Payments Interface) and AePS (Aadhaar Enabled Payment System) to provide loans to small businesses and individuals. - DPI has three layers: Identity (Aadhaar), Payments (UPI, AePS), Data (Account Aggregators). |
| RBI-Led Digital Infrastructure | - UMI (Unified Market Interface): Helps trade financial assets digitally and settle with CBDC (Central Bank Digital Currency). - ULI (Unified Lending Interface): Helps lenders use data to give loans to underserved people. |
| Account Aggregator (AA) Framework | - Lets users share financial data safely with permission. - 160 million accounts connected, 3.66 billion data requests processed. - Helps create credit history for people without formal loans. - RBI encourages all AA players to integrate more data and work together. |
| Synergy of UMI, ULI, AA | - Using these together, 3.2 million loans worth ₹1.7 trillion were given by 58 lenders. - Improves loans, money transfers, and trust in digital finance. |
| NPCI Digital Payment Innovations | - AI-based UPI HELP: Chatbot-like help for payments and complaints. - IoT Payments: Pay using smart devices (cars, TVs, watches). - Banking Connect: Easy onboarding and payment settlement for merchants. - UPI Reserve Pay: Block part of credit for recurring payments across apps. |
SEBI Reviewing Stock Lending and Borrowing Mechanism (SLBM)
- Supports hedging strategies for institutional investors.
- Provides extra income to long-term investors through lending fees.
RBI Lifts Ceiling on Loans Against Corporate Debt
- Bank Credit Against Shares: Loan limits for lending against shares increased from ₹20 lakh → ₹1 crore per person. IPO financing limits increased from ₹10 lakh → ₹25 lakh per person.
- Loan Limits Removed: Previously, banks could lend only up to ₹20 lakh against listed corporate debt securities. Now, there is no ceiling, enabling higher borrowing against these instruments.
- Previously, banks could lend only up to ₹20 lakh against listed corporate debt securities.
- Loan limits for lending against shares increased from ₹20 lakh → ₹1 crore per person.
HSBC India Launches ‘HSBC Innovation Banking’ Platform
- Full Name: The Hongkong and Shanghai Banking Corporation LimitedEstablished in India: 1853, as Mercantile Bank of India, London and ChinaAcquired by HSBC: 1959Headquarters: Mumbai, MaharashtraCEO (as of 2021): Hitendra Dave
- On October 9, 2025, HSBC India launched the “HSBC Innovation Banking” platform in Mumbai to support startups and the growing technology and venture ecosystem in India.
- Supports startup growth without diluting equity, allowing founders and investors to retain control.
Microfinance Loan Defaults Surge in FY 2024-25: Sa-Dhan Report
- Rising Delinquencies: Loans overdue more than 30 days (PAR 30+) rose to 6.2% in FY25 from 2.1% in FY24.
- Loans overdue more than 30 days (PAR 30+) rose to 6.2% in FY25 from 2.1% in FY24.
- Non-Performing Assets (NPAs): Loans overdue more than 90 days increased to 4.8%, up from 1.6% in FY24.
- Loans overdue more than 90 days increased to 4.8%, up from 1.6% in FY24.
RBI Suggests Overhaul of EPFO’s Investment and Accounting Framework
- EPFO’s Current Investment Pattern: 45–65% in Government Securities 20–45% in Debt Instruments 5–15% in Equities (via index funds) 0–5% in Short-Term Debt Instruments
- 5–15% in Equities (via index funds)
- EPFO manages over ₹25 trillion in retirement savings for nearly 300 million formal-sector workers, making it India’s largest retirement fund.
- 45–65% in Government Securities
RBI Consolidates 9,000 Regulatory Circulars into 238 Master Circulars
- Massive Consolidation Drive: The RBI will consolidate all regulatory instructions issued up to October 9, 2025, into 238 master circulars across 11 types of regulated entities and up to 30 regulatory areas.
- The RBI will consolidate all regulatory instructions issued up to October 9, 2025, into 238 master circulars across 11 types of regulated entities and up to 30 regulatory areas.
- 9,000 Circulars to be Repealed: Around 9,000 circulars currently administered by the Department of Regulation will be repealed as part of this exercise.
- Around 9,000 circulars currently administered by the Department of Regulation will be repealed as part of this exercise.
IRDAI Issues New Guidelines Mandating Board-Approved Anti-Fraud Policy for Insurers
- The Insurance Regulatory and Development Authority of India (IRDAI) has introduced the Insurance Fraud Monitoring Framework Guidelines, 2025, requiring all insurers to adopt a board-approved Anti-Fraud Policy to strengthen fraud prevention and risk management practices across the insurance sector.
- Insurers must constitute a Risk Management Committee responsible for implementing and overseeing the fraud risk management framework.
- Zero-Tolerance Policy for Fraud: Insurers must implement a comprehensive fraud risk management framework aimed at deterring, preventing, detecting, reporting, and remedying insurance frauds across all lines of business.
- Insurers must implement a comprehensive fraud risk management framework aimed at deterring, preventing, detecting, reporting, and remedying insurance frauds across all lines of business.
NPCI and PayPal Partner to Integrate UPI with Global PayPal World Platform
- Objective of Collaboration: The initiative aims to create a frictionless, seamless, and interoperable payments ecosystem allowing users and merchants across different countries to transact easily.
- The National Payments Corporation of India (NPCI) and PayPal announced a major global partnership to integrate India’s Unified Payments Interface (UPI) with PayPal World, a new interoperable platform connecting payment systems and digital wallets across countries. The announcement was made at the Global Fintech Fest 2025 in Mumbai.
- UPI Goes Global via PayPal World: India’s UPI will be the first instant payments platform to be integrated into PayPal World, marking a significant step toward global payment interoperability.
- India’s UPI will be the first instant payments platform to be integrated into PayPal World, marking a significant step toward global payment interoperability.
RBI Advisories and Public Communication (“RBI Kehta Hai”)
- Verified WhatsApp Accounts Official RBI numbers: 99990 41935 (already active) and 99309 91935 (being added). Only accounts with blue tick verification are official. Purpose: Deliver updates on policies, financial literacy, and public advisories.
- Official RBI numbers: 99990 41935 (already active) and 99309 91935 (being added).
- Use of Official Website Citizens are encouraged to refer to the RBI website for authentic circulars, press releases, and notifications.
- Citizens are encouraged to refer to the RBI website for authentic circulars, press releases, and notifications.
The Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015 (BMA)
- Under Section 72(c), the year the tax department discovers the asset is considered the year of income, bypassing usual time-barring provisions under the I-T Act.
- By contrast, under the I-T Act, the department can go back 5 years if escaped income ≥ ₹50 lakh, and 3 years if less.
- Heavy Tax & Penalties: 30% tax + 90% penalty on undisclosed foreign assets, totaling 120% of asset value, compared with 90% maximum under I-T Act.
- 30% tax + 90% penalty on undisclosed foreign assets, totaling 120% of asset value, compared with 90% maximum under I-T Act.
| Aspect | Details |
|---|---|
| Scope | Applies to income or assets held outside India by:- Indian residents- Citizens of India- Entities controlled by Indian residents |
| Taxation | Undisclosed foreign income/assets taxed at 30% plus applicable surcharge and cess. Additional penalties and prosecution may apply in serious cases. |
| Penalty | Penalty can be equal to tax payable on undisclosed foreign income/assets. Additional penalties may apply for concealment or failure to report. |
| Voluntary Disclosure / Compliance | Government provides Voluntary Disclosure Schemes (VDS) periodically:- Allows taxpayers to disclose undisclosed foreign income/assets- Pay tax and penalty- Avoid prosecution |
| Prosecution | Willful concealment or misreporting is a criminal offense:- Imprisonment: 3 to 10 years- Fines: As per the Act |
| Reporting Requirements | Individuals and entities must report foreign income and assets in annual income tax returns. Compliance is strictly enforced with cross-checking of foreign data. |
Banks Seek Exemption from SMS Alerts for Transactions Below ₹100
- Banks in India have requested the Reserve Bank of India (RBI) to allow exemption from sending SMS alerts for low-value transactions (below ₹100), citing growing digital transaction volumes and customer notification fatigue.
- Customers can register for email alerts, SMS costs (~₹0.20 per SMS) are typically passed to customers or borne by banks depending on account type.
- Reason for Request: Increased use of online payment channels, particularly UPI, has led to a surge in small-value transactions. Frequent SMS notifications create clutter and fatigue, sometimes causing customers to miss alerts for higher-value transactions.
- Frequent SMS notifications create clutter and fatigue, sometimes causing customers to miss alerts for higher-value transactions.
Foreign Banks Propose Policy Eases to RBI
- Governed under: Banking Regulation Act, 1949 Foreign Exchange Management Act (FEMA), 1999 RBI’s Master Directions for Foreign Banks
- Banking Regulation Act, 1949
- Foreign Exchange Management Act (FEMA), 1999
- Currently, unrated corporate loans above ₹200 crore attract a 150% risk weight, higher than rated corporates (30–100%).
EPFO to Adopt Separate Investment Benchmarks for Its Social Security Schemes
- 5–15% in equity markets via index funds
- Central Board of Trustees (CBT) to approve facility via India Post Payments Bank (IPPB) for ~8 million EPS pensioners.
- This comes after a Reserve Bank of India (RBI) suggestion to the Labour and Employment Ministry to review EPFO’s current approach of pooling all three schemes’ corpus (~₹25 trillion) with a common investment strategy, despite differing actuarial liabilities.
- 45–65% in government securities
IRDAI Mandates Fraud Risk Management Framework for Insurers
- The Insurance Regulatory & Development Authority of India (IRDAI) has directed all insurers, reinsurers, and distributing channels to establish a comprehensive fraud risk management framework. This comes in response to rising instances of insurance and cyber frauds. The guidelines are set to take effect from April 1, 2026.
- Zero Tolerance for Fraud: Insurance companies must adopt a board-approved anti-fraud policy. Policy should include red flag indicators and procedures to prevent, detect, report, and remedy fraud.
- Policy should include red flag indicators and procedures to prevent, detect, report, and remedy fraud.
- Cybersecurity Measures: Robust cybersecurity frameworks must be implemented to prevent new-age cyber frauds. Continuous monitoring and strengthening of incident databases, customer verification, and access control systems.
RBI Eases Expansion Norms for Payment Aggregators
- Scope of Expansion: Most fintechs start with a domestic PA license and later expand into PA-CB for cross-border payments. Compliance requirements for PA-CB are largely similar (≈80%) to a regular PA license.
- Compliance requirements for PA-CB are largely similar (≈80%) to a regular PA license.
- The Reserve Bank of India (RBI) has announced new guidelines allowing fully licensed payment aggregators (PAs) to expand into new segments, such as cross-border (CB) payments, with significantly streamlined approval processes.
- Fast-Track Expansion: Fully licensed PAs can now commence operations in a new PA category by simply notifying the RBI 30 days in advance, compared to nearly one year previously for separate approvals.
RBI Eases Transaction Compliance for EXIM Trade but Calls for Broader Reform
- AP (DIR Series) Circular No. 12, Oct 1, 2025 allows Authorised Dealer (AD) banks to reconcile and close entries in the Export Data Processing and Monitoring System (EDPMS) and Import Data Processing and Monitoring System (IDPMS) for bills valued ≤ ₹10 lakh.
- New: Foreign exchange outlay extended to 6 months, giving merchant traders additional operational flexibility.
- Reconciliation and Closure in EDPMS/IDPMS: AP (DIR Series) Circular No. 12, Oct 1, 2025 allows Authorised Dealer (AD) banks to reconcile and close entries in the Export Data Processing and Monitoring System (EDPMS) and Import Data Processing and Monitoring System (IDPMS) for bills valued ≤ ₹10 lakh. Closure can be based on a declaration from exporter/importer confirming realisation/payment. Quarterly consolidated submissions are permitted for bulk reconciliation. Helps address cases where payments are received/made through different AD banks or third parties.
- The Reserve Bank of India (RBI) recently introduced measures to simplify foreign exchange management and promote the use of the Indian Rupee (INR) in international trade, targeting exporters, importers, and merchant traders.
| Aspect | MTT (Merchanting Trade Transactions) | SRVA (Special Rupee Vostro Accounts) |
|---|---|---|
| Definition | International trade where an Indian merchant buys goods from one foreign country and sells to another, without goods entering India physically. | Accounts held by foreign partner banks in India in INR, used to settle trade in Indian Rupees. |
| Earlier Rule | - Transaction had to be completed within 9 months. - Foreign exchange outlay restricted to 4 months. | - Surplus balances could only be invested in government treasury bills or securities. |
| RBI 2025 Update | - Foreign exchange outlay extended to 6 months, giving more operational flexibility for merchant traders. | - Surplus balances can now also be invested in: • Non-convertible debentures (NCDs) • Corporate bonds • Commercial papers of Indian companies- Must follow existing investment guidelines and limits. |
SBI Cards & Payment Services: Impact of RBI’s Revised Credit Card Risk Weights
- All credit card dues (₹100) attract a uniform risk weight of 125%, leading to a capital requirement of ₹18.75 (CRAR of 15% applied to ₹125).
- Transactor dues risk weight: Reduced to 75% as they pose lower credit risk.
- Revolver dues risk weight: Remains 125%.
- Definition of transactors: Customers who fully paid their dues by the due date in the last 12 months.
| Aspect | Details / Observations |
|---|---|
| Stock Performance | - Up 40% in 2025.- CAGR since IPO (₹755 in March 2020 → ₹921.75) remains below 5%. - Volatility driven partly by high bad debts. |
| Credit Costs | - Gross credit cost: 6.7% (Q2 FY24) → 9.6% (Q1 FY26), except Q4 FY25. - Net credit cost: 5.5% → 8.5% sequentially. - Recoveries from past dues remain weak. |
| Preventive Measures | - Capping credit limits for existing customers. - Ensuring high quality of new card applicants. - Goal: Reduce delinquencies amid elevated household debt and leverage. |
| Capital Adequacy | - CRAR: 20.6% (Q1 FY25) → 23.2% (Q1 FY26).- Well above RBI’s minimum requirement of 15%, indicating capital is not a growth constraint. |
HDFC Bank Launches ‘My Business QR’ at GFF 2025
- Collaboration: HDFC Bank partnered with Vyaparify under the SmartHub Vyapar merchant app, which already serves 2 million+ merchants in India.
- Event: Global Fintech Fest 2025 (GFF 2025)Location: Mumbai, Maharashtra
- Initiative: ‘My Business QR’ – India’s first commerce identity QR solution for small businesses.
- Purpose: Helps retailers transition from offline to online, enhancing digital presence and commerce capabilities.
RBI Supersedes Board of Irinjalakuda Town Co-operative Bank
- RBI has superseded the Board of Directors of the bank for 12 months.
- Action taken under Section 36AAA read with Section 56 of the Banking Regulation Act, 1949.
- Purpose: Typically, such measures are taken to protect depositors’ interests, improve governance, and ensure financial stability of the bank.
SEBI Chief Urges Mutual Fund Trustees to Ensure Fair Fees and Stronger Oversight
- Fair Fees & Expenses: SEBI directed mutual fund trustees to ensure that fees and expenses charged to investors are fair, justified, and transparent.
- SEBI directed mutual fund trustees to ensure that fees and expenses charged to investors are fair, justified, and transparent.
- Who Are Mutual Fund Trustees? Mutual fund trustees are independent individuals or a board appointed to oversee a mutual fund’s operations, ensuring that it is managed fairly, transparently, and in compliance with regulations.
- Mutual fund trustees are independent individuals or a board appointed to oversee a mutual fund’s operations, ensuring that it is managed fairly, transparently, and in compliance with regulations.
Fraudbusters Digi Life: RBI’s AI Tool to Detect Fraud in Real Time
- Negative Registry (Phase 1): In its first phase, RBI has created a negative registry—a shared database that integrates data from telecom companies and the I4C to flag suspicious or fraudulent entities.
- In its first phase, RBI has created a negative registry—a shared database that integrates data from telecom companies and the I4C to flag suspicious or fraudulent entities.
- The Reserve Bank of India (RBI) is developing a next-generation Digital Payments Intelligence Platform (DPIP) to detect and prevent digital payment frauds in real time using Artificial Intelligence (AI). The initiative is being led through the RBI Innovation Hub, in collaboration with banks, telecom operators, and the Indian Cyber Crime Coordination Centre (I4C).
- Pilot Implementation: Initially, five banks were onboarded to the platform. It is now being expanded to include over a dozen lenders, enabling wider data sharing and detection efficiency.
Emirates NBD Bank in Talks to Acquire RBL Bank
- Founded in 1943, headquartered in Kolhapur, Maharashtra.
- Has a loan book of ₹6,568 crore (March 2025).
- RBI rules: No shareholder can normally vote with more than 26% stake, even if owning more.
- Operates 562 branches and has total business of ₹2.07 trillion.
RBI Allows Banks to Lend in Rupees to Bhutan, Nepal & Sri Lanka
- Earlier permission (Jan 2025): Exporters could open foreign currency accounts outside India to realise export proceeds. Unutilised balances must be repatriated by next month-end.
- Extended repatriation period: Foreign currency accounts in IFSCs (International Financial Services Centres) in India now have up to 3 months for repatriation. Encourages exporters to open accounts in IFSC units.
- On October 1, 2025, the Reserve Bank of India (RBI) allowed Indian banks and their overseas branches to lend in Indian Rupees (INR) to residents of Bhutan, Nepal, and Sri Lanka. These amendments are part of RBI’s efforts to ease external trade and payments, under the Foreign Exchange Management Act (FEMA).
- Foreign currency accounts in IFSCs (International Financial Services Centres) in India now have up to 3 months for repatriation.
UPI Goes PIN-Free with Biometric Authentication
- Every UPI transaction required entering a Personal Identification Number (PIN).
- Easier payments can democratise UPI, encouraging more users from rural and urban areas alike.
- Improves security and convenience for users.
Government’s Sovereign Gold Bond (SGB)
- Government discontinued SGB issuance from FY25. Last tranche issued in Feb 2024 at ₹6,263/g, and gold prices have nearly doubled since then.
- Investors can buy bonds instead of physical gold, earning 2.5% annual interest on the purchase price.
- Bonds mature in 8 years, with an option to redeem after 5 years.
- The sharp rise in gold prices over 35% in this financial year has seen the government’s outstanding debt on sovereign gold bonds (SGBs) spiralling to a record Rs 1.5 lakh crore.
RBI Issues Letter of Caution to Axis Bank for KYC Non-Compliance
- Axis Bank said it has received a "Letter of Caution" from the Reserve Bank of India's High-Level Committee for lapses related to KYC compliance in an account opened in 2009.
- Banks must verify the identity, address, and background of customers to prevent money laundering, fraud, and terrorist financing.
- RBI’s view: Bank has taken remedial actions and improved its systems, so a letter of caution is considered sufficient.
- RBI advised Axis Bank to exercise extreme caution and diligence to ensure strict compliance with KYC norms.
POSB and EPFO May Come Under RBI Oversight After Fraud and Fund Management Concerns
- POSB currently functions under the Ministry of Finance and falls under the Payment and Settlement Systems Act, 2007, already giving RBI partial authority over payment-related functions.
- Employees’ Provident Fund Organisation (EPFO): The Ministry of Labour sought RBI’s guidance on EPFO’s fund management and investment practices in February 2025. RBI’s Findings: Flagged accounting anomalies, including lack of mark-to-market valuation and absence of loss provisioning. Highlighted a conflict of interest between EPFO’s roles as regulator and fund manager. Recommended separation of regulatory and investment functions. Advised EPFO to conduct actuarial assessments and adopt a gradual diversification into equities and alternative assets.
- The Ministry of Labour sought RBI’s guidance on EPFO’s fund management and investment practices in February 2025.
- Post Office Savings Bank (POSB): Audit Findings: Over 60 cases of misappropriation across 14 postal circles revealed “manual manipulation” of the Sanchay Post database. The Department has proposed an MoU with RBI to review internal processes and strengthen fraud prevention mechanisms. POSB currently functions under the Ministry of Finance and falls under the Payment and Settlement Systems Act, 2007, already giving RBI partial authority over payment-related functions.
EPFO Proposes Major Simplification in PF Withdrawal Rules
- Digital Ease: Enables 100% auto-settlement for partial withdrawals without physical documents.
- Savings Discipline: Prevents premature depletion of retirement savings by mandating a 25% minimum balance.
- Simplification: Reduces administrative complexity by consolidating 13 withdrawal categories into 3.
| Aspect | Existing Rule | Proposed Change |
|---|---|---|
| Partial Withdrawals | 13 separate conditions with varying limits | Merged into 3 broad categories – (1) Personal milestones (marriage, illness, education), (2) Housing, and (3) Special circumstances |
| Frequency of Withdrawals | Combined limit of 3 for marriage & education | Up to 5 times for marriage and 10 times for education |
| Minimum Service Period | Varies by purpose | Standardised to 12 months |
| Minimum PF Balance | No such rule | Members must maintain 25% of contributions as minimum balance |
| Withdrawal Limit | Fixed per category | Up to 100% of eligible balance (after maintaining 25%) |
| Documentation | Documents required | Auto-settlement through simplified digital claim process |
| Full Settlement (Post-Resignation) | Allowed after 2 months | Waiting period increased to 12 months |
| Women Employees | Allowed early withdrawal under certain conditions | May continue under special circumstances |
| Employees’ Pension Scheme (EPS) | Withdrawal after 2 months | Waiting period extended to 36 months |
NTT Data Partners with NPCI International to Enable UPI Payments in Japan
- Objective: Enable Indian tourists in Japan to make payments using UPI, enhancing their shopping and payment experience.
Employees Enrolment Scheme, 2025 (EES 2025)
- Link to Other Schemes: Employers registering under EES 2025 or declaring additional employees become eligible for benefits under the Pradhan Mantri Viksit Bharat Rojgar Yojana, subject to its terms and conditions.
- Penal Damage: Employers opting for the scheme pay a nominal ₹100 lump sum penalty instead of standard non-compliance penalties.
- Scheme Period: 1 November 2025 to 30 April 2026.
- Eligibility: Employees who joined between 1 July 2017 and 31 October 2025, are alive and employed on the declaration date, and were not previously enrolled in the EPF scheme.
SEBI’s Relaxation of Minimum Public Shareholding
- Initial Public Offer (IPO) Requirement: Large companies can now list with as low as 2.5% public shareholding at the time of listing.
- Large companies can now list with as low as 2.5% public shareholding at the time of listing.
- Timeline to Achieve Full MPS: Companies have a 10-year period to reach the standard 25% MPS threshold, instead of meeting it immediately at listing.
- Companies have a 10-year period to reach the standard 25% MPS threshold, instead of meeting it immediately at listing.
IMF Raises India’s FY26 GDP Forecast to 6.6%
- Global Growth Outlook: The IMF raised the global growth projection for 2025 by 20 bps to 3.2%, while 2026 remains at 3.1%.
- External Factors: Despite trade challenges, including a 50% US tariff on labour-intensive exports (textiles, footwear, marine products), the Indian economy has shown resilience.
- Strong Domestic Momentum: Private sector growth and technology adoption remain key drivers of India’s economic expansion.
| Institution | Earlier | Current |
|---|---|---|
| World Bank | 6.3 | 6.5 |
| OECD | 6.3 | 6.7 |
| S&P Global | 6.5 | 6.5 |
| ADB | 6.5 | 6.5 |
| RBI | 6.5 | 6.8 |
| IMF | 6.4 | 6.6 |
Indian Banking Sector Attracts Significant Foreign Investments
- FDI in private banks is capped at 74%, with individual foreign financial entities limited to 15% without RBI approval.
- Foreign investors’ voting rights in private banks are capped at 26%, but the regulatory stance is becoming more supportive of larger foreign stakes, especially from countries with strong bilateral ties with India.
- Equity Investment / Stake Acquisition: Direct purchase of shares from promoters or private placements (e.g., SMBC in Yes Bank). Can be structured as preferential allotments, warrants, or secondary market purchases.
- Direct purchase of shares from promoters or private placements (e.g., SMBC in Yes Bank).
India’s First Wearables Payment Ecosystem – Muse & NPCI
- India’s first device-based wearables payment ecosystem, promoting contactless, secure, and convenient transactions.
Curie Money & ICICI Prudential AMC – Instant Mutual Fund Redemption via UPI
- Feature: Instant redemption up to 90% of invested liquid fund amount via UPI
- Daily Limit: ₹50,000
- Eliminates standard 1–2 business days waiting period for redemption.
- Empowers retail investors with flexibility and instant access to invested funds without penalties.
SEBI Extends Deadline for Angel Funds to Disclose Allocation Methodology in PPM
- Objective: Support innovation and entrepreneurship by funding high-growth potential startups.
- Regulation: Governed under SEBI (Alternative Investment Funds) Regulations, 2012.
- The Securities and Exchange Board of India (SEBI) has extended the deadline for angel funds to disclose their allocation methodology in the Private Placement Memorandum (PPM) to 31 January 2026. The earlier deadline was 15 October 2025.
- Objective: To provide ease of compliance and allow angel funds adequate time to align their documentation with SEBI’s requirements.
Bitcoin
- Launched in 2009, Bitcoin evolved from a niche digital payment tool to a globally traded asset.
- El Salvador became the first country to adopt Bitcoin as legal tender in 2021.
- 2025: The US established a Bitcoin reserve using seized tokens — the first formal recognition of Bitcoin as a reserve asset.
- 2013: RBI issued its first cautionary note on virtual currencies.
RBI Intervention Boosts Rupee to Biggest Single-Day Gain in Months
- RBI Action: The central bank conducted market operations to curb excessive volatility. Measures included buying/selling of dollars to maintain orderly movement and prevent abrupt depreciation.
- Measures included buying/selling of dollars to maintain orderly movement and prevent abrupt depreciation.
- Impact of Intervention: Stabilized the rupee against major currencies like the USD. Supported market confidence and helped prevent negative spillovers to trade and investment flows.
- Supported market confidence and helped prevent negative spillovers to trade and investment flows.
SEBI Cracks Down on Insider Trading in IEX
- SEBI (Prohibition of Insider Trading) Regulations, 2015: Defines insider trading and roles of insiders. Mandates disclosure of holdings and trades by promoters and directors. Prohibits trading based on UPSI. Regulates communication or procurement of UPSI.
- The Securities and Exchange Board of India (SEBI) barred eight individuals from the securities market and impounded ₹173.14 crore in alleged illegal gains from trades in Indian Energy Exchange (IEX).
- Buying or selling of securities by a person who has access to unpublished price-sensitive information (UPSI).
- Insider: Directors, officers, employees, or connected persons of a listed company.
Ageas Federal Life Partners with CSB Bank for SME Bancassurance
- Bancassurance is a collaboration between a bank and an insurance company where the bank sells the insurance company’s products to its customers.
- Customers: Bank clients who gain easier access to insurance coverage.
- Referral/Lead Generation Model: Bank refers customers to insurer; earns a referral fee.
- Bank refers customers to insurer; earns a referral fee.
Universal Sompo Partners with Andhra Pradesh Grameena Bank for Rural Insurance
- Universal Sompo General Insurance Company has partnered with Andhra Pradesh Grameena Bank (APGB) to provide a wide range of general insurance products across all 26 districts of Andhra Pradesh.
- Both organizations aim to offer customised and integrated financial and insurance solutions for farmers and rural enterprises.
Paytm Transfers Offline Merchant Payments to PPSL to Comply with RBI Guidelines
- RBI regulates Payment Aggregators under the Payment and Settlement Systems Act, 2007.
- Master Directions on Regulation of Payment Aggregators and Payment Gateways (issued 15 September 2025) define the rules.
- Objective: Avoid commingling of funds, improve oversight, and strengthen risk management.
- Capital Requirements Minimum net worth for a Payment Aggregator is ₹15 crore (for entities handling card/UPI/BBPS transactions).
RBI Introduces Reforms to Boost Cross-Border Trade
- Regulation: Foreign Exchange Management (Foreign Currency Accounts by a Person Resident in India) (Seventh Amendment) Regulations, 2025
- Regulation: Foreign Exchange Management (Borrowing and Lending) Regulations, 2018 – Amended in 2025
- Authorised Dealer (AD) banks in India and their overseas branches can now extend loans in Indian Rupees to persons or banks in Bhutan, Nepal, and Sri Lanka.
- Exporters with foreign currency accounts (FCA) in IFSC banks in India can retain export proceeds for up to three months before repatriation (earlier: next month).
Groww Launches Commodities Trading on Its Platform
- Others: Rubber, spices, palm oil.
- Investors can trade spot (cash) contracts for immediate delivery or futures contracts for delivery at a later date.
EPFO Reforms and RBI Recommendations – October 2025
- Premature Withdrawal: Members can withdraw up to 75% of PF for essential needs (illness, education, marriage), housing, and special circumstances; 25% retained for prudence.
- Frequency: Withdrawals for education – 10 times, marriage – 5 times. Minimum membership: 12 months.
- Unemployment Clause: Retained 25% can be accessed after 1 year of no pay.
- Current PF payouts (>8%) exceed returns on 10-year government bonds (~7%).
GIFT City Climbs to 43rd in Global Financial Centres Index 2025
- Asia-Pacific Trends: Six centres in the top 15, average rating increased by 1.27%. Beijing was the only city to see a decline.
- The 38th edition of the Global Financial Centres Index (GFCI 38) was released in October 2025 by the China Development Institute (Shenzhen) and Z/Yen Partners (London). GFCI evaluates 135 financial centres worldwide using 140 instrumental factors from organizations like the World Bank, OECD, and UN, along with 28,549 survey assessments.
- Rank: Improved from 46th to 43rd globally.
- FinTech Ranking: Rose from 40th to 35th, reflecting growing investor confidence in India’s IFSC.
LIC Launches Two New Insurance Products – Jan Suraksha and Bima Lakshmi
- Life Insurance Corporation of India (LIC) introduced two new insurance plans on 15 October 2025: LIC Jan Suraksha and LIC Bima Lakshmi. These are the first products launched under the next-gen GST regime.
- Age: 18–55 years
- Term: 12–20 years
- Premium Paying Term = Policy Term − 5 years
LIC Launches Jan Suraksha (880) & Bima Lakshmi (881) Plans
- Policy Term: 25 years
- Premium Paying Term: 5 years
- Entry Age: 18–55 years
- Minimum Sum Assured: ₹50,000
Lxme Launches India’s First Women UPI “Lxmepay”
- To address challenges such as overspending, losing track of expenses, and missing out on meaningful rewards.
- Digital Gold Rewards: Earn digital gold not only on spends but also when receiving money from other LxmePay users.
- Women-Centric Design: Features tailored to women’s unique financial behaviors, goals, and money management needs.
Bajaj Finserv AMC Introduces ‘Pay with Mutual Fund’ Feature
- Redemption Limit: Investors can redeem up to ₹50,000 or 90% of their investment, whichever is lower, under the Insta Redemption facility.
- Collaboration: Developed in partnership with Curie Money, a fintech platform ensuring seamless transaction processing.
- Instant Access via UPI: Payments can be made by scanning a QR code, triggering an automatic redemption from the mutual fund to the bank account in the background.
RBI's Application Tracking System (ATS)
- The Application Tracking System (ATS) is an online platform hosted on the RBI website for members of the public to submit applications to any department of the Reserve Bank of India and track their status until disposal.
- Registration: First-time users register with a valid email ID; system generates a password.
- Attachment Support: Documents can be uploaded with each application (max size 1 MB each).
- Tracking Physical Submissions: Applications submitted at RBI counters or via post/courier can also be tracked if a valid email ID is provided.
Indian Economy Shows Resilience Amid Global Challenges: RBI Report
- The report notes that real GDP growth remains above 7%, driven by urban demand, infrastructure spending, and service sector expansion.
- Economic Growth: India continues to be one of the fastest-growing major economies, supported by a revival in private consumption and public investment. The report notes that real GDP growth remains above 7%, driven by urban demand, infrastructure spending, and service sector expansion.
- Structural Strengths: The report underscores the impact of digitalization, fiscal prudence, and supply-side reforms in bolstering the economy’s medium-term prospects.
- The report underscores the impact of digitalization, fiscal prudence, and supply-side reforms in bolstering the economy’s medium-term prospects.
RBI May Ease Approval Norms for Banks to Float Subsidiaries
- Legal Basis: Section 6 of the Banking Regulation Act, 1949, specifies permissible non-core banking businesses.
- Objective: To enhance operational flexibility for banks and reduce regulatory bottlenecks.
- Promotes segmented diversification in financial services.
- Segmentation Rule: RBI will propose that subsidiaries should operate in segments distinct from their parent banks (e.g., if a bank provides housing loans, its subsidiary may focus on affordable housing finance).
RBI Pushes to Expand Rupee Settlements with Trade Partners
- The effort supports the Rupee Trade Settlement System (RTS) introduced in July 2022, allowing foreign trade invoicing and payments in Indian rupees.
- To support India’s ambition of becoming a global economic powerhouse by 2047.
- The Reserve Bank of India (RBI) is taking steps to expand rupee-based trade settlement mechanisms with major trading partners to promote rupee internationalisation and reduce dependence on the US dollar.
- The new reference rate framework will extend to currencies of trade partners in the Gulf, ASEAN region, and Mauritius.
GSTR-3B
- What it is: A monthly self-declaration form through which registered GST taxpayers report summary details of outward and inward supplies, input tax credit (ITC), and tax liability.
- The Central Board of Indirect Taxes and Customs (CBIC) has extended the deadline for filing the GSTR-3B return for certain taxpayers, in view of the Deepavali festival.
- The CBIC issued a notification extending the deadline for GSTR-3B, the monthly summary return under the Goods and Services Tax (GST) regime.
- The extension applies to taxpayers registered in specific states and Union Territories where Deepavali festivities may affect timely filing.
SEBI Proposes Relaxation for Transfer of Pre-2019 Securities
- Simplify the demat process for security transactions executed before April 2019.
- SEBI discontinued transfer of physical securities from April 1, 2019, to encourage full dematerialisation.
- The Securities and Exchange Board of India (SEBI) has proposed amendments to the Listing Obligations and Disclosure Requirements (LODR) Regulations, 2015, aimed at facilitating the transfer and dematerialisation of securities executed before April 1, 2019. This move seeks to provide relief to investors who missed earlier deadlines for regularising such holdings.
- Provide one more opportunity for investors to re-lodge transfer deeds for physical securities.
Unclaimed Shares Portal Set for Major Upgrade
- The Investor Education and Protection Fund Authority (IEPFA) under the Ministry of Corporate Affairs is planning to upgrade the integrated unclaimed shares and dividends portal to accelerate claim settlements and improve investor convenience.
- The upgraded portal, termed Integrated Portal 2.0, will leverage artificial intelligence (AI) and data analytics to expedite claim verification and reduce settlement time to about 15 days.
- Target Settlement: Claims to be processed within 15 days.
- Mobile App: Investors will be able to apply and track claim status via an app.
RBI’s Expected Credit Loss (ECL) Model
- Alignment with Global Standards: Consistent with IFRS 9 and Basel III guidelines for credit risk provisioning.
- Key Features: Provisions are based on probability of default (PD), exposure at default (EAD), and loss given default (LGD). Requires banks to continuously monitor and update credit risk parameters. Enhances capital adequacy and financial stability.
- Requires banks to continuously monitor and update credit risk parameters.
- Resilient Banking System: Strengthens buffers against economic shocks.
India Records Net FDI Outflow in August 2025
- The Reserve Bank of India (RBI) reported a 159% decline in net Foreign Direct Investment (FDI) in August 2025, indicating that more money left India than entered it. This marks the second time in FY26 that outflows have exceeded inflows, signaling volatility in foreign investment trends.
- Gross Inflows: Total money invested by foreign investors in India.
- Geopolitical and Economic Uncertainty: Investors shifting capital to safer markets.
- Corporate Restructuring: Indian firms investing abroad for diversification.
New Tax Rules on Share Buybacks
- Buyback Tax: Companies were liable to pay a 20% tax (plus surcharge and cess) on the distributed income from share buybacks under Section 115QA of the Income Tax Act.
- Governed under Section 68–70 of the Companies Act, 2013 and SEBI (Buyback of Securities) Regulations, 2018 (for listed companies).
- Tax Shift: The 20% buyback tax on companies has been abolished. The entire buyback amount is now taxable as dividend income in the hands of shareholders.
- The 20% buyback tax on companies has been abolished.
PFRDA Releases Draft Framework on Pension Wealth Accumulations
- Established: 2003 | Statutory Authority: Since 2013 (PFRDA Act, 2013)
- Headquarters: New Delhi
- Stable Wealth Depiction: To provide subscribers with a more stable and simplified picture of their pension wealth accumulation during the contribution phase.
- To provide subscribers with a more stable and simplified picture of their pension wealth accumulation during the contribution phase.
RBI Study Flags Overvaluation Risks in SME IPO Segment
- Overvaluation Signals: The study compared price-to-earnings (P/E) ratios of 100 SMEs listed in FY24–FY25 with their respective industry averages. Around 20% of these stocks had excessive P/E multiples, suggesting overvaluation relative to peers.
- Around 20% of these stocks had excessive P/E multiples, suggesting overvaluation relative to peers.
- Dominance of Fresh Capital Issues: In FY24, fresh capital accounted for 94.8% of total issue size. In FY25, it was 91.5%, showing that companies are raising funds for expansion rather than providing exits to existing shareholders.
- In FY24, fresh capital accounted for 94.8% of total issue size.
Indian Banks’ Profitability and NIM Improvement Amid RBI Rate-Cut Cycle
- Sectoral Performance: Private sector banks continue to maintain higher NIMs compared to public sector peers, supported by better credit appraisal systems and diversified loan books.
SEBI Tightens Insider Trading Oversight as Unlawful Gains Surge
- Key Action: The regulator impounded over ₹173 crore of unlawful gains, marking one of the largest insider trading crackdowns in recent years.
- Governed under SEBI (Prohibition of Insider Trading) Regulations, 2015.
PFRDA Proposes Dual Valuation Framework for NPS and APY Portfolios
- Objective of the Framework: To present pension wealth accumulation more clearly to subscribers. To ensure long-term financial stability and reflect the true economic purpose of pension investments. To align pension fund investments with long-term capital formation—especially in funding productive infrastructure assets with long gestation periods.
- To present pension wealth accumulation more clearly to subscribers.
RBI Launches Offline Digital Rupee (e₹) at Global Fintech Fest 2025
- Pilot & Adoption: India’s first retail e-rupee pilot started on December 1, 2022. Over 7 million users have participated so far.
- India’s first retail e-rupee pilot started on December 1, 2022.
- Availability: Wallet apps available on Google Play and Apple App Store. Supports instant person-to-person (P2P) and person-to-merchant (P2M) transactions.
- Supports instant person-to-person (P2P) and person-to-merchant (P2M) transactions.
WACR Now Better Aligned with Repo Rate: RBI Report
- Early October: As liquidity improved, the WACR fell below the repo rate, prompting the RBI to conduct two Variable Rate Reverse Repo (VRRR) auctions (on October 9 and 15) to absorb excess liquidity.
- The risk premium — defined as the spread between 3-month CP and 91-day T-Bill yields — widened, indicating rising credit risk perceptions or selective risk pricing by investors.
- This alignment suggests effective monetary transmission under the revised liquidity management framework introduced on September 30, 2025.
- The Reserve Bank of India (RBI) has noted that the Weighted Average Call Rate (WACR) showed improved alignment with the policy repo rate during the period September 16–October 16, according to its State of the Economy report released on Monday.
| Feature | WACR | SORR |
|---|---|---|
| Type of Market | Uncollateralised (Call Money Market) | Collateralised (Repo Market) |
| Security | No collateral | Backed by government securities |
| Administered by | RBI | FBIL |
| Use | Operating target of monetary policy | Benchmark reference rate |
| Risk Level | Higher (credit risk involved) | Lower (secured by collateral) |
Mutual Funds Seek Wider Operational Flexibility from SEBI
- Permitting AMCs to act as global distributors for funds managed by themselves or their subsidiaries, under strict regulatory oversight.
- Easing restrictions on AMC mergers and acquisitions (M&A).
- In July 2025, SEBI released a consultation paper proposing limited relaxations under Regulation 24(b). The proposals included:
RBI Allows Banks to Cut Home Loan Spreads for Existing Borrowers
- The spread reflected factors such as the borrower’s credit score, loan tenure, and the bank’s margin.
- This means that if your credit score improves, or your risk profile becomes stronger, your bank can lower your loan rate without waiting for three years.
- Banks were not allowed to alter the non-credit-risk component of the spread for three years after sanction — even if the borrower’s creditworthiness improved.
- As a result, new borrowers often enjoyed lower rates, while existing borrowers remained stuck with higher EMIs.
Banking Laws (Amendment) Act, 2025
- The Finance Ministry has announced that key provisions related to nomination under the Banking Laws (Amendment) Act, 2025 will come into effect from November 1, 2025. These measures are designed to enhance flexibility, transparency, and efficiency in claim settlements for depositors.
- Deposit Accounts: Depositors can make nominations for their bank deposits according to their preference.
- Safe Custody Articles & Lockers: Nomination facilities extend to articles kept in safe custody and contents of safety lockers maintained with banks.
- Relevant Sections: Provisions being implemented through Sections 10, 11, 12, and 13 of the amended Banking Laws.
RBI Proposes to Mandate Unique Transaction Identifier (UTI) for All OTC Derivative Transactions
- The RBI has invited comments from banks, market participants and other stakeholders by 14 November 2025.
- Format: A maximum of 52 characters, comprising the LEI of the generating entity plus a unique identifier for that transaction.
- UTIs are viewed globally as a key data element for reporting OTC derivatives, helping regulators and policymakers aggregate, analyse and monitor risks in the derivatives markets.
| Term | Meaning | Purpose | Example |
|---|---|---|---|
| UTI | A unique alphanumeric code assigned to each derivative transaction | To ensure consistent reporting and tracking | A code like “INRFX20251023001” assigned to an FX swap |
| OTC Derivative | A privately negotiated financial contract between two parties | To manage risk or speculate without using exchanges | Two banks agree on an interest rate swap |
SEBI (Merchant Bankers) Regulations
- Merchant bankers are bound by the SEBI (Merchant Bankers) Regulations, 1992, which require strict adherence to norms on net worth, underwriting exposure, disclosure compliance, and scope of business.
- The Securities and Exchange Board of India (SEBI) introduced the Merchant Bankers Regulations, 1992 to regulate the operations of merchant bankers in India. These regulations ensure transparency, accountability, and professionalism in capital market intermediation, especially in issue management, underwriting, and corporate advisory services.
| Provision | Regulation Reference | Key Requirements / Highlights |
|---|---|---|
| 1. Registration Requirement | Reg. 3–6 | • Must obtain SEBI registration before business commencement. • Must have adequate infrastructure, qualified personnel, and financial soundness. • SEBI may reject/suspend registration for non-compliance or misconduct. |
| 2. Capital Adequacy Norms | — | • Minimum net worth: ₹5 crore (latest amendment). • Net worth = Paid-up capital + Free reserves (excluding revaluation reserves). • Non-compliance can lead to suspension/cancellation. |
| 3. Code of Conduct | Schedule III | • Maintain integrity, fairness, and diligence. • Avoid conflicts of interest. • Ensure full and fair disclosure to investors. • Maintain confidentiality and act in clients’ best interests. |
| 4. Underwriting & Issue Management | Reg. 13–16 | • Must sign formal agreement with issuer. • Conduct due diligence on disclosures. • Underwriting within financial capacity (linked to net worth). • Submit due diligence certificate to SEBI before issue opens. |
| 5. Books of Accounts & Records | Reg. 29 | • Maintain books, client agreements, reports, and correspondence for minimum 5 years. • Must be available for SEBI inspection. |
| 6. Half-Yearly Reporting | Reg. 32 | • Submit half-yearly activity and compliance reports to SEBI. • Delay or non-submission may attract penalties or suspension. |
| 7. Prohibition on Non-Securities Business | Reg. 24(b) | • Cannot engage in unrelated businesses (e.g., real estate, property, or trade). • SEBI may permit related activities (like portfolio/advisory services) with prior approval. |
RBI Payments System Report 2025
- Remittances: India remains the largest recipient globally, with $137.7 billion inflows in 2024, more than double Mexico ($67.6 billion). The Kuwait-India corridor is the most cost-efficient at 2.10%, below the UN SDG target of 3%.
- UPI-FPS Integration: Operationalised linking of UPI (India) with PayNow (Singapore) in 2023.
- Operational Barriers: Multiple intermediaries, fragmented data standards, compliance checks, and legacy platforms increase transaction costs and reduce efficiency, particularly for individuals and SMEs.
- Payments Regulatory Board (PRB): Replaced the BPSS; chaired by RBI Governor; oversees regulation and supervision of payment systems.
Microfinance Institutions (MFIs)
- Key measures include: Capping the number of lenders per borrower at three (effective April 1, 2025). Monitoring outstanding loans to prevent excessive indebtedness.
- Capping the number of lenders per borrower at three (effective April 1, 2025).
- Established to promote responsible lending practices, transparency, and financial inclusion, MFIN acts as a bridge between the microfinance industry and regulatory authorities like the Reserve Bank of India (RBI).
- Industry Representation: Represents the interests of member microfinance institutions (MFIs) to regulators, policymakers, and other stakeholders.
New Bank Nomination Rules 2025
- The Banking Laws (Amendment) Act, 2025 was notified on April 15, 2025.
- It includes 19 amendments across five key legislations: Reserve Bank of India Act, 1934 Banking Regulation Act, 1949 State Bank of India Act, 1955 Banking Companies (Acquisition and Transfer of Undertakings) Acts, 1970 and 1980
- Reserve Bank of India Act, 1934
- Banking Regulation Act, 1949
SEBI Proposes Easing Geo-Tagging Requirement for NRIs in KYC
- Purpose: Simplifies compliance for overseas investors. Follows multiple stakeholder representations seeking streamlined KYC procedures.
- Simplifies compliance for overseas investors.
- Reduces compliance burden for NRI investors.
- Facilitates ease of investment from abroad while maintaining regulatory oversight.
Government Securities (G-Sec)
- Government Bonds / Dated Securities: Long-term securities with maturities ranging from 5 to 40 years. Pay periodic interest (coupon) at fixed or floating rates.
- Long-term securities with maturities ranging from 5 to 40 years.
- Treasury Bills (T-Bills): Short-term securities with maturities of less than one year (commonly 91 days, 182 days, and 364 days). Issued at a discount and redeemed at face value (zero-coupon instrument).
- Short-term securities with maturities of less than one year (commonly 91 days, 182 days, and 364 days).
RBI Gold Reserves
- Recent addition: 0.2 tonnes added in the last week of September 2025
- India’s Monetary Strategy: Gold reserves complement foreign currency reserves, providing diversification and reducing dependence on the US dollar. Acts as a financial buffer for the Reserve Bank of India to stabilize the economy during crises.
- In the six months ended September 2025, RBI added 0.6 tonnes, showing a gradual accumulation strategy rather than large, sporadic purchases.
- Total gold reserves: 880 tonnes
RBI Proposes New Norms to Allow Banks to Fund Corporate Acquisitions
- Exposure Cap: The aggregate exposure of a bank towards acquisition finance cannot exceed 10% of its Tier-I capital.
- Funding Limit: Banks can fund up to 70% of the acquisition value, with at least 30% financed by the acquiring company’s own equity contribution.
- Implementation Date: The proposed norms will come into effect from April 1, 2026.
- Eligibility: Only listed Indian companies with a satisfactory net worth and profitable operations for the past three years can access such financing.
RBI Proposes Cap on Banks’ Capital Market and Acquisition Financing Exposure
- Aggregate Cap: The total direct exposure of banks to capital markets and acquisition financing will be capped at 20% of their Tier-1 capital.
- The total direct exposure of banks to capital markets and acquisition financing will be capped at 20% of their Tier-1 capital.
- Sub-limits: Capital Market Exposure: Cannot exceed 40% of Tier-1 capital, including loans, guarantees, and fund-based exposures. Acquisition Financing: Restricted to 10% of Tier-1 capital to prevent overleveraging in corporate takeovers.
- Capital Market Exposure: Cannot exceed 40% of Tier-1 capital, including loans, guarantees, and fund-based exposures.
SEBI Restricts Mutual Funds from Participating in Pre-IPO Placements
- Regulatory Clarification: SEBI stated that mutual funds can invest in unlisted shares only as anchor investors — that is, a day before an IPO opens to the public.
- SEBI stated that mutual funds can invest in unlisted shares only as anchor investors — that is, a day before an IPO opens to the public.
Simplified GST Registration under GST 2.0
- Eligibility for Automatic Registration: Applicants identified as low-risk by the system based on data analytics. Taxpayers self-assessing that their monthly output tax liability does not exceed ₹2.5 lakh.
- Taxpayers self-assessing that their monthly output tax liability does not exceed ₹2.5 lakh.
- Coverage: Nearly 96% of new applicants are expected to benefit from this simplified system.
- Objective: To ease compliance, enhance efficiency, and ensure transparency by limiting discretionary approvals.
RBI Proposes Lower Risk Weights for NBFC Loans to High-Quality Infrastructure Projects
- Policy Context: The proposal aligns with the RBI’s announcement during the Monetary Policy Committee (MPC) meeting earlier in 2025 to rationalize capital adequacy norms for NBFCs. NBFCs are already permitted to assign lower risk weights for operational Public-Private Partnership (PPP) projects. This framework extends the benefit to other operational infrastructure projects that meet defined quality standards.
- The proposal aligns with the RBI’s announcement during the Monetary Policy Committee (MPC) meeting earlier in 2025 to rationalize capital adequacy norms for NBFCs.
- Lower Risk Weights Proposed: Loans where the borrower has repaid at least 10% of the sanctioned amount → 50% risk weight (reduced from 100%). Loans where the borrower has repaid between 5% and 10% of the sanctioned amount → 75% risk weight.
- Loans where the borrower has repaid at least 10% of the sanctioned amount → 50% risk weight (reduced from 100%).
RBI Exempts Swamih Fund from Tightened AIF Rules
- Established: 2019
- Objective: Provide debt financing to affordable and mid-income housing projects that have stalled due to financial difficulties
- This facilitates greater investment in stalled real estate projects, enabling faster project completion and mitigating losses for homebuyers and developers.
- Managed by: SBICAP Ventures, a subsidiary of the State Bank of India
SBI and BoB to Lead Digital Payments Intelligence Body to Curb Fraud
- Authorized Capital: ₹500 crore
- Paid-Up Capital: ₹200 crore
- Initial Funding: SBI and BoB to contribute ₹10 crore each
- Legal Structure: Section 8 company (non-profit)
RBI Proposes Higher Loan-to-Value Limits for Loans Against Shares and Debt Mutual Funds
- For Shares: Increased from 50% to 60%.
- For Debt Mutual Funds (MFs): Increased from 50% to 75%.
- Maximum loan amount: Increased fivefold — from ₹20 lakh to ₹1 crore per individual.
- Loan for acquisition of securities in secondary markets: Capped at ₹25 lakh per individual.
PMS Transfer Between Managers Gets SEBI Nod
- Minimum Investment: ₹50 lakh (as per SEBI regulations).
- 2. Intra-Group Transfers
- 3. Inter-Group Transfers
- Portfolio managers can transfer their PMS business, either partially (specific investment approaches) or completely, to another manager after obtaining SEBI’s prior approval.
India’s Forex Reserves Cross $700 Billion for the First Time
- The Reserve Bank of India (RBI) reported that total forex reserves surged by $8.5 billion, crossing $700 billion.
- Definition: External assets held by the central bank in the form of foreign currencies, gold, Special Drawing Rights (SDRs), and IMF reserve positions.
- India’s foreign exchange reserves have touched a new milestone, crossing the $700 billion mark for the first time. The jump was mainly driven by an increase in gold reserves, boosted by both RBI’s purchases and a rise in global gold prices.
- Gold reserves rose sharply to over $60 billion, reflecting higher global prices and fresh RBI acquisitions.
Government Clarifies LIC’s Investment Autonomy
- Founded: 1956 (through nationalisation of life insurers)
- Headquarters: Mumbai, Maharashtra
- Assets under Management (AUM): Over ₹55 lakh crore
- Listed: 2022 on BSE and NSE
MCX Launches Options Trading on Bullion Index ‘Bulldex’ Amid Gold-Silver Price Volatility
- Launch Date: Monday, with contracts expiring in November, December, and January 2026 available initially.
- Existing Framework: MCX, launched Bulldex futures in August 2020, and is now expanding the product suite to include options contracts for greater hedging flexibility and participation.
- The financial instrument on which the option is based — for example, Nifty 50, Bank Nifty, or a specific stock like Reliance or Infosys.
- Call Option (CE):Gives the holder the right to buy the underlying asset at a fixed price before expiry. Traders buy calls if they expect prices to rise.
Parametric Insurance
- Existing Scheme: Pradhan Mantri Fasal Bima Yojana (PMFBY), launched in 2016, replaced NAIS and MNAIS.
- Employment and GDP: Agriculture employs nearly 50% of India’s population and contributes about 18% to GDP.
- Smallholder Dominance: Around 86% of Indian farmers are smallholders, managing limited landholdings and depending heavily on monsoons.
- Transparency: Objective, data-based triggers reduce disputes and delays.
SEBI Proposes Easing Compliance for High Value Debt-Listed Entities
- Threshold: ₹1,000 crore or more in outstanding listed NCDs
- Proposal: Increase the threshold from ₹1,000 crore to ₹5,000 crore.
- Impact: Reduce HVDLEs from 137 to 48 entities, lowering the count by around 64%.
- Objective: Ease compliance for smaller issuers and frequent debt-raising NBFCs.
| Area | Proposed Change |
|---|---|
| Definition of Material Subsidiary | Replace the term “income” with “turnover” for uniformity with equity-listed rules. |
| Age Limit for Directors | Require special shareholder approval if a director is aged above 75 years. |
| Nominee Directors | Exempt directors appointed by courts, tribunals, or regulators from needing shareholder approval. |
| Board Recommendations | Boards must provide a rationale for all recommendations made to shareholders. |
| Vacancies in Key Committees | Allow 3 months to fill vacancies in Audit, NRC, Stakeholders, and Risk Committees. |
| Independent Director Vacancy | Remove the 3-month mandatory filling requirement if minimum board composition is maintained. |
| Intra-Group Transfers | Exempt shareholder approval for intra-group asset transfers between subsidiaries. |
| CIRP-Related Companies | Give 3 months post-resolution to fill Key Managerial Positions (KMPs). |
| Compliance Reports | Replace fixed 21-day filing deadline with a flexible, SEBI-prescribed timeline. |
| Related Party Transactions (RPTs) | Exclude RPT disclosures from periodic reports (already covered in half-yearly filings). |
| Secretarial Auditors | Introduce clear provisions on appointment, reappointment, and removal of secretarial auditors. |
| Debenture Trustees’ Role | Retain the requirement for NOCs from debenture trustees and debenture holders for RPTs. |
RBI’s 30th Standing Advisory Committee Meeting on MSME Credit Flow
- Objective: To provide greater financial flexibility and reduce the cost of credit for small borrowers.
- The 30th meeting of the Standing Advisory Committee (SAC) to review the flow of credit to the Micro, Small and Medium Enterprises (MSME) sector was held in Coimbatore, chaired by RBI Deputy Governor Swaminathan J.
Banks Prefer Direct Assignment Over Co-Lending
- Co-Lending: Banks and NBFCs jointly lend to borrowers, sharing risk and returns. Complexity has increased due to RBI’s new rules (15-day assignment window, tech integration requirements).
- Direct Assignment (DA): Transfer of loans from NBFCs to banks without SPV; bank assumes ownership and repayment rights.
- Advantages: Banks acquire ownership and the right to receive borrower payments. Allows banks to free up capital for NBFCs. Enables banks to cherry-pick high-quality loans. Helps meet priority-sector lending targets.
- Banks acquire ownership and the right to receive borrower payments.
Gaja Capital Set to Become India’s First Private Equity (PE) Firm
- Long-Term Investment Horizon:Typically 5–10 years, focusing on business growth, restructuring, or turnaround.
- Regulated by the Securities and Exchange Board of India (SEBI) under the Alternative Investment Funds (AIF) Regulations, 2012.
- Capital Source:PE firms raise funds from institutional investors (pension funds, insurance companies, sovereign wealth funds) and high-net-worth individuals (HNIs).
- Ownership:They usually acquire significant or controlling stakes in target companies, influencing strategy and management decisions.
| Type | Description |
|---|---|
| Venture Capital (VC) | Early-stage funding for startups with high growth potential. |
| Growth Capital | Funding for mature companies looking to expand or enter new markets. |
| Buyout / Leveraged Buyout (LBO) | Acquisition of majority control, often financed through debt. |
| Distressed / Turnaround | Investment in struggling companies for restructuring and revival. |
| Fund of Funds (FoF) | Investment in other PE or VC funds rather than direct companies. |
SEBI Proposes Incentives to Boost Retail Participation in Corporate Bonds
- Historical Context: In 2024, SEBI allowed discounts for retail investors in Offers for Sale (OFS), showing precedent for incentivization.
- In 2024, SEBI allowed discounts for retail investors in Offers for Sale (OFS), showing precedent for incentivization.
- Proposal Details: Issuers may provide incentives such as: Higher coupon rates Discounts on issue price Targeted investor groups: Senior citizens Women investors Armed forces personnel Retail subscribers
- Issuers may provide incentives such as: Higher coupon rates Discounts on issue price
SEBI Proposes Tighter KYC for Mutual Fund Investors
- Industry & Government Initiatives: Central KYC Registry: Managed by CERSAI, intended to unify KYC across banks, MFs, insurance, and pensions; expected launch March 2026. Mutual fund assets as of September 2025: ₹75.61 trillion (up ₹8.5 trillion YoY).
- Central KYC Registry: Managed by CERSAI, intended to unify KYC across banks, MFs, insurance, and pensions; expected launch March 2026.
- Mutual fund assets as of September 2025: ₹75.61 trillion (up ₹8.5 trillion YoY).
- Proposed KYC Norms: First-time investments or new folios will be accepted only after the investor’s KYC is fully verified and marked “compliant” by the KYC Registration Agency (KRA). Aim: Prevent unclaimed dividends and blocked redemptions.
VFS Capital Withdraws Small Finance Bank Licence Application
- Key Features: Must be registered as a public limited company under the Companies Act, 2013. Minimum paid-up capital: ₹200 crore. Must maintain 75% of Adjusted Net Bank Credit (ANBC) for priority sector lending. At least 50% of loans should be up to ₹25 lakh.
- Founded: 1995
- Must maintain 75% of Adjusted Net Bank Credit (ANBC) for priority sector lending.
- Must be registered as a public limited company under the Companies Act, 2013.
Sebi Seeks Details After MCX Trading Disruption
- Established: Year: 2003 Headquarters: Mumbai, Maharashtra
- Headquarters: Mumbai, Maharashtra
- Ownership & Regulation: Regulated by: Securities and Exchange Board of India (SEBI) Operates as a demutualized exchange, meaning ownership and management are separate from trading membership.
- Operates as a demutualized exchange, meaning ownership and management are separate from trading membership.
Small Finance Banks (SFBs)
- Priority Sector Lending: ≥75% of adjusted net bank credit
- Minimum Capital: ₹200 crore
- Deposit Limit: ₹2 lakh per individual
- Crisil Ratings projects that advances of Small Finance Banks (SFBs) will exceed ₹2 trillion in FY26, marking a 16–17% year-on-year growth, up from 13% in FY25. The growth is driven by non-microfinance segments and a gradual recovery in microfinance loans.
SEBI Proposes Overhaul of Mutual Fund Regulations
- Brokerage cap: Cash market: Reduced from 0.12% (12 bps) to 0.02% (2 bps) Derivatives: Reduced from 0.05% (5 bps) to 0.01% (1 bps)→ Prevents investors from being charged multiple times for overlapping services.
- Cash market: Reduced from 0.12% (12 bps) to 0.02% (2 bps)
- Derivatives: Reduced from 0.05% (5 bps) to 0.01% (1 bps)→ Prevents investors from being charged multiple times for overlapping services.
- To offset reduced distribution margins, SEBI proposed a 5 bps upward revision in the first two TER slabs for small open-ended active funds.
| Term | One-Line Explanation |
|---|---|
| TER (Total Expense Ratio) | Annual percentage of fund assets charged to cover management and operational costs. |
| AMC (Asset Management Company) | Entity that manages mutual fund schemes and investor money. |
| AUM (Assets Under Management) | Total market value of assets a fund manages on behalf of investors. |
| Basis Point (bps) | One-hundredth of a percent (0.01%), used for precise fee or rate measurement. |
| Chinese Wall | Internal barrier preventing conflict of interest between two business units. |
| Non-Pooled Fund | Investment vehicle serving large, specific clients rather than public investors. |
| NFO (New Fund Offer) | Initial launch phase of a mutual fund scheme to raise capital from investors. |
RBI Eases Rules for External Commercial Borrowings
- The RBI has removed or relaxed these cost caps, giving borrowers and lenders freedom to negotiate interest rates based on market conditions.
- Impact: Makes Indian borrowers more attractive to global investors. Offers greater flexibility in structuring loans.
- Makes Indian borrowers more attractive to global investors.
- Offers greater flexibility in structuring loans.
| Term | Explanation |
|---|---|
| ECB (External Commercial Borrowing) | Loans in foreign currency raised by Indian entities from non-resident lenders (like banks, institutions, or capital markets). |
| Automatic Route | Borrowing mechanism where no prior RBI approval is required if conditions are met. |
| Tranche | A portion or installment of a total borrowing amount raised at one time. |
| SOFR (Secured Overnight Financing Rate) | Benchmark interest rate replacing LIBOR for US dollar loans. |
| Currency Conversion | The process of switching loan denomination from one currency (e.g., USD) to another (e.g., INR). |
Bank Merger
- In case of public sector banks, mergers are carried out under the Banking Companies (Acquisition and Transfer of Undertakings) Act, 1970/1980 and require Cabinet approval on recommendation of the Finance Ministry.
- Governed by the Banking Regulation Act, 1949, particularly Sections 44A and 45.
- Capital Adequacy: Post-merger CRAR (Capital to Risk-weighted Assets Ratio) must meet minimum regulatory standards (as per Basel III norms, currently 11.5% including buffers).
- The Reserve Bank of India (RBI) acts as the regulatory authority overseeing all bank mergers in India to ensure financial stability and depositor protection.
| Banks Under Consideration | Rationale / Notes |
|---|---|
| Union Bank of India + Bank of India | Would create the second-largest PSB with assets of ₹25.67 trillion, just behind SBI; focus on scale and efficiency. |
| Indian Overseas Bank + Indian Bank | Operational synergies, complementary geographies, similar customer base and product portfolio, rationalization of branches and back-end functions. |
RBI’s New Nomination Rules for Bank Accounts and Lockers
- Effective Date: 1 November 2025
- Covered Entities: Deposit Accounts (Savings, Current, Fixed Deposits, etc.) Safe Deposit Lockers Articles in Safe Custody with Banks
- Safe Deposit Lockers
- Banks must inform customers about the availability and advantages of the nomination facility.
SIDBI Outlook Survey on MSMEs
- The Small Industries Development Bank of India (SIDBI) released its fourth MSME Outlook Survey for July–September 2025 (Q2 FY26). The survey assesses the performance and confidence levels of India’s micro, small, and medium enterprises (MSMEs) through structured indicators.
- Sales sentiment: Manufacturing: 47% of firms reported positive growth. Trading: 50% reported positive growth. Exports: Only 43% saw growth now; 56% expect recovery.
- Manufacturing: 47% of firms reported positive growth.
- Trading: 50% reported positive growth.
SEBI Proposes Simpler Mutual Fund Rules to Cut Investor Costs
- Brokerage cuts: Cash market 0.12% → 0.02%; Derivatives 0.05% → 0.01%.
- Exit-load expenses: Additional 0.05% charge removed; exit load continues to credit schemes directly.
- Revised Expense Ratio (TER): First two slabs for open-ended active schemes raised by 5 bps.
- Regulation 24(b) updated to allow AMCs/subsidiaries to provide advisory services to non-pooled funds with Chinese walls and trustee oversight.
RBI Proposes Measures to Speed Up Cross-Border Remittances
- Same-Day Credit: Banks are advised to credit inward remittances received during forex market hours on the same business day. Currently, only 8–10% of inward remittances reach beneficiaries within an hour, compared to 75% in the US.
- Currently, only 8–10% of inward remittances reach beneficiaries within an hour, compared to 75% in the US.
- Banks are advised to credit inward remittances received during forex market hours on the same business day.
- Real-Time Nostro Reconciliation: Banks must reconcile and confirm credits in their nostro accounts on a near real-time basis or at maximum intervals of 30 minutes. This addresses delays caused by end-of-day reconciliation practices.
India’s UPI Ecosystem
- P2P Payments: Transfers between individuals.
- P2M Payments: Payments from individuals to merchants or service providers.
- The Unified Payments Interface (UPI) in India continues to lead global digital payment innovation. A report by Worldline highlights the upcoming growth drivers for UPI, focusing on enhanced user experience, global adoption, and embedded financial services.
- Conversational “Chat and Pay” Journeys: Integration of payments within messaging/chat platforms for seamless transactions.
Agriculture · 30
Arya.ag Wins SmartAG Award 2025
- Arya.ag, an integrated grain commerce platform, has been recognized with the SmartAG Award 2025 for its solutions promoting climate resilience and sustainable agriculture for smallholder farmers.
- Operated by women community value chain resource persons.
- Provides smallholder farmers in climate-vulnerable regions with real-time access to advanced agri-tech services: Soil testing Drone-based spraying Hyperlocal weather advisories
- Core of Arya.ag’s award-winning solution.
Farmer Suicides in India – NCRB 2023 Data
- Farmer vs Agricultural Worker Suicides: Farmers/Cultivators: 4,690 (4,553 male; 137 female) Agricultural Workers: 6,096 (5,433 male; 663 female) Farm sector suicides accounted for 6.3% of total suicides (1,71,418) in India in 2023.
- Farm sector suicides accounted for 6.3% of total suicides (1,71,418) in India in 2023.
- The National Crime Records Bureau (NCRB) reported that 10,786 farmers and agricultural workers committed suicide in 2023. This continues a trend of over 10,000 farm sector suicides annually, highlighting ongoing distress in agriculture.
- Maharashtra: 38.5% of cases (highest), especially Marathwada and Vidarbha cotton/soybean belts.
AVPL Launches Tech Park to Indigenize Drone Components
- Focus Areas: Development of autonomous navigation systems. Creation of lightweight drone frames. Integration of AI-powered sensors for precision agriculture. Manufacturing of high-capacity batteries tailored for agricultural drones.
- Integration of AI-powered sensors for precision agriculture.
- Enhanced Productivity: Drones equipped with advanced sensors can monitor crop health, optimize pesticide use, and improve irrigation efficiency.
- Data-Driven Decisions: Real-time data collection enables farmers to make informed decisions, leading to better yield and resource management.
National Pulses Mission (2025–31)
- Duration: Six years (2025–26 to 2030–31)
- Boost Domestic Production: Raise production from 242 lakh tonnes (2024–25) to 350 lakh tonnes (2030–31).
- Budget: ₹11,440 crore
- Expand Cultivation Area: Bring pulses area under cultivation to 310 lakh hectares.
Crop Insurance Premiums Fall 34% in FY26
- Major Insurer Performance: Agriculture Insurance Company of India (segment leader): ₹2,539 crore, down 4% YoY.
- Agriculture Insurance Company of India (segment leader): ₹2,539 crore, down 4% YoY.
- State Trends: Maharashtra’s crop insurance premium dropped sharply from ₹9,000 crore earlier to ~₹3,000 crore. Other states may follow re-tendering practices, further reducing premiums.
- Maharashtra’s crop insurance premium dropped sharply from ₹9,000 crore earlier to ~₹3,000 crore.
Mission for Atmanirbharta in Pulses
- Projected demand-supply gap: 15.7 mt by 2030, narrowing to 4.5 mt by 2047 (NITI Aayog report).
- The Union Cabinet approved a ₹ 11,440 crore Mission for Atmanirbharta in Pulses, aimed at boosting domestic pulse production, reducing import reliance, and strengthening India’s food security, nutrition, and environmental sustainability.
- Low productivity: India produces 27.4% of global pulses but has the lowest yield among top 10 producers, at 0.74 t/ha—less than half of Ethiopia or Canada.
- Post-harvest losses: Storage challenges lead to 5–7% losses, affecting availability and price stability.
KisanKraft Launches Nationwide Campaign to Promote Dry Direct Seeded Rice (DDSR) Technology
- Water Efficiency: Reduces water use by 50–60% as there is no puddling or standing water.
- Reduced Methane Emissions: DDSR produces negligible methane, unlike wetland rice which contributes 8–12% of global methane emissions.
- Faster Maturity: DDSR varieties mature in 110–140 days, adapting well to diverse soil conditions.
- The technique involves directly sowing rice seeds into dry soil instead of transplanting seedlings from nurseries.
Kerala Launches Initiative to Promote Low-Emission Rice-Based Farming Systems
- Kerala Agricultural University (KAU)
- The initiative forms part of the Kerala Climate Resilient Agri-Value Chain Modernization Project (KERA), implemented by the Department of Agriculture and Farmers’ Welfare with World Bank support.
- Support sustainable agricultural practices through economic incentives for farmers.
e-NAM Platform Expanded with 09 New Commodities
- Launched: 14 April 2016
- Aim: Promote uniform agricultural marketing Reduce information asymmetry between buyers and sellers Ensure transparent price discovery based on demand, supply, and quality
- Reduce information asymmetry between buyers and sellers
- Digital Marketplace: Links APMCs, private markets, and buyers nationwide.
Prime Minister Launches PM Dhan-Dhaanya Krishi Yojana & Dalhan Atmanirbharata Mission
- Infrastructure & Support: 25 crore Soil Health Cards distributed Micro-irrigation covering 100 lakh hectares PM Fasal Bima Yojana insurance claims: ₹2 lakh crore 10,000 FPOs formed for better market access
- PM Fasal Bima Yojana insurance claims: ₹2 lakh crore
- Aim: Transform agriculture in 100 low-performing districts by enhancing crop productivity, sustainable farming, post-harvest storage, irrigation, and credit access.
- Target: Expand pulse cultivation area by 35 lakh hectares; increase production of tur, urad, and masoor pulses.
Pradhan Mantri Dhan-Dhaanya Krishi Yojana (PMDDKY) 2025
- On October 12, 2025, Prime Minister Narendra Modi launched the Pradhan Mantri Dhan-Dhaanya Krishi Yojana (PMDDKY), a landmark scheme targeting 100 low-performing districts to modernize farming, enhance productivity, and double farmers’ income by 2030.
- Double Farmers’ Income: By 2030 through modern farming and market access.
- Budget Allocation: ₹1.44 lakh crore over 6 years (₹24,000 crore annually, 2025–31).
- Increase Crop Productivity: Targeting 20–30% growth.
Natural Farming Gains Traction in Himachal Pradesh
- Launched: 2018.
- Farmers trained: 3.06 lakh
- Practising natural farming: 2.22 lakh farmers (partial or full adoption)
- Certification: Over 2 lakh farmers certified under CETARA–NF (Certified Evaluation Tool for Agriculture Resource Analysis), a self-assessment certification mechanism under PK3Y.
India’s Mariculture Ambitions and ICAR-CMFRI Initiatives
- Production Target: ICAR-Central Marine Fisheries Research Institute (CMFRI) targets 2.5 million tonnes of mariculture production by 2047, up from the current 1.5 lakh tonnes.
- Training and Support: A nationwide training programme for fish farmers was launched in conjunction with Pradhan Mantri Dhan Dhanya Krishi Yojana (PMDDKY).
- Seaweed Potential: India’s current seaweed production is low compared to the global output of 35.5 million tonnes. CMFRI estimates a potential of 5 million tonnes domestically, catering to industrial and nutraceutical demand.
ICAR Approves 28 New Wheat and Barley Varieties Ahead of Sowing Season
- Punjab Agriculture University (PAU): 2 varieties approved – PBW 906 (central zone) and PBW 915 (North-East Plain Zone), both rust-resistant and high-yielding.
- Varieties Cleared: Out of 46 new requests, 23 wheat varieties and all 5 barley varieties were identified for approval by the Varietal Identification Committee (VIC).
- The Indian Council of Agricultural Research (ICAR) has approved 28 new wheat and barley varieties for consideration by the Central Sub-Committee on Crop Standards, Notification & Release of Varieties (CSN&RV), just before the start of the wheat sowing season.
- Regional Focus: Punjab Agriculture University (PAU): 2 varieties approved – PBW 906 (central zone) and PBW 915 (North-East Plain Zone), both rust-resistant and high-yielding. Indian Agricultural Research Institute (IARI): 7 of 11 wheat varieties approved. Indian Institute of Wheat and Barley Research (IIWBR): 2 of 6 wheat varieties and all 3 barley varieties approved.
NITI Aayog Releases Report on Deep-Sea and Offshore Fisheries in India
- Economic Impact: Fisheries sector supports nearly 30 million livelihoods; fishery exports earned ₹60,523 crore in FY 2023–24.
- Phase 3 (2033 onwards): Achieve global leadership in sustainable deep-sea fisheries.
- Global Position: India is the second-largest fish-producing country, contributing 8% of global production.
- Phase 1 (2025–28): Lay the foundation and foster early growth.
IFBA Launches Food Awareness Initiative on World Food Day
- National Institute of Food Technology, Entrepreneurship and Management (NIFTEM-Kundli)
- Promote informed dialogue and collaborative action across the food ecosystem, bringing together industry leaders, regulators, researchers, and academia.
- Empower consumers to make science-backed, healthy food decisions.
- A1 vs A2 ghee varieties.
Finance Minister Inaugurate Farmers Training and Agro-Processing Centres in Kalyana Karnataka
- Objectives: Enhance farmers’ income. Create employment opportunities. Build entrepreneurial capacities in farmer organizations.
- Inauguration by Nirmala Sitharaman, Minister for Finance and Corporate Affairs.
- Established with contributions from MPLADS, in collaboration with NABARD.
- Enhance farmers’ income.
NABARD to Launch Digital Infrastructure for Rural Cooperative Banks
- Timeline: Expected in the second half of FY2025-26.
- Aims to modernize banking operations in rural areas.
- Planner: NABARD (National Bank for Agriculture and Rural Development)
Krishi Mangal 3.0
- Objective: Empower farmers by scaling startups that provide climate-smart, technology-driven solutions to enhance productivity, profitability, and sustainability.
- Deployment-focused, milestone-based non-dilutive funding of up to ₹50 lakh per startup.
- Potential additional funding of up to ₹2 crore for expansion.
- Access to 200,000+ farmers and 150 FPOs for scaling solutions.
Union Finance Minister Inaugurates Farmers’ Training cum Common Facility Centre at Koppal
- PM Kisan Samman Nidhi Yojana (PM-KISAN): Provides ₹6,000/year in three installments to 43 lakh farmers in Karnataka via Direct Benefit Transfer (DBT).
- ₹24,000 crore allocation for PM FME in 2025-26.
- Since 2020, ₹3,700 crore distributed to states for farmer loans and support, generating over 1 lakh agriculture entrepreneurs.
- Aim: Empower farmers and agro-entrepreneurs by providing training, processing, and storage facilities.
Centre to Roll Out Tech-Enabled Monitoring for Farmer Schemes
- Objective: Bridge the gap between policy formulation and implementation. Ensure farmers are aware of, understand, and can access schemes. Promote adoption of sustainable and improved farming practices.
- Quarterly Stakeholder Meetings: States will conduct quarterly meetings at block, district, and state levels with farmers, panchayat representatives, and other stakeholders to assess implementation of government schemes.
- States will conduct quarterly meetings at block, district, and state levels with farmers, panchayat representatives, and other stakeholders to assess implementation of government schemes.
- Ensure farmers are aware of, understand, and can access schemes.
Social Alpha & Sustain Plus Tie-Up with PRADAN to Strengthen Agri Value Chain in Jharkhand
- Improve livelihoods of ~1 lakh small and marginal farmers over four years.
- Directly empower 40,000 women across 20 Farmer Producer Organisations (FPOs) in 20 blocks.
- Integration of farming with allied activities and entrepreneurship.
India’s Agricultural Climate Initiatives: Building a Climate-Resilient Agri-Ecosystem
- Agroforestry: Integrating trees with crops to enhance biodiversity, prevent soil erosion, and improve micro-climates.
- Natural/Organic Farming: Adoption of organic inputs (cow dung, biofertilizers) to reduce chemical dependence.
- Climate Forecasting Models: Provide timely information to farmers for informed decision-making.
- Capacity-building programs educate farmers on sustainable practices.
Kapas Kranti Mission
- Budget Allocation: ₹600 crore over multiple years.
- Nodal Ministry: Ministry of Agriculture and Farmers’ Welfare
- The Central Government has launched the ₹600 crore “Kapas Kranti Mission” to enhance cotton productivity and promote sustainable cultivation practices across India. The initiative focuses on long-staple, high-yield cotton through scientific innovation and farmer-oriented extension services.
Per Drop More Crop Scheme
- Launched: 2015
- Earlier, funding for such activities was capped at 20% of total allocation for each state/UT.
- For Northeastern and Himalayan states, as well as UTs of J&K and Ladakh, the cap was 40%.
- Part of the Pradhan Mantri Krishi Sinchayee Yojana (PMKSY) – launched in 2015 to achieve “Har Khet Ko Pani” (Water for Every Field) and improve water-use efficiency in agriculture.
NABARD Announces First Investment Under AgriSURE Fund at Global Fintech Festival 2025
- At the Global Fintech Festival (GFF) 2025, the National Bank for Agriculture and Rural Development (NABARD) announced its first investment under the AgriSURE Fund, jointly promoted with the Union Ministry of Agriculture and Farmers Welfare. The initiative highlights NABARD’s focus on fostering agritech innovation, rural entrepreneurship, and digital financial inclusion.
- To promote digital and financial inclusion in agriculture and allied sectors.
- At GFF 2025, NABARD showcased several of its supported and funded ventures that are driving innovation and rural financial inclusion, including:
- NAVADHAN Capital: Facilitates accessible and affordable credit for smallholder farmers and rural entrepreneurs.
National Seeds Corporation Launches Modern Seed Processing and Management Systems to Boost Farm Productivity
- NSC, a Miniratna public sector enterprise under the Ministry of Agriculture and Farmers Welfare, is responsible for producing, processing, and distributing quality seeds across the country.
- The Agriculture Minister highlighted that fake and substandard seeds had become a recurring challenge for farmers.
- The new plants will ensure that certified, high-germination seeds reach farmers efficiently and in time for the sowing seasons.
- The Minister also launched Seed Management 2.0 and an online seed booking platform.
Centre Approves ₹15,096-Crore Procurement of Pulses and Oilseeds under MSP
- Total Procurement Value: ₹ 15,095.83 crore
- Price Support Scheme (PSS):Central government-backed mechanism ensuring procurement at Minimum Support Price (MSP) to protect farmers from distress sales. Implemented through NAFED and NCCF as central nodal agencies.
- Bhawantar Bhugtan Yojana (BBY): A price deficiency payment scheme, where farmers receive compensation for the difference between MSP and actual market price. Promotes market-based sales while ensuring income protection.
- A price deficiency payment scheme, where farmers receive compensation for the difference between MSP and actual market price.
| State | Crop(s) Covered | Key Features |
|---|---|---|
| Telangana | Mung beans, black gram, soybean | 100% procurement approved for all these crops under Price Support Scheme (PSS) |
| Odisha | Pigeon pea (tur) | Full procurement permitted |
| Maharashtra | Mung beans, black gram, soybean | Largest procurement among the four states under PSS |
| Madhya Pradesh | Soybean | Bhawantar Bhugtan Yojana (BBY) to be launched for soybean |
Cabinet Approves ₹37,952 Crore Fertilizer Subsidy for Rabi 2025-26 Season
- Total Subsidy: ₹37,952 crore for Rabi 2025-26 — an increase of ₹14,000 crore compared to the previous Rabi season (₹24,000 crore in 2024-25).
- Nitrogen (N): ₹43.02 (unchanged from Kharif 2025)
- Phosphorus (P): ₹47.96 (up from ₹43.60 during Kharif 2025)
- Sulphur (S): ₹2.87 (up from ₹1.77 during Kharif 2025)
Nutrient Based Subsidy (NBS) Scheme
- Launched on 1st April 2010, replacing the earlier product-based subsidy system for non-urea fertilizers.
- Urea exception: Urea remains under statutory price control, with fixed MRP of ₹242 per 45-kg bag since March 2018.
- The Union Cabinet, chaired by the Prime Minister, approved NBS rates for Rabi 2025–26 for Phosphatic and Potassic (P&K) fertilizers to ensure smooth availability at affordable prices.
- Coverage: 28 grades of P&K fertilizers, including DAP and NPKS grades.
Facts To Remember · 64
Centre appoints RBI ED Murmu as Deputy Governor
- The Appointments Committee of the Cabinet (ACC) has approved the appointment of Shirish Chandra Murmu, Executive Director, Reserve Bank of India (RBI), for the post of Deputy Governor, RBI, for a period of three years.
Prabu wins gold; silver medals for Dewan and Tarushi
- Nine-year-old Aaruthran Prabu won gold in the karting slalom cadet class while Aarav Dewan, a 15-year-old from Gurugram, and Chikmagaluru’s Tarushi Vikram, won a silver each in the FIA Asia-Pacific motorsport championship at Bandaragama (Sri Lanka).
Punjab farm groups oppose crackdown on stubble burning
- Farmer bodies have begun opposing the crackdown on stubble burning in Punjab and demanded cash incentives for farmers to desist from the practice, in keeping with the 2019 SC directive on crop-residue management.
Tata Capital’s ₹15,511 Crore IPO to be India’s Largest NBFC Listing
- Tata Capital, the financial services arm of Tata Group, is launching its ₹15,511-crore Initial Public Offering (IPO), making it the largest-ever IPO by any Non-Banking Financial Company (NBFC) in India and Tata Group’s biggest IPO to date.
Sidbi net profit rises by 19.5% to record high of ₹4,811 cr in FY25
- Small Industries Development Bank of India (Sidbi) said its net profit rose by 19.5 per cent to hit an all-time high of Rs 4,811 crore in the 2024-25 financial year.
Srihari wins his fifth medal, Rohit claims silver in 50m butterfly
- Star Indian swimmer Srihari Nataraj once again stood tall, bagging a bronze in the 100m freestyle to extend his personal haul to five medals at the 11th Asian aquatics championships.
Indian Railways to Launch First Container Service with Assured Transit Time
- Indian Railways, in partnership with Container Corporation of India (CONCOR), will launch its first container train service with assured transit time on a pilot basis from October 1, 2025.
Dharambir, Atul add to India’s medal tally
- On a day the retreating monsoon decided to turn up in full force in the city, Dharambir Nain proved he was still one of the best, winning silver in the club throw F51 category on the fifth day of the 2025 World Para Athletics Championships.
Global Agency Projections for India (FY26)
- CII: 6.4–6.7%
- Fitch: 6.9% (FY26), 6.3% (FY27)
- S&P Global: 6.5%
- UN: 6.3% (FY26), 6.4% (FY27)
PM Modi launches ₹62,000-crore schemes targeted at Bihar youth
- Prime Minister Narendra Modi on Saturday launched various youth-focused initiatives estimated at more than ₹62,000 crore, with a focus on poll-bound Bihar, from New Delhi.
India adds nearly 17 crore jobs in six years as unemployment dips to 3.2%
- Around 17 crore jobs have been added to the workforce in India over six years. As per the Labour and Employment Ministry, employment in India rose to 64 crore 33 lakh in 2023-24 compared to 47 crore 50 lakh in 2017-18, a net addition of 16 crore 83 lakh jobs over six years.
IAF Celebrates 93rd Anniversary with Aerial Display at Hindan Airbase
- The 93rd anniversary of the Indian Air Force (IAF) was commemorated at Air Force Station Hindan in Uttar Pradesh’s Ghaziabad today. This Air Force Day celebration included a spectacular aerial display by the Heritage Flight.
India Wins Global Social Security Award; Mandaviya Unveils Draft ‘Shram Shakti Niti 2025’
- India has been conferred with the Outstanding Achievement in Social Security Award 2025 by the International Social Security Association.
PM Modi Inaugurates 9th India Mobile Congress; Says Digital Connectivity is no Longer a Luxury
- Prime Minister Narendra Modi today inaugurated the ninth edition of the India Mobile Congress 2025, Asia’s largest telecom, media, and technology event at Yashobhoomi in New Delhi.
PM Modi hails ₹24,000 Cr rail projects to boost connectivity across four states
- Prime Minister Narendra Modi has said that Union Cabinet approval for four key multi-tracking projects of the Indian Railways worth over 24,000 crore across Maharashtra, Madhya Pradesh, Gujarat and Chhattisgarh
IAF to Receive First Indigenous Tejas Mk1A Fighter Jet
- The Indian Air Force (IAF) is set to induct the first Light Combat Aircraft (LCA) Tejas Mk1A, a significant milestone in India’s indigenous fighter aircraft development programme led by Hindustan Aeronautics Limited (HAL).
Champion jockey Aslam Kader passes away
- Former champion jockey Aslam Kader passed away on Thursday morning (Oct. 9) in Bengaluru, after a long battle with lung cancer. He was 63.
All-India house price index up 3.6% annually in Q1: RBI
- All-India House Price Index (HPI) based on transaction-level data of 18 major cities increased by 3.6% year-on-year in the first quarter of the current fiscal, according to the Reserve Bank of India (RBI) data released
India-UK Navies Conduct First Combined Carrier Strike Group Exercise
- The United Kingdom’s Royal Navy frigate HMS Richmond arrived at Mumbai Port today following the successful conclusion of Exercise Konkan 2025, held off India’s western coast from 5th-9th of this month.
India Wins Historic Bronze at BWF World Junior Mixed Team Championships 2025
- The Indian Badminton team clinched bronze in the Mixed Team event at the BWF World Junior Mixed Team Championships 2025 in Guwahati
Reserve Bank of India Appoints Shirish Chandra Murmu as Deputy Governor
- Shirish Chandra Murmu took charge as the Deputy Governor of the Reserve Bank of India yesterday for a period of three years.
RBI appoints Sonali Sen Gupta as Executive Director
- The Reserve Bank of India (RBI) has appointed Sonali Sen Gupta as Executive Director (ED) with effect from October 09, 2025.
Diane Keaton, Oscar winner, star of Annie Hall, Godfather, dead
- Actress Diane Keaton, known for her Oscar-winning performance in 1977’s Annie Hall and her role in The Godfather films, has died at age 79.
Govt Launches Employees’ Enrolment Campaign 2025 to Boost Social Security Coverage
- The Government has launched Employees’ Enrolment Campaign 2025 to expand social security coverage of employees. This campaign is intended to encourage employers to voluntarily declare and enroll eligible employees.
Indian Army Troops Arrive in Australia for 4th Edition of Exercise AUSTRAHIND 2025
- In Australia, around 120 troops from the Indian Army have arrived to participate in the 4th edition of Exercise AUSTRAHIND 2025 with the Australian Army from today.
India to Participate in NAM Ministerial in Kampala on 15th–16th October
- Minister of State for External Affairs Kirti Vardhan Singh will be leading the Indian delegation for the 19th Mid-Term Ministerial of the Non-Aligned Movement (NAM) being held in Kampala, Uganda, on the 15th and 16th of this month.
India’s Largest School Hackathon ‘Viksit Bharat Buildathon 2025’ Begins Today
- India's largest school hackathon, ‘Viksit Bharat Buildathon 2025', will be held today between 10 AM and 11 PM.
India to launch first nationwide income survey in February 2026
- The Centre will launch India’s first nationwide household income survey in February 2026, marking a major step toward filling a persistent data gap in measuring income distribution and inequality, the ministry of statistics and programme implementation (MosPI).
International Purple Fest
- On the second day of the International Purple Fest Goa 2025, three transformative initiatives were unveiled to strengthen accessibility in listening, reading, and writing for persons with disabilities, marking a step forward in inclusive education and skill development.
Indian Banks’ Deposit Growth Slows in Q2 FY26, Credit Outpaces Deposits
- Credit-deposit ratio (CD ratio): Rose to 80.3%, crossing 80% for the first time in six months. In Q2 FY26 (July–September 2025), loan growth in Indian banks outpaced deposit growth, reversing the trend seen in Q1.
Tribal Affairs Minister Jual Oram Launches Adi Karmayogi Abhiyan to Train 20 Lakh Change-Leaders
- Tribal Affairs Minister Jual Oram has said that the Adi Karmayogi Abhiyan aimed to build a cadre of 20 lakh trained change-leaders across one lakh tribal villages in the country.
Defence Minister Rajnath Singh Unveils First Tejas LCA Mk1A from HAL’s New Nashik Production Line
- Defence minister Rajnath Singh today unveiled the first Tejas LCA MK1A fighter jet from Hindustan Aeronautics' new Nashik production line.
8th National Nutrition Mission Concludes Today with Grand Event in Dehradun
- The 8th National Nutrition Mission will conclude today with a grand event in Dehradun, the capital of Uttarakhand.
Legendary horse trainer Padmanabhan passes away
- The Indian horse racing fraternity bid goodbye to one of its most brilliant trainers, S. Padmanabhan, popularly known as Paddy, who passed away at Bengaluru. He was 71 and is survived by wife Sharmila Padmanabhan, who was a pillar of support.
146 Bird Species Recorded in Kaziranga Survey
- The Kaziranga National Park and Tiger Reserve, Assam, recorded 146 bird species in its latest avian survey, highlighting the park’s rich biodiversity.
India to Induct 800-km BrahMos and Upgraded Astra Missiles
- India plans to significantly enhance its precision strike capabilities with the induction of 800-km extended range BrahMos supersonic cruise missiles and the over 200-km Astra air-to-air missiles in the next two to three years.
26% of PMJDY Accounts in PSBs Are Inoperative
- The share of inactive Pradhan Mantri Jan-Dhan Yojana (PMJDY) accounts in public sector banks (PSBs) has risen to 26% as of September 2025, up from 21% in September 2024, indicating a slowdown in account activity under India’s flagship financial inclusion scheme.
Vanasamrakshana Samiti (forest protection committee)
- Members often assist forest officials in fire prevention, wildlife rescue, and ecological monitoring.
Centre Notifies Amendments to IT Rules, 2025 to Boost Content Moderation Transparency
- Ministry of Electronics and Information Technology has notified the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Amendment Rules, 2025 to amend the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules – IT Rules, 2021.
Earth Sciences Ministry Conducts 54 Cleanliness Campaigns, Clears 192 Files Under SCDPM 5.0
- The Ministry of Earth Sciences has conducted 54 impactful cleanliness campaigns and has weeded out 192 files after a thorough review of more than 500 files and records under the Special Campaign for Disposal of Pending Matters (SCDPM) 5.0.
NHAI to Deploy 3D Survey Vehicles in 23 States for AI-Based Highway Monitoring
- National Highways Authority of India (NHAI) will deploy Network Survey Vehicles in 23 states covering 20 thousand 933 km for the collection, processing and analysis of Road inventory and Pavement condition data of National Highway stretches.
Union Government Proposes Mandatory Labelling of Synthetic AI-Generated Content on Social Media
- The Ministry of Electronics and Information Technology (MeitY) has released a draft amendment to the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021, proposing mandatory disclosure and labelling of all AI-generated or synthetic content on social media platforms. The move follows growing public and parliamentary concern over deepfakes, impersonation, and misinformation spread through synthetic media.
RBI Shifts Focus from US Treasuries to Gold
- India’s Reserve Bank of India (RBI) has increasingly added gold to its reserves while reducing investments in US Treasury Securities since the start of FY2025-26. This reflects a strategy to diversify forex reserves amid global economic uncertainties.
SBI Recognised as World’s Best Consumer Bank 2025
- Awards: World’s Best Consumer Bank 2025 Best Bank in India 2025
- World’s Best Consumer Bank 2025
- Best Bank in India 2025
- Significance: Reinforces SBI’s global leadership in banking. Highlights excellence in innovation, financial inclusion, and customer service. Recognises technological leadership and expansion across India’s diverse regions.
Two-Minute Film on ‘Sabki Yojana, Sabka Vikas’ to Promote People’s Role in Grassroots Planning
- A two-minute Public Service Awareness film on the People’s Plan Campaign - Sabki Yojana, Sabka Vikas will be screened across cinema theatres in the country from today till 6th November.
Gaganyaan Uncrewed Test Flight Ready for Launch in December, Says ISRO Chief Dr. V. Narayanan
- The Indian Space Research Organisation Chairman, Dr V Narayanan, has informed that 90 percent of the work on the Gaganyaan uncrewed test flight mission G1 is over, and they are set for launch in December first week.
ESTIC 2025 to Be Held at Bharat Mandapam from Nov 3–5
- Emerging Science, Technology, and Innovation Conclave (ESTIC) 2025 will be organised from 3rd to 5th November, at Bharat Mandapam in New Delhi.
ISRO Says 90% of Gaganyaan Development Complete
- Bengaluru: The Indian Space Research Organisation (ISRO) is making steady progress on its Gaganyaan mission, with about 90% of the development work already completed, according to ISRO Chairman V. Narayanan.
Prime Minister will lead parade on 150th birth anniversary of Sardar Vallabhbhai Patel
- Prime Minister Narendra Modi will lead the Rashtriya Ekta Diwas parade near Kevadia in Gujarat on October 31 to commemorate the 150th birth anniversary of Sardar Vallabhbhai Patel, the first Deputy Prime Minister and Home Minister of the country.
India’s Private Sector Growth Slows to Five-Month Low in October: HSBC Flash PMI
- India’s private sector growth lost some momentum in October 2025, as business activity was dampened by weaker demand conditions and rising output prices, according to the HSBC Flash India Composite Purchasing Managers’ Index (PMI) compiled by S&P Global.
Australia launches First Nations mission to boost mining, RE sector ties with India
- Australia will send itsfirst-ever First Nations business mission to India this month to strengthen trade and investment links between Indigenous Australian enterprises and Indias mining and renewable energy sectors.
IPL Biologicals Wins Bronze at 10th Bernard Blum Awards 2025 for Biocontrol Innovation ‘Bellator’
- IPL Biologicals Ltd, a leading Indian company specializing in biological solutions for sustainable agriculture, has won the Bronze Award at the 10th Bernard Blum Awards 2025 for its innovative biocontrol product, Bellator.
- Event: 10th Bernard Blum Awards 2025
- Organisers: Jointly hosted by the International Biocontrol Manufacturers Association (IBMA) and FiBL (Research Institute of Organic Agriculture)
Paytm enables UPI payments for NRIs using international mobile numbers
- Paytm has launched a service allowing Non-Resident Indians from 12 countries to make UPI payments in India using their international mobile numbers, the company announced today. The feature eliminates the need for a local Indian SIM card and works with NRE or NRO bank accounts.
Vigilance Awareness Week 2025 Begins Nationwide with Theme “Vigilance – Our Shared Responsibility”
- The Vigilance Awareness Week 2025 is being observed across the country from today to promote probity in public life and achieve a corruption-free society.
Rashtriya Vigyan Puraskar 2025 announced
- Rashtriya Vigyan Puraskar 2025 were announced today. Prof. Jayant Vishnu Narlikar will be given the Vigyan Ratna award posthumously.
World’s oldest President, Paul Biya, wins Cameroon election at 92
- The world’s oldest President, Cameroon’s 92-year-old Paul Biya, won election again, the country’s top court said, after days of protesters’ clashes with security forces left at least four dead as opposition demanded credible results.
Youth Engagement Initiative ‘Mera Yuva Bharat’ Crosses 2 Crore Registrations
- Flagship youth engagement initiative of The Ministry of Youth Affairs and Sports, Mera Yuva Bharat, has achieved a milestone with the platform by crossing over 2 crore registrations.
National Maritime Heritage Complex Logo Launched at India Maritime Week 2025
- Union Minister of Ports, Shipping and Waterways, Sarbananda Sonowal, today unveiled the logo of the proposed National Maritime Heritage Complex (NMHC) at Lothal in Gujarat on the second day of India Maritime Week 2025 in Mumbai.
India Ranks Third Globally in Solar Power Generation: Union Minister Pralhad Joshi
- Union Minister Pralhad Joshi today said that India has ranked third globally in solar power generation, having achieved 50 per cent of the installed capacity.
Manush and Diya make it to the WTT Finals
- India’s Manush Shah and Diya Chitale qualified for the mixed doubles event of the WTT Finals, to be held in Hong Kong from December 10 to 14. No Indian in any category has made it to the WTT Finals since it was introduced in 2021.
President Droupadi Murmu Takes Historic Sortie in Rafale Fighter Jet
- President Droupadi Murmu created history by taking a sortie in a Rafale fighter aircraft from the Indian Air Force (IAF) Station in Ambala, Haryana, on October 30, 2025. This marked her as the first President of India to fly in two different fighter jets of the IAF.
RBI Accelerates Repatriation of Gold to Strengthen Reserve Control
- The Reserve Bank of India (RBI) has intensified its efforts to bring gold reserves back to domestic storage, with over 65% of its holdings now in India, nearly double the share from four years ago. This move enhances control over national bullion assets amid global geopolitical uncertainties.
Over 10,000 Farmer-Producer Organisations Established Across India, Says Agriculture Minister Shivraj Singh Chouhan
- Union Agriculture and Farmers’ Welfare Minister Shivraj Singh Chouhan said that so far ten thousand Farmer-Producer Organisations (FPOs) have been established in the country and the turnover of some FPOs have reached 100 crore rupees.
56th International Film Festival of India (IFFI) 2025 in Goa
- With the 56th International Film Festival of India - IFFI 2025 scheduled to be held from 20th to 28th November 2025 at Panaji in Goa
Facts to Remember · 4
Former Rajasthan Speaker Girraj Tiwari passes away
- Former Rajasthan Assembly Speaker Girraj Prasad Tiwari died in Bharatpur late on Thursday night at the age of 105 years.
Government Raises Wheat MSP for 2025-26 Amid Policy Concerns
- The Narendra Modi government has announced a minimum support price (MSP) of Rs 2,585 per quintal for the 2025-26 wheat crop, up Rs 160 from last year. This marks a higher-than-usual hike, exceeding the Rs 150-per-quintal rise of the previous two years.
Power Minister Manohar Lal to attend G20 Energy meet in South Africa
- Power Minister Manohar Lal will participate in the G20 Energy Transitions Ministerial meeting to be held in KwaZulu-Natal Province in South Africa. According to the Ministry of Power, the meeting is being organised under the South African G20 presidency.
Silver Jubilee Edition of FICCI FRAMES Inaugurated in Mumbai
- Speaking at the inauguration, Mr Jaju highlighted the remarkable growth of the media and entertainment industry over the past 25 years. He said the industry has grown tenfold from 25 thousand crore rupees to two lakh 50 thousand crore rupees.
Awards & Recognitions · 4
Nobel Prize 2025
- Shimon Sakaguchi (Japan) - Distinguished Professor, Osaka University: Discovered CD25+ regulatory T cells and their role in suppressing self-attacking T-cells.
- The 2025 Nobel Prize in Physiology or Medicine has been awarded to Mary Brunkow (USA), Fred Ramsdell (USA), and Shimon Sakaguchi (Japan) for their pioneering discoveries on regulatory T cells (Tregs) and the Foxp3 gene, which govern peripheral immune tolerance. Their work has transformed understanding of autoimmune diseases and opened pathways for therapies in cancer, autoimmunity, and transplantation.
- Significance: This discovery is critical for understanding autoimmune diseases, cancer, and organ transplantation. Opens avenues for new therapies and clinical interventions.
- This discovery is critical for understanding autoimmune diseases, cancer, and organ transplantation.
Nobel Prize in Physics 2025
- The 2025 prize includes a monetary award of 11 million SEK (≈ ₹8.5 crore).
- The Nobel Prize in Physics, first awarded in 1901, recognises outstanding contributions to the field of physical sciences that deepen our understanding of the universe.
- The 2025 Nobel Prize in Physics has been awarded to John Clarke, Michel Devoret, and John Martinis for their pioneering experiments that deepened scientific understanding of the quantum world, particularly the phenomenon of quantum tunnelling.
- Quantum tunnelling is a phenomenon where particles such as electrons can pass through energy barriers that they cannot cross under classical physics.
| Name | Institution | Country | Key Contribution |
|---|---|---|---|
| John Clarke | University of California, Berkeley | USA | Developed experimental methods to detect quantum effects in macroscopic systems |
| Michel H. Devoret | Yale University | USA | Advanced understanding of superconducting circuits and quantum coherence |
| John Martinis | University of California, Santa Barbara | USA | Built one of the first practical superconducting qubits for quantum computation |
Hungarian Writer László Krasznahorkai Wins 2025 Nobel Prize in Literature
- The Nobel Prize in Literature, established in 1901, honours an author who has produced “the most outstanding work in an ideal direction.”
- Award ceremonies will be held on December 10, the anniversary of Alfred Nobel’s death, in Stockholm, Sweden.
- The 2025 Nobel Prize in Literature has been awarded to Hungarian novelist László Krasznahorkai, recognised for his “compelling and visionary oeuvre that, in the midst of apocalyptic terror, reaffirms the power of art.” The Nobel Committee praised his philosophical depth, artistic courage, and unique narrative style, which often unfolds in long, uninterrupted sentences.
Sveriges Riksbank Prize in Economic Sciences 2025 (Nobel Prize in Economics)
- Established: 1968 by Sveriges Riksbank on its 300th anniversary.
- First Awarded: 1969 to Ragnar Frisch (Norway) & Jan Tinbergen (Netherlands).
- Medal Design: Obverse: Portrait of Alfred Nobel + crossed horns of plenty (bank symbol) Reverse: North Star emblem of Royal Swedish Academy of Sciences + “Kungliga Vetenskaps Akademien”
- Obverse: Portrait of Alfred Nobel + crossed horns of plenty (bank symbol)
| Nobel Laureate | Affiliation | Contribution / Awarded For |
|---|---|---|
| Joel Mokyr | Northwestern University, USA | Explaining innovation-driven economic growth; identified prerequisites for sustained growth via technological progress. Showed that societies need practical knowledge, scientific understanding, and a culture open to new ideas. |
| Philippe Aghion | Collège de France & INSEAD, France; LSE, UK | Jointly awarded with Peter Howitt for theory of sustained growth through creative destruction; co-developed 1992 model showing how new products/technologies replace old ones, driving productivity and growth. |
| Peter Howitt | Brown University, USA | Emphasized innovation cycles improving living standards, health, quality of life; importance of managing transitions to avoid innovation blockages by vested interests. |
Award and Recognitions · 1
Nobel Chemistry Prize 2025
- The 2025 Nobel Prize in Chemistry was awarded to Susumu Kitagawa (Japan), Richard Robson (Australia/UK), and Omar Yaghi (Jordan/US) for developing metal-organic frameworks (MOFs) — a new class of molecular materials with extraordinary porosity and versatile applications.
| Name | Affiliation | Nationality |
|---|---|---|
| Susumu Kitagawa | Kyoto University, Japan | Japanese |
| Richard Robson | University of Melbourne, Australia | British-born, Australian |
| Omar Yaghi | University of California, Berkeley, USA | Jordanian-American |
Facts To Remember (15 October 2025) · 3
Railways Minister Inaugurates 16th International Railway Equipment Exhibition in New Delhi
- Union Railways Minister Ashwini Vaishnaw today inaugurated the 16th International Railway Equipment Exhibition-2025, Asia’s largest and the world’s second-largest railway exhibition at Bharat Mandapam in New Delhi.
India, Saudi Arabia Hold Bilateral Talks to Boost Cooperation in Chemicals and Petrochemicals
- Union Chemicals and Fertilisers Ministry held a bilateral meeting with the Industry and Minerals Ministry of the Kingdom of Saudi Arabia to further strengthen bilateral cooperation between the two nations in the Chemicals and petrochemicals sector.
India Elected Unopposed to UN Human Rights Council for 2026–28 Term
- India has been elected unopposed to the Human Rights Council for the seventh time for a three-year term (2026-28) starting next year.
Facts To Remember (16 October 2025) · 4
Trade Deficit Widens 93% in September 2025 as Services Exports Decline
- India’s trade deficit almost doubled in September 2025 as imports surged and services exports weakened. The latest data from the Ministry of Commerce and Industry highlights growing pressure on India’s external trade balance despite moderate growth in goods exports.
India Drops to 85th in 2025 Henley Passport Index
- The 2025 Henley Passport Index, which ranks passports based on visa-free access, has seen India fall from 80th to 85th position. Indian passport holders can now access 57 countries without a visa, down from 62 countries last year.
PM Narendra Modi inaugurated multiple development projects worth around 13,430 crore rupees in Kurnool
- Prime Minister Narendra Modi inaugurated multiple development projects worth around 13,430 crore rupees in Kurnool, Andhra Pradesh, this afternoon.
Ahmedabad in Gujarat recommended as host for 2030 Commonwealth Games
- In a landmark development for Indian sports, Ahmedabad in Gujarat has been recommended as the host city for 2030 Commonwealth Games.
Economy · 1
Post-Diwali Farm Challenge: From Consumer Inflation to Farmer Woes
- Food Inflation Eased: Retail food inflation has been in negative territory for four consecutive months ending September 2025, compared to an average of 8.5% annual rise during July 2023–Dec 2024.
- Crop Glut & High Stocks: Wheat stocks stood at 320.3 lakh tonnes on October 1, 2025 — highest in four years and about 1.5 times required buffer. Rice stocks held by government agencies were 4.4 times the PDS plus strategic reserve requirement.
- Wheat stocks stood at 320.3 lakh tonnes on October 1, 2025 — highest in four years and about 1.5 times required buffer.
- Example: Soyabean area and yield fell in 2025, yet market prices in places like Latur were around ₹4,100/quintal, well below MSP of ₹5,328.
NABARD Grade A 2026
Mentorship & Test Series
471 lessons · ARD master notes · descriptive answers evaluated by hand · daily 11 AM live class.
₹3,500₹6,000
Clarity 4 Sure · c4scourses.in · +91 87086 52887 · compiled 25 September 2026