Clarity 4 Sure · Revision Sheet
March 2025 — exam-ready facts
709 items from 25 days · NABARD Grade A · RBI Grade B · SEBI Grade A
Names, numbers and tables only — the narrative is stripped out. Prints two columns to a page. For the full write-up of any item, open the full version.
Want this month’s PDF on WhatsApp?
Tap below — WhatsApp opens with the message already written. Just press Send and the link arrives straight away.
Get the March 2025 revision sheet on WhatsAppFree live session
NABARD Grade A 2026: what the 2025 cut-offs changed, and the 90-day plan
The 2025 cycle was the toughest on record at every stage. This session reads those numbers properly and turns them into a week-by-week plan for Phase 1.
In 2 days · Sun, 27 Sep at 7:30 PM IST · 75 minutes · free
25days covered
709topics
29topics a day
13hto revise once
1
Cover the right column
Read only the topic name and try to recall the facts before you look.
2
Mark what you missed
Anything you could not recall is what the exam will find first.
3
Write one answer
Pick one topic and write 150 words on it. That is what converts marks.
2.2%India is the 9th largest trading partner to the EU, accounting for 2.2% of the total trade i…
30%Thus, voluntary UN guidelines (such as the 25 year deorbit rule) have maximum 30% compliance…
$1.3 trillionGoal Mobilize $1.3 trillion annually by 2035 for developing nations.
121 millionThe astronauts traveled 121 million miles, completing 4,576 orbits around Earth.
55%In February 2025, China imported around 503,000 barrels per day (bpd) of Venezuelan crude an…
70.15 percentTotal storage across 155 reservoirs (CWC monitored) 180.85 BCM (70.15 percent of total capac…
1.5 millionInsertion in Halo Orbit: January 6, 2024, in Lagrange Point (L1), at 1.5 million km from the…
₹7,523 crore118 Arjun Mark-1A tanks (with major upgrades) ordered for ₹7,523 crore in 2021.
9.2%Recovery rates fell to just 9.2% (2022-23), undermining its purpose.
₹840 croreFinancial Allocation: ₹840 crore allocated for the pilot project. ₹48 crore spent so far.
36%36% of children under five are stunted.
6.3%Growth driven by a 6.3% increase in foreign-born workers in the US labor force in 2022, up f…
Pulled straight out of this month's own facts. If a figure here is new to you, go back and read that item in full.
International Affairs · 71
The India-European Union Free Trade Agreement
- India is the 9th largest trading partner to the EU, accounting for 2.2% of the total trade in the EU 2023.
- Trade Volume in 2023-24 India’s Exports to EU: $75.9 billion (contributes to 17.4% of total exports). India’s Imports from EU: $61.5 billion (9% of total imports).
- Long standing Negotiations Negotiations were first started in 2007 and later were re launched in 2022. Rather than any progress, the negotiations have faced delays due to differences on tariffs, intellectual property, and labor standards.
- Negotiations were first started in 2007 and later were re launched in 2022. Rather than any progress, the negotiations have faced delays due to differences on tariffs, intellectual property, and labor standards.
Trump, Zelenskyy and Vance’s Heated Argument in the Oval Office
- European Intervention France and Britain leaders had to negotiate with the U.S. to convince them to not pull back support from Kyiv.
- France and Britain leaders had to negotiate with the U.S. to convince them to not pull back support from Kyiv.
China's Retaliation After Trump Imposes New Tariffs on Chinese Imports
- The stocks on the onshore CSI 300 Index keep slides down 1.9%, the first weekly loss that has been recorded in a month.
- Hong Kong-listed Chinese shares plummeted to as low as 3.9% today, marking the biggest and most recent biggest single-day fall reaching this month as analysts blamed it on the trade dispute.
- Chinese Stocks Tumble Hong Kong-listed Chinese shares plummeted to as low as 3.9% today, marking the biggest and most recent biggest single-day fall reaching this month as analysts blamed it on the trade dispute. The stocks on the onshore CSI 300 Index keep slides down 1.9%, the first weekly loss that has been recorded in a month.
- Tariffs are timed just prior to China's National People's Congress, at which time President Xi Jinping's team would announce the details of the 2025 economic blueprint.
Trump-Zelensky Clash at White House
- On the Russian Invasion of 2022 Rather than flee, he stayed in Kyiv whilst giving hope to the Ukrainians and galvanizing the Western powers. His audacity displayed leadership reminiscent of that of Churchill.
- Final Judgement The face of resistance, Zelenskyy now encounters a war he cannot win and allies unwilling to fight it for him. The hero of 2022 is now a leader running out of options.
- The face of resistance, Zelenskyy now encounters a war he cannot win and allies unwilling to fight it for him. The hero of 2022 is now a leader running out of options.
- The famous TV actor Volodymyr Zelenskyy, running on the platform of fighting corruption and achieving peace for Ukraine in its conflict with Russia, became the President of Ukraine in the 2019 presidential election.
Firefly Aerospace Blue Ghost Lunar Mission
- As of March 16, 2024 The lander will record a lunar sunset, providing insights into how dust levitates above the moon's surface due to solar radiation. This phenomenon was first observed by Apollo astronaut Eugene Cernan.
- Launch Rideshare Mission: It was carrying a Japanese lunar lander, set on attempting its own moon land in May 2024.
- Rideshare Mission: It was carrying a Japanese lunar lander, set on attempting its own moon land in May 2024.
- On Sunday, March 3, 2024, Firefly Aerospace, a U.S. based company, successfully landed its Blue Ghost Mission 1 spacecraft on the moon. It made the second private mission to reach this goal. Unlike their first private mission in February, which crashed on its side, Blue Ghost made an upright landing. It is a huge technical achievement.
India-Australia Economic Cooperation
- The export markets of India grew by 35% over the last five years, while exports to Australia surged by 66%, the latter nearly double the speed showing complementary economic strengths.
- Education & Skills Australian universities are exporting to India (GIFT City, Noida) to skill 20 million Indians every year.
- Australian universities are exporting to India (GIFT City, Noida) to skill 20 million Indians every year.
- Australia expressed continuing faith in the economic ascent of India, backing its aim to become the third largest global economy by 2030, and supporting India's permanent membership in the United Nations Security Council. Recently, Prime Minister Anthony Albanese of Australia announced the New Roadmap for Australia Economic Engagement with India to expand cooperation in various sectors ranging from trade to investment to geostrategic partnership.
The White House Clash
- 63% of Americans think NATO helps the U.S., down from 66% in 2024 (Chart 4).
- A smaller share of Americans (39%) now believes that European allies ought to increase their defense spending, down from 47% in 2024 (Chart 5).
- Now, more Americans think the U.S. is giving too much aid (30%, up from 27% immediately prior to the November elections).
- 22% feel the U.S. is not providing enough, a 4% increase since the elections.
India-Belgium Defence Ties
- Boosted maritime cooperation in the Indo Pacific is in alignment with the cherished Act East Policy for India and EU Indo Pacific strategy.
U.S.-Taiwan Relations
- Demand for Elevated Defense Spending He demands Taiwan to contribute more to guarding itself and obliges it to inflate the defense budget (currently slightly above 2.5% of GDP).
- He demands Taiwan to contribute more to guarding itself and obliges it to inflate the defense budget (currently slightly above 2.5% of GDP).
- Weapon Deals Through and Political Support Approved arms sales worth USD 10 billion in his final stint. Enacted Taiwan legislative acts including the Taipei Act and the Taiwan Assurance Act.
- Approved arms sales worth USD 10 billion in his final stint.
Strengthening India-U.K. Relations
- Jaishankar and Lammy to deliberate on information technology security initiative birthed during David Lammy's visit to Delhi in July 2024.
India-Belgium Relations
- Belgium's business delegation of 300 members has come to expand economic cooperation.
- 24 MoUs signed across core sectors, which include:
- This JV promotes the employment of major stats in India Belgium defense, coinciding with their most recent global defense cooperation memorandum of understanding which is to be signed by the end of 2025.
- 25 years experience in the defense sector, especially simulators and missile launchers.
Tariffs on Canada, Mexico, and China by Trump
- Domestic U.S. Economic Threats Higher inflation and cost of living. Economic uncertainty may pose a threat to the 2026 elections. Possible loss of access to markets for U.S. exporters.
- a tariff of 25% on imports from Canada and Mexico
- a 10% tariff on energy products imported from Canada
- and an increase of another 10% on tariffs with respect to goods from China
The Blue Ghost
- The mission is being managed through NASA's Commercial Lunar Payload Services (CLPS) program to foster public private partnerships in space.
- The New Moon Race U.S. vs. China: China has ambitious plans for a lunar base by 2030.
- U.S. vs. China: China has ambitious plans for a lunar base by 2030.
- According to NASA's acting administrator, Janet Petro, the U.S. plans to dominate space to maintain its global leadership.
US Strategic Cryptocurrency Reserve
- An actual reserve might act as a precursor to more central banks and sovereign wealth funds adding crypto assets to their portfolios, sustaining price increases over a long term.
- The estimated seized cryptocurrencies in the USA sum up to about $17 billion, while China boasts an approximate $19 billion.
- Trump and his close allies, including Elon Musk, are known to have personal crypto interests, raising conflict of interest concerns.
Trump on Tariffs
- Tariffs on India He attacked India over auto tariffs, which, he claimed, are actually over 100%.
- He attacked India over auto tariffs, which, he claimed, are actually over 100%.
Space Debris
- Soviet satellite Cosmos 954 (1978) crashed with a nuclear reactor into Canada. After years of negotiations, Canada received only $3 million of the $6 million cleanup costs as compensation.
- Updating the 1972 Liability Convention. Create an independent international tribunal with powers of binding enforcement to bring into accountability responsible parties.
- A SpaceX Falcon 9 rocket debris fell in Poland in March 2024, while no clear authority owns responsibility after loss of control.
- Thus, voluntary UN guidelines (such as the 25 year deorbit rule) have maximum 30% compliance, hence weak in enforcement.
India-Australia Defence Cooperation
- Collaboration is taking place under the Comprehensive Strategic Partnership and through trilateral and quadrilateral frameworks such as the QUAD.
- Emphasized the importance of the India-Australia defence partnership.
- Stressed strengthening people-to-people links and engaging with key regional partners.
COP-30
- Goal: Align global behaviors and decisions with the 1.5°C target.
- National Adaptation Plan with 16 sub-programs targeting: Vulnerable urban communities affected by heatwaves and wildfires. Food security systems impacted by extreme weather. Early warning systems for climate disasters.
- COP30 Dates & Location: Scheduled for November 10-21, 2025, in Brazil.
- January 2025 was the warmest on record, with global temperatures 1.75°C above pre-industrial levels.
India-China Relations
- The Xi Jinping-Narendra Modi meeting in Kazan (October 2024) provided strategic guidance for better bilateral ties.
U.S.-Iran Nuclear Tensions
- 2015 JCPOA (Iran Nuclear Deal) Imposed restrictions on Iran’s nuclear program in exchange for sanctions relief. Trump withdrew the U.S. in 2018, reimposing harsh sanctions.
- Trump withdrew the U.S. in 2018, reimposing harsh sanctions.
- Potential rift with Israel: Israel has opposed diplomacy with Iran and conducted airstrikes on Iranian sites.
U.S.-India Free Trade Agreement (FTA)
- Both nations are negotiating a Bilateral Trade Agreement (BTA) by October 2025, which may serve as a precursor to an FTA.
- Commerce Minister Piyush Goyal visited Washington (March 4-6) ahead of the April 2 implementation of U.S. reciprocal tariffs.
- If India agrees to an FTA, it could open doors to greater access to U.S. markets but might also require significant tariff reductions.
OIC's Rejections Against Trump's Gaza Takeover Plan
- OIC's 57 member states called for international and regional financial support for this to happen.
- U.S. envoy Steve Witkoff, however, called it a "good faith first step", probably hinting at future diplomatic engagement.
- Israel has not yet endorsed any long term governance plan about post war Gaza, rendering implementation very difficult.
- The Organisation of Islamic Cooperation (OIC), formerly the Organisation of the Islamic Conference, is an intergovernmental organization founded in 1969.[1] It consists of 57 member states, 48 of which are Muslim-majority.
India-Mauritius Relations
- Shared Colonial Past: Mauritius’ first PM, Sir Seewosagur Ramgoolam, worked with Netaji Subhas Chandra Bose in London (1919-21).
- Nearly 70% of Mauritius’ population is of Indian origin, descended from indentured laborers.
- Mauritius has a new government led by Navinchandra Ramgoolam (Labour Party), who won a landslide victory in November 2024 elections.
- Rapid trade growth: India-Mauritius bilateral trade reached $554 million (2022-23).
India Raises Concerns Over Pakistan’s Investment in NDB
- Pakistan’s Economic Coordination Committee (ECC) has approved a $582 million investment in the New Development Bank (NDB) for a 1.1% stake.
- NDB, founded by BRICS nations (Brazil, Russia, India, China, South Africa) in 2015, finances infrastructure and sustainable development projects.
- In January 2024, during the review of Pakistan’s $3 billion Stand-By Arrangement (SBA), India demanded: Strict monitoring of IMF funds. Checks to prevent misuse for repaying third-country debts or boosting military spending.
- IMF is conducting its first review of a $7 billion bailout granted to Pakistan in 2023. India has previously abstained from voting on Pakistan’s IMF loan requests but took a stricter stance in January 2024. India urged the IMF to ensure "stringent monitoring" of funds provided to Pakistan to prevent diversion towards defense spending or external debt repayment.
India U.S. Bilateral Trade Agreement (BTA)
- Under Article 24.8(b) of GATT, agreements such as these have to eliminate tariffs and barriers on substantially all the trade among them.
- Article 24.5 would permit interim agreements leading to FTAs to be concluded within a reasonable time frame (which would be 10 years at most).
- On February 13, 2025, during Indian Prime Minister Narendra Modi's visit to the United States, the two nations agreed to start negotiations for a Bilateral Trade Agreement (BTA) by fall of 2025.While the details regarding the scope and provisions of the BTA remain vague, it contemplates the BTA to have a multisector perspective rather than to be one primarily oriented toward the liberalization of trade, a feature of the FTA.The agreement would be bilaterally permissible under WTO trade laws, and with respect to India and the U.S., both being members of WTO, especially the General Agreement on Tariffs and Trade (GATT), whatever concerns compliance with WTO trade laws.
- It is necessary for India to make sure that under the BTA only selective tariff reductions are made with the understanding that Indo US tariff structures are transitioning to an FTA.
India on Tariff Reduction Claims by the US
- Trump further stated that foreign goods tariff would be reciprocally applied by the US from April 2, 2025.
- The Indian government denied making any commitment on a tariff reduction in the face of US President Donald Trump's assertion. Discussions continue since India wants an extended time frame until September 2025 to negotiate the Bilateral Trade Agreement (BTA).
- Trade issues for India will, however, not concern immigration and national security effects as with its border sharing neighbors.
- Commerce Secretary Sunil Barthwal and Foreign Secretary Vikram Misri briefed the 30 member panel, headed by Congress MP Shashi Tharoor.
US Economic Outlook & Trump's Trade Policies (2025)
- Optimism in light of the 2024 election: Tax cuts first, tariffs later leading to growth and inflation.
- Since Donald Trump was re elected in January 2025, his policy decisions have swayed and now create uncertainty.
- The August 2025 reading of the New York Federal Reserve's Recession Probability Gauge is the third highest in decades, rivaling the downturns of the 1970s and 1980s.
- Contrast with 2024: In the previous year, the opposite was true increasing yields reflected optimism toward the business policies.
China’s Deflation Crisis
- Consumer Prices Declined: Prices in China fell 0.7% YoY in February, marking the first deflationary period in over a year.
- Prices in China fell 0.7% YoY in February, marking the first deflationary period in over a year.
- Producer Prices Also Dropped: 2.2% decline in producer prices indicates weakening industrial demand.
- 2.2% decline in producer prices indicates weakening industrial demand.
India-Mauritius Relations
- 1998 Ramayan Conference Modi reminisced about his earlier visit to Mauritius for the International Ramayan Conference.
- Girmitiya Struggles Modi recalled the hardships of indentured Indian laborers, who were taken to Mauritius by British colonizers. He noted their resilience, drawing strength from Lord Ram and the Ramcharitmanas.
- Modi recalled the hardships of indentured Indian laborers, who were taken to Mauritius by British colonizers. He noted their resilience, drawing strength from Lord Ram and the Ramcharitmanas.
- OCI Card Expansion Modi personally handed over OCI (Overseas Citizen of India) cards to Ramgoolam and his spouse Veena Ramgoolam. He also announced a special provision for Mauritius allowing OCI status up to the seventh generation of Indian-origin Mauritians.
US-Canada Trade War
- Previous US Tariffs Trump imposed 25% tariffs on all Canadian goods but delayed enforcement. Last week, he exempted USMCA-covered goods after markets reacted negatively.
- Trump imposed 25% tariffs on all Canadian goods but delayed enforcement.
- Upcoming April Tariffs US plans to set "reciprocal" tariffs matching Canada's trade barriers, including its 5% sales tax.
- US plans to set "reciprocal" tariffs matching Canada's trade barriers, including its 5% sales tax.
Brazil’s COP-30
- New initiative ‘Baku to Belem Roadmap to 1.3T’ to enhance climate finance. Brazil proposes an interim stocktake of global climate progress before 2028. Formation of ‘Circle of Presidencies’ to integrate biodiversity, land restoration, and climate action.
- Stocktaking Climate Action Progress The first Global Stocktake (GST) occurred at COP28 Dubai (2023). The next is scheduled for 2028, but Brazil wants an earlier assessment to identify implementation gaps.
- The first Global Stocktake (GST) occurred at COP28 Dubai (2023).
- Goal Mobilize $1.3 trillion annually by 2035 for developing nations.
India-Mauritius Relations
- Aim Strengthen counter piracy efforts, intelligence sharing, and maritime domain awareness in the Western Indian Ocean area.
- Chagos Dispute: India’s Diplomatic Leverage India strengthening Mauritius on the sovereignty of Chagos boosts India's leadership in Indian Ocean governance.
- India strengthening Mauritius on the sovereignty of Chagos boosts India's leadership in Indian Ocean governance.
- Implication Increased credibility of India among small island nations, mostly seeing military bases as evil. Balances Western strategic partnerships and yet shows the regional influence.
Jio Signs Deal to Bring SpaceX's Starlink Internet to India
- Jio will create support processes for Starlink consumers.
- Jio and SpaceX are looking into additional partnership opportunities to improve India's digital infrastructure.
US Tariffs of 25% Extra on Steel & Aluminium: Impact on India
- Additional Duty: 25% on steel & aluminium imports
- Total Exports to US: 5 billion dollars (Steel & Aluminium)
- Exports of Steel Products (Chapter 73): 3 billion dollars (Mainly MSME sector)
- Steel Secretary Sandeep Poundrik A limited impact of such tariffs on large carbon steel producers since their exports to the US are very minimal. Exports of steel to the USA from India are less than 100,000 metric tonnes, that is a very small fraction of the 145 million tonnes produced in 2024.
BRICS Trade & Climate Strategies Amid U.S. Tariff Threats
- Climate Finance Targets Build upon the $300 billion pledged at COP29, aiming for $1.3 trillion in funding. Mobilize multilateral banks & private investors to increase financing.
- Objective: Reduce reliance on the U.S. dollar in trade.
- Impact Strengthens economic ties among BRICS nations. Reduces vulnerability to U.S. economic policies. Supports a more diversified global financial system.
- Supports a more diversified global financial system.
India-France Defence Deals
- Delivery Timeline Begins four years after contract signing (estimated from 2029).
- Begins four years after contract signing (estimated from 2029).
- Status Follow-up to the original six-Scorpene submarine deal between France’s Naval Group and India’s Mazagon Dock Shipbuilders Ltd. (MDL). CCS approval awaited; likely conclusion in April 2025.
- Specifications 22 single-seater Rafale-M (carrier-compatible). 4 twin-seater Rafale trainers (not carrier-compatible).
Rodrigo Duterte’s Arrest
- Timeframe of Investigation: 2011–2019 (before Duterte withdrew the Philippines from ICC membership).
- Lack of Enforcement Power Relies on national governments to execute warrants. Many leaders evade arrest by avoiding ICC member states.
- Many leaders evade arrest by avoiding ICC member states.
- Selective Justice Allegations Criticized for focusing on African warlords and conflict zone leaders. Warrants for Vladimir Putin and Benjamin Netanyahu remain unexecuted.
India-New Zealand Free Trade Agreement (FTA)
- India and New Zealand first began negotiating the Comprehensive Economic Cooperation Agreement (CECA) in April 2010.
- New Zealand Low average tariff of 2.3%. More than 50% of imports already duty-free → Indian goods already have significant market access.
- Low average tariff of 2.3%.
- More than 50% of imports already duty-free → Indian goods already have significant market access.
Baidu’s Ernie X1 AI
- The AI boom contributed to a 26% rise in Baidu’s cloud revenue, showcasing a shift towards AI and cloud-driven growth.
- Financial Reinvestment in AI A $2.1 billion takeover deal freed up $1.6 billion in capital, which Baidu plans to reinvest into AI and cloud infrastructure. This signals a long-term commitment to AI leadership despite challenges in advertising revenue.
- Open-Sourcing Ernie AI from June 30 to attract global developer adoption.
- Baidu claims Ernie 4.5 surpasses OpenAI’s GPT-4.5 in text generation, positioning itself as a strong domestic alternative.
NASA Astronauts’ Long-Awaited Return
- The new crew includes Anne McClain (NASA) and Nichole Ayers (NASA) – Both are military pilots. Takuya Onishi (Japan) and Kirill Peskov (Russia) – Both are former airline pilots.
- Anne McClain (NASA) and Nichole Ayers (NASA) – Both are military pilots.
- Launching Rocket LVM3, LVM3, Next Generation Launch Vehicle (NGLV)
- LVM3, LVM3, Next Generation Launch Vehicle (NGLV)
India Strengthens Defence Ties with US, New Zealand, and Australia
- The 9th edition of defence policy talks focused on maritime domain awareness, information-sharing, and defence industry collaboration.
- India is positioning itself as a central player in regional security by deepening relations with Four of the Five Eyes members.
- Collaboration on defence technologies and supply chains indicates long-term strategic alignment with Western allies, reducing dependency on traditional defence suppliers and increasing self-reliance.
India–New Zealand Strengthen Trade and Digital Cooperation
- Signing of the Authorised Economic Operators Mutual Recognition Arrangement to ease the movement of goods under the Customs Cooperation Arrangement (2024).
- India and New Zealand have revived talks on a Free Trade Agreement (FTA) after a 10-year hiatus, with both leaders committing to expedite negotiations.
- Trade and Economic Engagement India and New Zealand have revived talks on a Free Trade Agreement (FTA) after a 10-year hiatus, with both leaders committing to expedite negotiations. India’s merchandise exports to New Zealand in 2023–24 stood at $535 million, while imports were $335 million, indicating modest but growing bilateral trade. New Zealand ranks 59th in terms of historical FDI in India, with only $87.2 million invested since 2000, highlighting untapped potential. Both leaders emphasized leveraging complementary strengths and addressing mutual concerns for balanced growth in trade and investment.
- India’s merchandise exports to New Zealand in 2023–24 stood at $535 million, while imports were $335 million, indicating modest but growing bilateral trade.
India–U.S. Trade Talks
- Scheme to Promote Manufacturing of Electric Passenger Cars: Offers 15% customs duty for manufacturers setting up production in India Notified in March 2024
- Offers 15% customs duty for manufacturers setting up production in India
- Talks are happening within the framework of Mission 500, aiming to: Increase bilateral trade from $200 billion to $500 billion Finalize a multi-sectoral bilateral trade agreement
- Notified in March 2024
U.S. Withdrawal from the Ukraine War Crimes Prosecution Group
- About ICPA The ICPA was established in 2023 under the Biden administration to pursue legal accountability for Russian leaders including President Vladimir Putin and their allies for crimes of aggression against Ukraine.
- The ICPA was established in 2023 under the Biden administration to pursue legal accountability for Russian leaders including President Vladimir Putin and their allies for crimes of aggression against Ukraine.
- The Trump administration is also reducing the operations of the War Crimes Accountability Team, a unit created in 2022 to support investigations of Russian atrocities in Ukraine.
- The U.S. Justice Department has formally notified European officials of its decision to withdraw from the International Centre for the Prosecution of the Crime of Aggression (ICPA) by the end of March 2025.
U.S. Launches Strikes on Houthis in Yemen
- Since late 2023, the Houthis have attacked over 100 commercial vessels, sinking two and killing four sailors.
- The Red Sea is a critical maritime chokepoint, with about 15% of global trade passing through it, including oil and LNG shipments.
- So far: 2 ships sunk 1 vessel seized 4 crew members killed
- 4 crew members killed
Israel Launches Air Strikes on Gaza
- Evacuation Orders Residents of eastern Gaza (Beit Hanoun and other areas to the south) were being evacuated. It signals preparation for renewed Israeli ground operations.
NASA Astronauts Butch Wilmore and Sunita Williams Return After 286 Days in Space
- The astronauts were originally launched on Boeing’s Starliner capsule on June 5, 2024, for a brief mission. However, technical failures forced Starliner’s early return, leaving the astronauts stranded aboard the International Space Station (ISS).
- Sunita Williams set a record with 62 hours of spacewalking across nine missions, the highest for a female astronaut.
- NASA astronauts Butch Wilmore and Sunita Williams returned to Earth on March 18, 2025, after an extended 286-day mission in space.
- The astronauts traveled 121 million miles, completing 4,576 orbits around Earth.
Global Shifts in Financial Systems and the Rise of Dollar Alternatives
- Recently strengthened by Saudi Arabia’s membership in June 2024.
- Announced at the Kazan Brics Summit (October 2024) by the New Development Bank (NDB).
- Shanghai International Energy Exchange Handles 10.5% of global oil trade; oil futures quoted in Shanghai make up 14.4% of global volume. Compared to Brent (29%) and West Texas Intermediate (56%).
- Handles 10.5% of global oil trade; oil futures quoted in Shanghai make up 14.4% of global volume.
US Building on Strong Security Partnership with India: Tulsi Gabbard
- Collaborative Approach Emphasized “America first is not America alone.” During her visit to New Delhi, Gabbard met Indian counterparts and acknowledged India’s serious security concerns.
- Emphasized “America first is not America alone.”
- Future Opportunities Highlighted the intention to build on the existing strong partnership. Stressed leveraging the new US administration’s momentum for expanding collaboration.
- Highlighted the intention to build on the existing strong partnership.
Chinese UAV Activity Near Okinawa
- Iran-U.S. Disaster (2019) An Iranian missile shot a U.S. surveillance drone out of the sky. But no escalation into military conflict took place.
- Russia-U.S. Scuffle (2023) A MQ 9 Reaper UAV was knocked down by Russia without much consequence from the U.S. The pattern here shows that incidents over UAV often lead to restraint rather than escalation.
- Cost Difference Air to air missiles (as in the case for India in 2019) become unattractive propositions against very low value dolls.
- Air to air missiles (as in the case for India in 2019) become unattractive propositions against very low value dolls.
Israel Conducts Ground Operation in Northern Gaza and Intensifies Air Strikes
- The Israeli Defense Minister, Mr. Katz, warned that civilian evacuation orders in combat areas would soon be reissued.
- Katz further stated that military attacks on Hamas would escalate unless the hostages held for over 17 months are released.
- The escalation of conflict threatens to plunge the region into all out war and reverse any semblance of the fragile peace established only during the two month ceasefire.
Donald Trump Could Reshape the Fed, IMF, and World Bank
- Project 2025, Trump’s second-term roadmap, suggests withdrawing from both the World Bank and IMF.
- US contributions are significant (~20% of IMF resources).
- US contribution is relatively small ($2.8 billion in 2024).
- Federal Reserve (Fed) Trump pressured the Fed to lower interest rates but respected its independence, understanding market sensitivities.
Why the Euro is Rising Against the Dollar
- OECD report (March 17, 2025): US GDP growth projected to slow from 2.8% (2024) → 2.2% (2025) → 1.6% (2026)
- US GDP growth projected to slow from 2.8% (2024) → 2.2% (2025) → 1.6% (2026)
- EU growth projections (OECD): 0.7% (2024) → 1.0% (2025) → 1.2% (2026)
- 0.7% (2024) → 1.0% (2025) → 1.2% (2026)
India-U.S. Bilateral Trade Agreement (BTA)
- U.S. Demands Pressure on India to reduce tariffs on cars and alcohol (current import tariffs on alcohol exceed 100%). Agriculture tariffs are also a key U.S. concern.
- Pressure on India to reduce tariffs on cars and alcohol (current import tariffs on alcohol exceed 100%).
- Both sides are working toward building a "mutually beneficial" trade agreement by late 2025.
- A team of U.S. officials, led by Assistant Trade Representative Brendan Lynch, will visit New Delhi next week. The goal is to discuss and shape the proposed Bilateral Trade Agreement (BTA). Both sides aim to finalize the first tranche of the agreement by Fall 2025.
Global Outstanding Bonds Cross $100 Trillion: OECD
- Outstanding government and corporate bonds worldwide exceeded $100 trillion in 2024, according to the OECD's annual global debt report. Interest costs as a share of global output rose to their highest level in 20 years, reaching 3.3% of GDP among OECD member countries surpassing defence spending. The surge in borrowing costs poses challenges for governments and corporations, forcing them to prioritize productive, growth-oriented investments.
- Central banks have started rate cuts, but interest rates remain well above pre-2022 levels.
- Companies have increasingly used debt for shareholder payouts and refinancing rather than capital investments since 2008.
- Emerging markets (excluding China) face a $10 trillion shortfall by 2050 to meet Paris climate goals.
| Key Indicator | Data Point |
|---|---|
| Total outstanding sovereign & corporate bonds | Exceeded $100 trillion in 2024 (nearly 3x 2007 levels) |
| Government interest spending (OECD members) | 3.3% of GDP — higher than defence spending |
| Sovereign & corporate debt maturing by 2027 | 40% of total debt |
| Share of low-income, high-risk countries’ debt maturing by 2027 | 50% within 3 years; 20% in 2024 alone |
| Dollar-denominated bond borrowing costs | Rose from 4% in 2020 to over 6% in 2024; 8%+ for junk-rated issuers |
India–New Zealand Relations
- Potential for direct flights by 2028
- Despite not being part of the Quad, New Zealand engages with regional partners (Australia, Japan, South Korea)
- Decision to restart free trade talks (current bilateral trade under $2 billion)
- New Zealand’s trade with China valued at $24 billion
Glaciers Losing Ice
- Around 1.1 billion people in mountain communities face immediate impacts due to shrinking glaciers affecting water supply, hydroelectric energy, and agriculture.
- 275,000 glaciers remain globally, along with Antarctic and Greenland ice sheets, holding approximately 70% of the world’s freshwater.
- Between 2000 and 2023, glacier melt caused 18 millimetres of global sea level rise.
- The report was released at the UN headquarters in Geneva alongside the first World Day for Glaciers, calling for global action.
India Imposes Anti-Dumping Duty on Five Chinese Goods
- Soft Ferrite Cores Used in electric vehicles, chargers, and telecom devices. Duty imposed: Up to 35% on CIF (Cost, Insurance, Freight) value. Duration: 5 years.
- Duty imposed: Up to 35% on CIF (Cost, Insurance, Freight) value.
- Duration: 5 years.
- Vacuum Insulated Flasks Duty imposed: $1,732 per tonne. Duration: 5 years.
US Industry Groups Urge Tariff Reduction
- Reduction of 28% GST on non-alcoholic aerated beverages, currently classified as sin/demerit goods, impacting U.S. company profitability.
- Harley-Davidson highlights extreme tariff disparities: 68% duty in the EU, 18% in Brazil, 60% in Thailand, 100% in India, calling for immediate tariff rationalization.
- 68% duty in the EU,
- 18% in Brazil,
Brazil’s COP30
- India is the first bilateral visit for do Lago in his role as COP30 president designate.
- India and Brazil have a longstanding partnership in: BASIC (Brazil, South Africa, India, China) BRICS G20
- Andre Correa do Lago, COP30 president designate and former Brazilian ambassador to India, emphasizes expanding climate discussions beyond the UN climate body into multilateral economic and financial institutions like the World Bank and the IMF.
- Mainstreaming climate action within broader multilateral structures is a top focus area for COP30.
Trump Proposes 25% Tariff on Countries Purchasing Venezuelan Oil
- In February 2025, China imported around 503,000 barrels per day (bpd) of Venezuelan crude and fuel, accounting for 55% of Venezuela’s total exports.
- Trump invoked the 1798 Alien Enemies Act to deport alleged members of the Venezuelan gang Tren de Aragua without waiting for immigration court removal orders.
- Earlier this month, Trump ordered a 30-day wind-down of the license granted to Chevron Corp to operate in Venezuela, with operations set to cease by April 3, 2025.
- Former U.S. President Donald Trump announced a plan to impose a 25% tariff on any country purchasing oil and gas from Venezuela. The tariff would apply to all trade those countries conduct with the United States. The measure is set to take effect from April 2, 2025, as per Trump’s statement on his social media platform.
India-China 33rd WMCC Meeting
- The 33rd meeting of the Working Mechanism for Consultation and Coordination (WMCC) on India-China Border Affairs was held in Beijing.
- Both countries agreed to make substantial preparations for the next Special Representatives (SR) meeting, to be hosted in India later in 2025.
- Measures were discussed to implement decisions from the 23rd SR meeting (held in December 2024 in Beijing).
- In November 2024, both nations completed disengagement at Demchok and Depsang in eastern Ladakh, returning to pre-April 2020 status quo.
India and Singapore Sign Letter of Intent for Green and Digital Shipping Corridor
- Identifying key stakeholders in both countries to drive innovation and participation.
- The cooperation will eventually be formalized through a Memorandum of Understanding (MoU).
- Enhance bilateral collaboration between India and Singapore’s maritime sectors.
Russia and Ukraine Agree to Cease Black Sea
- The U.S. government announced that it will assist in restoring Russia’s access to global markets for agricultural and fertilizer exports, marking the first direct concession in return for Russia’s cooperation.
- Russia specifically demands the reconnection of the Russian Agricultural Bank and related financial institutions to the SWIFT international payment system.
U.S. Intelligence Report Identifies China as Primary Global Threat
- Besides state actors, the report highlights concerns about transnational criminals, including: Mexican drug cartels. Islamic extremist groups.
- The China-Russia alliance is identified as the "most persistent" threat to U.S. influence.
- The report links China’s rise in global power to the U.S. strategic pivot to the Asia-Pacific region under Barack Obama.
- The report highlights increasing coordination among: China Russia Iran North Korea
India-New Zealand Free Trade Agreement (FTA)
- Tariff disparities: New Zealand’s average import tariff is 2.3% (many duty-free items). India has higher tariffs, making a traditional FTA less attractive.
- New Zealand’s average import tariff is 2.3% (many duty-free items).
- Wine tariffs: India imposes 150% import duty on wine (one of the highest globally). New Zealand seeks reductions, possibly following India-Australia FTA's phased model.
- India imposes 150% import duty on wine (one of the highest globally).
Trump Unveils 25% Auto Tariff, Escalating Trade War
- U.S. President Donald Trump announced a 25% tariff on imported vehicles, expanding an ongoing global trade war. The tariffs, effective April 3, 2025, are expected to impact key trading partners, raise vehicle prices, and provoke international retaliation.
- The U.S. imported $474 billion in automotive products in 2024.
- The biggest exporters to the U.S. are Mexico, Japan, South Korea, Canada, and Germany.
- Aims to revive U.S. manufacturing and reduce reliance on foreign imports.
India-Myanmar Free Movement Regime (FMR)
- Union Home Minister Amit Shah announced in February 2024 that the FMR would be scrapped, citing security concerns.
- The Free Movement Regime (FMR) along the India-Myanmar border (1,653 km) allows unrestricted movement of people up to 16 km on either side.
- The 16 km movement limit is rarely enforced, allowing unregulated trade and migration.
- Terrain & Logistics: A 1,700 km fence is impractical due to difficult terrain and dense forests.
India-US Bilateral Trade Agreement (BTA)
- The goal is to finalize the framework of the deal by month-end, aiming for completion by fall 2024.
- The US is concerned about India’s data localisation norms, which mandate storing data within the country under the Digital Personal Data Protection (DPDP) Act.
- Talks are expected to conclude by the end of the month, with an ambitious deadline set for finalizing the trade agreement by fall 2024.
- India and the US are engaging in intense discussions over the first phase of the Bilateral Trade Agreement (BTA).
India Unlikely to Opt for Across-the-Board Tariff Reduction
- Tariff Differential: India imposes 6.5% higher tariffs on U.S. goods than vice versa, the highest among emerging economies (Nomura report).
- Potential U.S. Tariff Increase: If the U.S. imposes reciprocal tariffs, India's average import tariff could rise to 15.7% from 2.7%, affecting almost all exports.
- U.S. Share in India's Exports: 18% of India’s merchandise exports go to the U.S.
- India’s Share in U.S. Imports: Just 1.6% of total U.S. imports come from India.
US Reciprocal Tariffs
- US Tariff Hikes: 25% import duties on steel & aluminum (March 12, 2025). 25% tariffs on automobiles (effective April 3, 2025).
- 25% import duties on steel & aluminum (March 12, 2025).
- 25% tariffs on automobiles (effective April 3, 2025).
- Countries Affected: China, Mexico, and Canada — accounting for 50% of US imports (~$3 trillion).
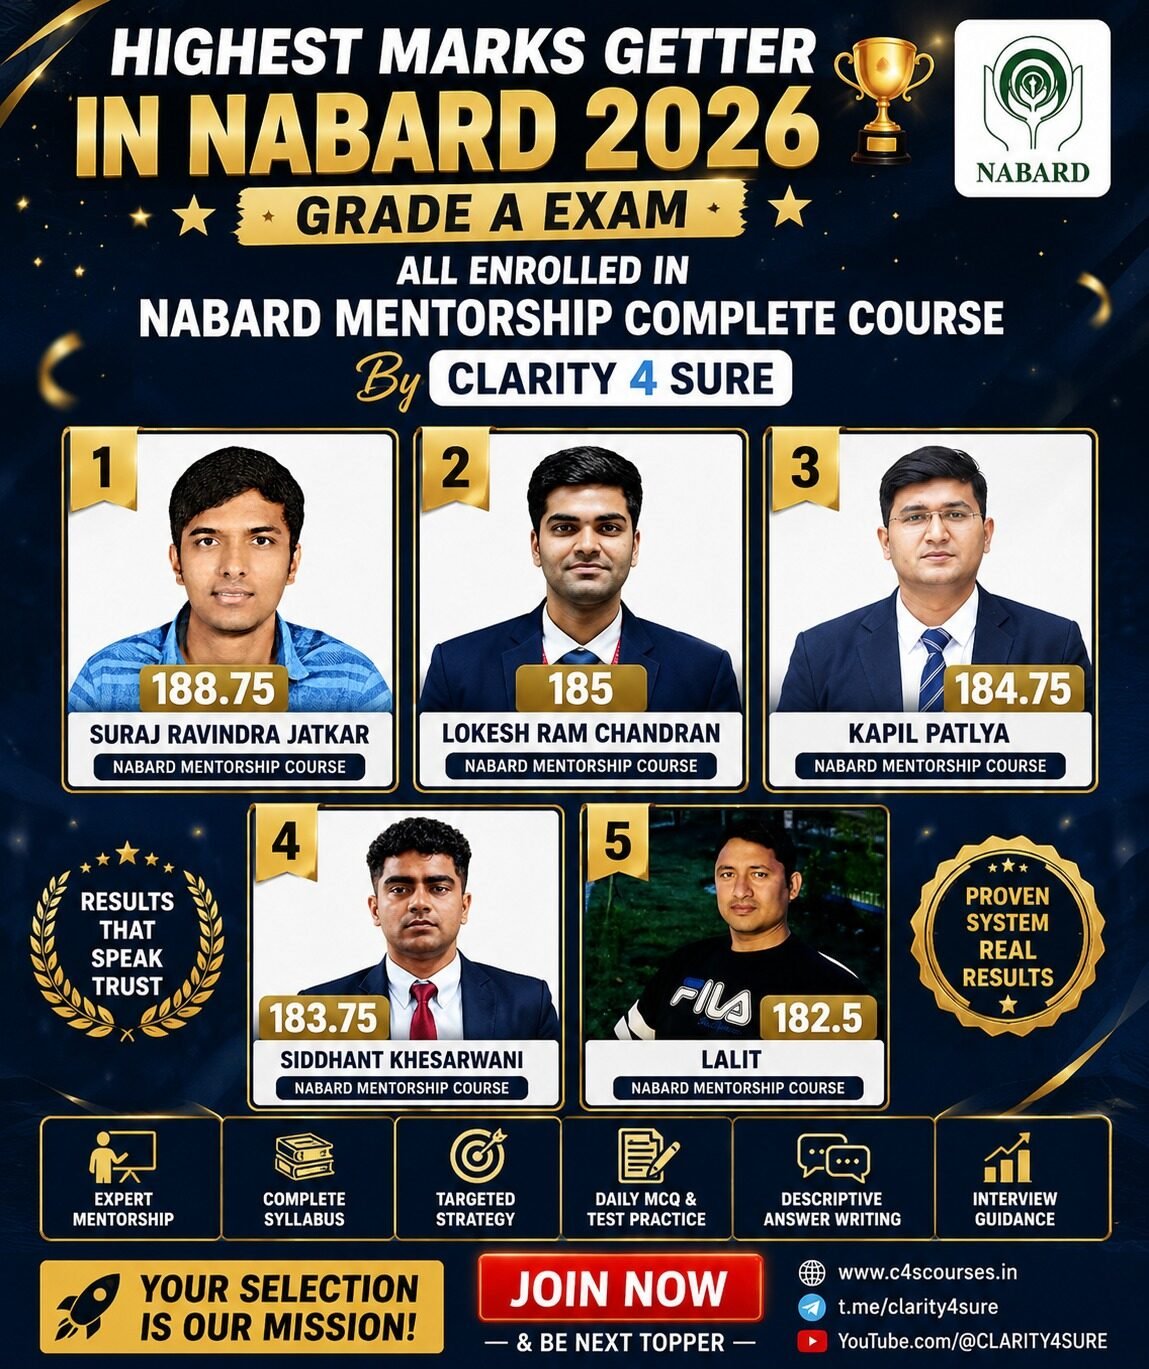
Results that speak
The six highest scorers in NABARD Grade A 2026 were all in one classroom
Every one of them was enrolled in the NABARD Mentorship Complete Course at Clarity 4 Sure. The same descriptive training and the same current affairs notes you are reading now.
- 1Suraj Ravindra Jatkar188.75
- 2Lokesh Ram Chandran185
- 3Vivek Kumar185
- 4Kapil Patlya184.75
- 5Siddhant Khesarwani183.75
- 6Lalit182.5
National Affairs · 138
Aditya L1 Captures Photo of first Solar Flare Kernel
- Unprecedented Resolution The first ever observation of solar flare brightening in the Near Ultraviolet (NUV) range (200-400 nm).
- The first ever observation of solar flare brightening in the Near Ultraviolet (NUV) range (200-400 nm).
- Launch Date: September 2, 2023
- Positioning Orbital: Aditya L1 was really placed in a halo orbit around the Earth Sun Lagrange Point L1 on January 6, 2024.
Wetlands Conservation in India
- Global Decline 50% of wetlands lost since 1900. 35% loss of wetland surface area (1970 2015). 81% decline of inland wetland species and 36% of coastal/marine species.
- 50% of wetlands lost since 1900.
- 35% loss of wetland surface area (1970 2015).
- Ramsar COP14 (2022) Integrated wetland conservation into Sustainable Development Goals (SDGs), Global Biodiversity Targets and Climate Change frameworks. Stress the requirement for wetland protection beyond stand alone initiatives.
India's Warmer March Prediction
- Indicate that wheat harvest in India would be of great importance by 2025 after three consecutive years of poor harvests.
- Possible policy shift Reduce import duty or remove the 40 percent import tax and thus allow private traders to import wheat as domestic production does not suffice. Banning wheat exports since 2022 may continue into the next fiscal year.
- Reduce import duty or remove the 40 percent import tax and thus allow private traders to import wheat as domestic production does not suffice.
- Total storage across 155 reservoirs (CWC monitored) 180.85 BCM (70.15 percent of total capacity).
SEBI Launches Bond Central
- To assist investors and market participants to make informed decisions.
- Better Access: Investors can have access to all bond-related data together.
Tuhin Kanta Pandey Takes Charge as the SEBI Chief
- Tuhin Kanta Pandey appointed as the SEBI Chairman for three years, taking the reins from Madhabi Puri Buch.Previously:DIPAM Secretary (2019 2024), responsible for India's overall disinvestment strategy. Revenue Secretary in the Ministry of Finance prior to SEBI. Holds a Master's in Economics from Panjab University and an MBA from the University of Birmingham.
- Revival of the Market and IPOs Confidence boosters will be key as sell offs increase in the markets. Support IPO's and near capital market fundraising.
- Confidence boosters will be key as sell offs increase in the markets.
- Transparency & Conflict of Interest Management Disclosing personal investments to avoid any chance of perceived bias.
RBI’s Auction on Dollar Rupee Swap of $10 Billion
- Patterned on Banking system liquidity deficit: ₹1.81 trillion (now 11th consecutive week).
- Rupee depreciation: Closed at ₹87.51/$ compared with ₹87.20 at the previous session.
- Key resistance levels: Downward supports for rupee are at ₹86.6 and resistance is at ₹87.5.
- Dollar Index: Surged to 107.37 from 106.62, making a mark on the currencies across the globe.
IRDAI Permits Insurers to Use Derivatives in Equities for Hedging Purposes.
- Corporate Governance A Hedging Policy is thus mandated for approval by the Board. Risk Management Policy Framework, IT Infrastructure, and Conduct of Periodic Audits among the foremost. Contracts will protect the interest of policyholders.
- A Hedging Policy is thus mandated for approval by the Board. Risk Management Policy Framework, IT Infrastructure, and Conduct of Periodic Audits among the foremost. Contracts will protect the interest of policyholders.
- Increased advantage for life insurers because the larger exposure to equity markets (ULIPs primarily).
- Already dealing with fixed income derivatives (FRAs, Interest Rate Swaps, Credit Default Swaps as Protection Buyers).
UGC Draft Regulations, 2025
- Definition of discrimination in 2012 was 'distinction, exclusion, limitation or preference' affecting equality of treatment, while this draft extends the extended protection to all "stakeholders" and not just students.
- The draft regulations of 2025 broaden the meaning of discrimination and provide for stricter enforcement. They would still require clarity and coverage about anti-reservation bias in universities.
- Public consultation The draft has been open for public feedback until March 28, 2025, by the UGC.
- The draft has been open for public feedback until March 28, 2025, by the UGC.
Maple Syrup Urine Disease (MSUD)
- Cow Calf Experiment A newborn calf with MSUD received the therapy and grew normally for two years. The animal was able to transition to a high protein diet, unlike untreated MSUD cases.
- A newborn calf with MSUD received the therapy and grew normally for two years. The animal was able to transition to a high protein diet, unlike untreated MSUD cases.
Sources and Health Effects of PM2.5 Pollution in Northern India
- PM2.5 oxidative potential has much to do with health risk indicators mainly due to organic aerosols from inefficient biomass and fossil fuel burning.
- By the same measure, traffic emissions contribute only 40% to organic aerosols at urban roadside locations.
- Hitherto, the toxicity of PM2.5 was five times worse in India compared to that of Chinese and European cities.
- PM2.5, or fine particulate matter, is a type of air pollution that can cause serious health problems. It's made up of tiny solid particles and liquid droplets that are 2.5 micrometers or less in diameter.
Advocates (Amendment) Bill, 2025
- In Section 45B, the BCI was permitted to address disciplinary complaints at a national scale and was empowered to terminate the practice of lawyers at its mere discretion.
- Section 48B endowed the BCI with powers to abrogate the State bar councils when they are unable to perform their functions in a satisfactory manner.
- Section 35 A Forbade advocates and bar associations from striking or boycotting courts, making it such violations would constitute misconduct and cause disciplinary proceedings to ensue.
- Section 49B Dictated that the Central Government could issue binding directions to the BCI.
ERONET (Electoral Roll Management System)
- ERONET is a web-based system for Electoral officials, in 14 languages and 11 scripts, to handle all processes pertaining to Form 6/6A/7/8/8A/001.
- It allows registration, migration, and deletion of the names of voters in order to help keep a cleaner and more transparent electoral roll.
Gulf Coast Communities in Kerala Rebel Against Offshore Mining Plans
- In particular, geological surveys have identified substantial mineral deposits within 745 million tonnes of construction grade sand offshore of Kerala. Lime mud, heavy mineral placers, and polymetallic nodules in excess of the other offshore regions.
- Coastal communities in Kerala have been agitating against the Centre's offshore mining plans, fearing destruction to marine ecosystems and loss of livelihoods. The agitation gained momentum after the 2023 amendment to the Offshore Areas Mineral (Development and Regulation) Act, 2002, which opened offshore mining to private players.The Kerala Fisheries Coordination Committee has been formed to lead the resistance, with a Parliament march planned for March 12.
- Tranche 1 of the auctions includes 13 offshore blocks Three blocks of construction sand offshore of Kerala. Three blocks of lime mud offshore of Gujarat. Seven blocks of polymetallic nodules offshore of the Great Nicobar Island. The mining zone in Kerala is Kollam Parappu (Quilon Bank), a key fishing hub and a marine biodiversity hotspot.
- The mining zone in Kerala is Kollam Parappu (Quilon Bank), a key fishing hub and a marine biodiversity hotspot.
Einstein Ring
- The Euclid space mission, launched by European Space Agency (ESA), discovered the Einstein ring in the galaxy NGC 6505 in September 2023.
- This galaxy sits at a relatively close distance from Earth at 590 million light years.
- The lensed object being viewed through NGC 6505 is a galaxy that lies 4.5 billion light years away.
- Einstein rings act as a gigantic lens for far off galaxies to aid astronomers in their hunt for faint objects.
Cheetahs Vulnerability
- This faces no new issue In fact, during the very first meeting of the CPSC convened on May 30, 2023, the very committee had concluded that prey augmentation must be a continuing effort.
- In fact, during the very first meeting of the CPSC convened on May 30, 2023, the very committee had concluded that prey augmentation must be a continuing effort.
- The Cheetah Project Steering Committee (CPSC) has raised concerns regarding the insufficient prey bounty available for cheetahs on various occasions. In its spur 10th meeting numbering August 23, 2024, the committee noted that:
- Eight cheetahs from Namibia on September 17, 2022
The Sacred Orans
- There is protection, but there are exceptions within the Forest Conservation Amendment Act, 2023 even for diversion of forest land for zoos, safaris and ecotourism-related activities.
- In pursuance of the judgment of the Supreme Court of India, all sacred forests in Rajasthan known as orans were, from December 2024, protected under a High Court order recognising the socio-ecological and cultural significance of orans in T. N. Godavarman Thirumulpad v. Union of India. The ruling brought orans under the purview of the biodiversity-related laws, but the issue remains whether formalisation undermines community governance.
- The ecological and economic functions they serve, among others, include: Support biodiversity Enhance sources of water by trapping runoff and raising underground water levels Community efforts at watershed management
- Support biodiversity
Cities Coalition for Circularity (C-3)
- India's leadership in advocating a Pro, Planet and People (P3) approach.
- ₹1,800 crore in agreements were announced under the initiative.
- The Regional 3R and Circular Economy Forum in Asia and the Pacific was inaugurated in 2009 with the objective of promoting: Sustainable waste management Resource efficiency Circular economy policies
- India launched the Cities Coalition for Circularity C-3, a multi national platform for city to city collaboration, knowledge sharing, and partnership with the private sector in support of sustainable urban development.
Gangetic Dolphins First Survey
- This survey is the first step undertaken in scientific conservation efforts, covering a huge expanse of river stretches that totals 8,507 km.
- Main stem Ganga: 3,275 dolphins
- Tributaries of Ganga: 2,414 dolphins
- Main stem Brahmaputra: 584 dolphins
Aditya-L1 Mission Update
- Launch Date: September 2, 2023 using PSLV C 57.
- Insertion in Halo Orbit: January 6, 2024, in Lagrange Point (L1), at 1.5 million km from the Earth toward the Sun.
- The Indian Space and Research Association has announced the second set of scientific data released by ISRO's solar observation mission Aditya L1, providing crucial information regarding the Sun's photosphere, chromosphere, and corona, as well as in situ particle and magnetic field measurements at the first Earth Sun Lagrange Point (L1).
- Current Status: It has been in its third revolution around L1, continuously observing the Sun.
Bose Metal
- Superconductors would conduct current without any resistance (e.g., zinc at 272.3ºC) due to the fact that they host Cooper pairs, which are two electrons bound together at low energy states.
- So the older theory has it that, at 0K, the metals can either be very good insulators (zero conductivity) or good superconductors (infinite conductivity).
- Cooper pairs form (like in superconductors).
- Results: Cooper pairs formed. Hall resistance was zero (which proved that Cooper pairs were indeed charge carriers). No superconducting state occurred.
Obesity Crisis in India
- Balancing Overnutrition & Undernutrition India is paradoxical: 180 million Indians suffer from obesity while 35% of under five children are malnourished (NHFS 5, 2019 21).
- India is paradoxical: 180 million Indians suffer from obesity while 35% of under five children are malnourished (NHFS 5, 2019 21).
- Younger Generations Affected More: People are gaining weight faster than the earlier generation. Earlier onset of obesity is more likely to have higher boluses of Type 2 diabetes, increased high blood pressure, cardiovascular illnesses, and cancers.
- Earlier onset of obesity is more likely to have higher boluses of Type 2 diabetes, increased high blood pressure, cardiovascular illnesses, and cancers.
Offshore Mining
- The amended Offshore Areas Mineral (Development and Regulation) Act, 2002 allows private people to access strategic deep sea minerals.
- Under the 2023 amendment of the Act, the Union Ministry of Mines can auction deep sea mineral blocks.
- Threat to National Security The amended Offshore Areas Mineral (Development and Regulation) Act, 2002 allows private people to access strategic deep sea minerals. The aspect of security risk is raised from the government of the State due to the control of important resources.
- Worries over Central Government Policy Under the 2023 amendment of the Act, the Union Ministry of Mines can auction deep sea mineral blocks. Kerala clearly states that this sort of measure is taken without proper consultation and disregard to the interests of the State.
Issues Related To Income Tax Bill, 2025
- The basic philosophy of taxation remains unchanged, giving the impression of a revamped version of the 1961 Act.
- The 1961 Act has seen several court decisions interpreting different provisions, thereby providing clarity to taxpayers.
- Cross referencing of older legislation (for example, designing "income" by reference to the 1961 Act) negates any reason for a new statute.
- The Income Tax Bill, 2025, introduced in Parliament, seeks to repeal the Income Tax Act, 1961, ostensibly to put in simple tax laws for easier compliance and administration. But, while the Bill brings some structural changes, it does not tackle issues that are more complex, in fact, in some areas, it further empowers the government by expanding the contours of its power.
Delimitation Debate in India
- The number of Lok Sabha seats was stopped at 543, as per the outcome of the 1971 Census, when the population of India was counted at 54.8 crore. This freeze aimed for population control enhancement, revised after the completion of the first Census after 2026.
- The above could transform the representation of southern states from 24% into near 19%, creating a reduced voice in national policymaking.
- It has had 543 MPs in India over the last five decades, whereas the population spoke from 55 crores to 145 crores.
- India, which expects its population to peak at 165-170 crore and will subsequently decline, should retain this number.
Discovery of largest Buddha head in Odisha’s Ratnagiri
- Buddha Sculpture A large Buddha head, palms, and fingers from what is likely a meditating Buddha statue, Khondalite in stone.
- A large Buddha head, palms, and fingers from what is likely a meditating Buddha statue, Khondalite in stone.
Supreme Court Ruling on Domicile Based Medical Reservations
- Any inconsistencies in merit assessment were exposed in 2023 when the NEET PG qualifying percentile was brought down to zero by the National Medical Commission (NMC) for filling vacant seats.
- Earlier Supreme Court cases(Jagdish Saran (1982), Pradeep Jain (1984), Neil Aurelio Nunes (2022), Om Rathod (2024))have ruled that: Merit must be defined in a social context. What matters are public service outcomes and not exam results. Domicile quotas would ensure that communities get access to healthcare services, in the context of social justice.
- Domicile quotas ensure that trained doctors remain in their States, which are being used to address many chronic specialist shortages.
- The moment the states feel secure about the local specialist workforce, they may downgrade their financial commitment into medical education, and this will worsen their healthcare infrastructure.
Supreme Court Calls for Regulation of Digital Humour
- Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021 Provides an age based classification of contents. Has a grievance redressal mechanism as follows: Platform level complaint handling. Self regulatory body. Government inter departmental committee.
- In India, Article 19(1)(a) of the Constitution guarantees freedom of speech and expression.
- This includes the right to express oneself through speech, writing, pictures, movies, banners, and more.
- Universal reach of the Internet does not allow justification on universal jurisdiction where one complaint can cause widespread legal consequences.
Quantum Computing and National Security
- Current Global Investments in Quantum Computing China: $15 billion US: $5 billion Europe: $1.2 billion India: $0.75 billion (Lagging far behind global leaders) Investment Rise in 2024: 50 deals of $1.5 billion invested (2x YoY growth).
- India: $0.75 billion (Lagging far behind global leaders)
- Investment Rise in 2024: 50 deals of $1.5 billion invested (2x YoY growth).
- China: $15 billion
U.S.-India Relations Under Trump: A Detailed Analysis
- Historically, the United States was seen as a member of the Western bloc (post 1945), but under Trump, its self perception is taking the shape of a country first approach, defined against the backdrop of traditional Western alliances.
- U.S. Moving Toward a Multipolar World Jaishankar noted that the policies of the Trump administration reflect a shift toward multipolarity that favors India from the standpoint of its global positioning. Historically, the United States was seen as a member of the Western bloc (post 1945), but under Trump, its self perception is taking the shape of a country first approach, defined against the backdrop of traditional Western alliances.
- Jaishankar noted that the policies of the Trump administration reflect a shift toward multipolarity that favors India from the standpoint of its global positioning.
- Changes in the Trump administration's policies thus open new avenues of Indo U.S. collaboration across a wide array of sectors.
Balancing Federal Principles & Democratic Representation
- Since the last delimitation exercise (2002-2008), India's electorate has grown by 45%, leading to significant malapportionment in many constituencies.
- Example: Bangalore North (3.2 million voters) vs. Udupi Chikmagalur (1.6 million voters)—showcasing disproportionate voter representation within Karnataka itself.
- CM Stalin warns that using 2026 Census data could lead to an “indelible injustice” against progressive States.
- Southern States, which have successfully controlled population growth, fear a loss of Lok Sabha seats if representation is strictly based on numbers.
INSV Tarini
- Background INSV Tarini is the Indian Navy’s second sailboat. Built at Aquarius Shipyard Goa. Commissioned for operation on 18 February 2017 after intensive sea trials.
- Commissioned for operation on 18 February 2017 after intensive sea trials.
- Departure: March 5, 9:10 a.m. (local time) from Port Stanley, Falkland Islands
- Sailors: Lieutenant Commander Dilna K. and Lieutenant Commander Roopa of the Indian Navy
AI Kosha: India’s New AI Dataset Platform
- IndiaAI Mission: A government-backed initiative with a budget of ₹10,370 crore
- Proposal (2020): Access to non-personal data from private firms (e.g., ride-sharing traffic data) for start-ups & policymaking
- Past Efforts to Leverage Non-Personal Data: 2018 Committee led by Kris Gopalakrishnan explored mandatory data-sharing by private firms Proposal (2020): Access to non-personal data from private firms (e.g., ride-sharing traffic data) for start-ups & policymaking Pushback from private sector: Concerns over competition and proprietary data protection
- 2018 Committee led by Kris Gopalakrishnan explored mandatory data-sharing by private firms
India Semiconductor Mission (ISM) Phase 2
- CDIL Semiconductors (India) & Infineon Technologies (Germany) have signed an MoU to explore collaboration opportunities in India's semiconductor market.
- Key Aspects of the Partnership: Infineon will supply bare die wafers to CDIL. CDIL will package and produce discrete & module semiconductor products for Indian customers. Focus areas include e-mobility, renewable energy, and energy-efficient appliances.
- Infineon will supply bare die wafers to CDIL.
- CDIL will package and produce discrete & module semiconductor products for Indian customers.
Duplicate Voter ID Issue
- First Appeal: File a complaint with the District Magistrate/District Collector/Executive Magistrate under Section 24(a) of the Representation of the People Act, 1950.
- It explained that since 2000, some Electoral Registration Officers (EROs) had mistakenly used the wrong EPIC series, leading to duplicate numbers across states.
- The EPIC (Electors Photo Identification Card) is a 10-digit unique number issued by the EC to every voter.
- The EC conducted a sample inquiry of over 100 electors, concluding that those with duplicate EPIC numbers were still genuine voters.
Deciphering the Indus Valley Script
- However, if the Indus script is Sanskrit-based and dates back to 4,000 BCE, this suggests Sanskrit was already present in the subcontinent thousands of years earlier.
- The widely accepted Aryan migration theory states that Sanskrit entered India around 1,500 BCE via steppe migrants.
- This would disprove the idea that Sanskrit was imposed by invaders and instead point to indigenous linguistic and cultural continuity.
- A major argument supporting a historical north-south divide is that northern Indians descend from Aryans, while southerners descend from the original Dravidian inhabitants of the IVC.
India’s Defence Deals
- Indigenous tank projects: 118 Arjun Mark-1A tanks (with major upgrades) ordered for ₹7,523 crore in 2021. 354 light tanks under Project Zorawar (₹17,500 crore) to enhance high-altitude warfare capabilities, especially for the Ladakh standoff with China.
- 118 Arjun Mark-1A tanks (with major upgrades) ordered for ₹7,523 crore in 2021.
- Tropex 2024 Concludes: A three-month-long naval exercise tested India’s maritime war-fighting readiness. Participation: 65-70 warships 10 submarines 80+ aircraft and helicopters Joint participation from the Army, IAF, and Coast Guard
- 354 light tanks under Project Zorawar (₹17,500 crore) to enhance high-altitude warfare capabilities, especially for the Ladakh standoff with China.
Geo Mapping of Plantations in Kerala by the Rubber Board
- EUDR Compliance This requires that all commodities that go into the EU must be deforestation free (post Dec. 31, 2020). Rubber must be derived lawfully and according to environmental sustainability.
- This requires that all commodities that go into the EU must be deforestation free (post Dec. 31, 2020).
- Objective Better and improved market access. It verifies the material under the certification towards Indian Sustainable Natural Rubber (iSNR) framework.
- Implementation Phase 1: 10 of the major rubber growing districts of Kerala. Other regions: Will be covered after this. Partnered by: Trayambu Tech Solutions Pvt. Ltd., Hyderabad.
TB Elimination Campaign
- The National TB Prevalence Survey (2019-2021) estimates that 42.6% of TB cases might have been missed without an X ray, thus making it a very useful tool.
- Given India’s high TB burden, eliminating TB by 2025—as envisioned by Prime Minister Narendra Modi—appears overly ambitious without sustained and improved interventions.
- The government’s assumption that all 3.5 lakh cases in intervention districts were detected solely due to the campaign is dubious.
- Though the campaign claimed a new strategy to early detection using chest X rays, only 3.8 lakh of the 10 crore (100 million) people screened (3.8%) were reported to have undergone an X ray.
River Dolphin Conservation in India
- Yangtze river dolphin (China; presumed extinct since 2007).
- Despite their legal protection under the Wildlife Protection Act (1972), river dolphins in India face multiple anthropogenic (human-induced) threats.
- Project Dolphin (Launched 2020): Aims to protect river dolphins through habitat conservation and awareness campaigns.
- Ganges Dolphin Conservation Action Plan (2010-2020): Focused on reducing pollution, promoting eco-tourism, and improving research.
The IndiaAI Mission
- Aim: Creating a national dataset platform for supplying quality Indian data, non personal, for the purpose of conducting AI research.
- Aim: Provide GPU access to startups and researchers who cannot afford costly AI hardware for themselves.
- Current Progress: 14,000 GPUs deployed through empaneled data centers; expansion is planned quarterly.
- The IndiaAI Mission, worth ₹10,371.92 crore, aims at driving India's artificial intelligence development and reducing the dependence on foreign AI models through indigenous capacity building. In this sense, the mission has aims in compute infrastructure, datasets, model development, safety, and skill building. It is a mission, too, that stands of great importance in light of rapid advances in AI technology across the globe and a rapidly emerging necessity for developing culturally and linguistically relevant AI tools for India's diversity.
Assessment of the IndiaAI Mission
| Initiative | Progress | Challenges | Strategic Impact |
|---|---|---|---|
| AI Kosha (Data Infrastructure) | Launched, initial datasets | Scaling high-quality, diverse datasets | Enables AI models adapted to India |
| Common Compute (GPU Access) | 14,000 GPUs deployed | Allocation, expansion amid global shortages | Lowers barriers for AI startups |
| AI Safety Institute | Planned | No clear regulatory framework yet | Essential for responsible AI use |
| Indigenous AI Models | 67 proposals received | Costly, high expertise required | Strengthens AI independence |
| Innovation & Skills Development | AI labs planned in smaller cities | Talent retention, industry-academia gap | Expands India’s AI talent pool |
Centre's Special Assistance Scheme
- Total Revised Allocation (FY25): ₹1.25 trillion (originally ₹1.5 trillion).
- Approved Amount (First 10 months): ₹1.22 trillion (~97% of allocation).
- ₹55,000 crore: Allocated based on states' share of central taxes & duties.
- ₹95,000 crore: Linked to reform implementation upon such reforms as: Iconic tourism destination development. Vehicle scrappage incentives. Development of industry. Advancement of NCR development.
India’s Semiconductor
- Government Announcement: India’s first domestically manufactured semiconductor chip will roll out in 2025. Aim: Reduce import dependency and boost domestic production.
- India’s first domestically manufactured semiconductor chip will roll out in 2025.
- FY23: Budgeted ₹200 crore → Spent ₹13 crore.
- FY24: Budgeted ₹3,000 crore → Revised ₹1,503 crore → Spent ₹681 crore.
India's Startup Boom
- 90% of startups fail globally—India is no exception.
- India is the world’s third-largest startup ecosystem (after the US and China), with over 120,000 startups registered in the last decade.
- Incubation centers across IITs, IIMs, and Nasscom are fostering innovation.
- Atal Tinkering Labs in 10,000 schools are encouraging early innovation among students.
Bridging the Gender Gap in Entrepreneurship and Finance
- Male entrepreneurs raised $10.8 billion for tech startups in 2004, while women-founded firms secured only $1 billion.
- Only 19.2% of Indian women participated in the workforce in 2022 (ILO data).
- Pradhan Mantri Mudra Yojana (PMMY): 68% of loans sanctioned to women entrepreneurs. 77.7% of Stand Up India beneficiaries are women. However, while women hold 67.92% of Mudra loan accounts, they receive only 44.46% of total credit sanctioned.
- Pradhan Mantri Jan Dhan Yojana (PMJDY): 303.7 million of 545.8 million bank accounts belong to women (as of January 2025).
India: The Prime Target for Hacktivist Attacks in 2024
- 2024 Dark Web statistics: 248.9 crore unique email addresses leaked and sold.
- India leads globally in hacktivist attacks (13%), followed by Israel (7%).
- In the Asia-Pacific (APAC) region, India alone accounted for 49.3% of such attacks, with Indonesia trailing at 14%.
- 248.9 crore unique email addresses leaked and sold.
Obesity in India
- Consumer Protection Act, 2019 Defines ‘misleading ads’ but does not compel nutritional information to be declared in food ads.
- An analysis of the earnings data for salaried workers, casual labourers, and self-employed persons from Periodic Labour Force Survey (PLFS) reports shows that when adjusted for inflation, wages for salaried workers in India have stagnated since 2019.
- These UPFs continue to be rated 'healthy' 2 Stars for Biscuits (high fat, sugar, salt). 2 Stars for Soft Drinks (high sugar). 3 Stars for Cornflakes (high sugar, sodium).
- 2 Stars for Biscuits (high fat, sugar, salt).
Global Arms Trade Trends (2020-2024): SIPRI Report
- China dropped out of the top 10 arms importers for the first time since 1990-94, reflecting its growing domestic defense industry.
- Top 3 Arms Exporters (2020-24): United States (43% of global exports) – Maintained dominance. France (9.6%) – Overtook Russia as the second-largest exporter. Russia (7.8%) – Significant decline in global share.
- Received 8.8% of global arms imports in 2020-24.
- Ukraine, involved in a war with Russia for the past four years, was the largest importer of major arms in the world in the 2020-24 period, clocking a nearly hundredfold rise in imports compared with the figures for 2015-19.
Ultra-High Energy Particles in Space
- December 17, 2017 Event: Scientists detected electrons in the foreshock region reaching 500 keV of energy (~86% the speed of light). A huge leap from the typical 1 keV energy levels in that region.
- Scientists detected electrons in the foreshock region reaching 500 keV of energy (~86% the speed of light).
- Previously, scientists struggled to explain how electrons initially accelerate to 50% of the speed of light, a necessary condition for further acceleration by diffusive shock acceleration.
- Researchers from Johns Hopkins University (U.S.) and Northumbria University (U.K.) found that collisionless shock waves act as powerful cosmic particle accelerators.
The Challenges of Tribunalization in India
- Implement SC recommendations from L. Chandra Kumar (1997) for an independent oversight authority.
- Debt Recovery Tribunal (DRT) Created to expedite loan recoveries but now has 215,431 pending cases. Recovery rates fell to just 9.2% (2022-23), undermining its purpose.
- Recovery rates fell to just 9.2% (2022-23), undermining its purpose.
- Double-shift working hours (discussed in 2011 but never implemented).
WHO’s Report on Compassion
- On February 7, 2025, the World Health Organization (WHO) released a report, “Compassion and primary health care”, which recognises compassion as a transformative force in primary health care.
- Faster Recovery: Compassionate care reduces hospital stays (Stanford University study).
- The 40-Second Rule: A simple "We are in this together" statement significantly aids patient recovery.
- Rescued from a superstitious ritual as an infant.
| Term | Definition | Impact on Health Care |
|---|---|---|
| Sympathy | Feeling pity for someone | A momentary reaction, no real impact. |
| Empathy | Deeply feeling others' pain | Can cause emotional exhaustion for caregivers. |
| Compassion | Feeling pain but with problem-solving focus | Leads to sustainable caregiving and better patient care. |
The Pitfalls of Toponymous Disease Naming
- Congenital Zika Syndrome (2016) The Zika virus was named after the Zika Forest in Uganda, where it was first isolated. To avoid geographical stigma, the WHO recommended the term Congenital Zika Syndrome to describe the fetal condition caused by the virus.
- The 1918–1920 influenza pandemic was labeled the Spanish flu, despite not originating in Spain.
- Mpox (Monkeypox) – 2022 The WHO renamed monkeypox as mpox due to concerns over racist and stigmatizing language linked to the disease’s name.
- Previously named after Hans Reiter, a German physician who described reactive arthritis in 1916.
Foreign Aid
- Is global aid funded by governments or by billionaire philanthropies? Here are the figures: Over 95% of the global foreign aid in 2023 derives from national governments.
- Over 95% of the global foreign aid in 2023 derives from national governments.
- A 2015 survey asked Americans how much of the U.S. federal budget went to foreign aid. The correct answer was under 1%. The average guess was 31%—a massive overestimation.
- Moreover, government funding played a mostly dominant role in the late 1990s and early 2000s by covering more than 80% of eradication efforts.
Immigration and Foreigners Bill
- The Bill merges and updates the following laws Foreigners Act Passport (Entry into India) Act Registration of Foreigners Act Immigration (Carriers' Liability) Act
- Foreigners Act
- Registration of Foreigners Act
- Immigration (Carriers' Liability) Act
ASHAs to Receive Higher Remuneration
- The scheme is focused on enhancing farmer incomes and ensuring the government’s commitment to doubling farmers’ income by 2022 (a target proposed earlier by the government).
- The Pradhan Mantri Annadata Aay SanraksHan Abhiyan (PM-AASHA) is a flagship initiative launched by the Government of India in September 2018 to ensure that farmers get fair prices for their produce and are protected from market fluctuations.
- The Pradhan Mantri Annadata Aay SanraksHan Abhiyan (PM-AASHA) was launched in September 2018.
- It is a central sector scheme of the Ministry of Agriculture & Farmers Welfare.
Bharti Airtel Alliance with SpaceX's Starlink
- Regulatory Approvals Needed Starlink needs to secure clearance from the Department of Telecommunications (DoT) and the Ministry of Home Affairs before it can commence its services.
- Starlink needs to secure clearance from the Department of Telecommunications (DoT) and the Ministry of Home Affairs before it can commence its services.
- Coverage: Over 100 countries and territories
- Residential & Business Internet: High-speed broadband with speeds up to 250 Mbps
PM Surya Ghar Scheme
- PM Surya Ghar Muft Bijli Yojana has installed 10.09 lakh rooftop solar system since its launch in February 2024. The Ministry of New and Renewable Energy (MNRE) has received 47.3 lakh applications so far, the government said.
- Budget Allocated Rs 75,021 crore.
- Rs 75,021 crore.
- Features Subsidies 60% of solar unit cost, if the systems capacity is within 2kW. 40% subsidy on additional system cost for systems between 2 to 3kW capacity. Capacity capped at 3kW.
Palk Bay Fisheries Dispute
- Lack of adequate financial support (₹1,600-crore deep-sea fishing scheme has seen limited success).
- Policy Proposal: Merging Palk Bay Deep-Sea Fishing Scheme with Pradhan Mantri Matsya Sampada Yojana (₹20,050 crore fund) to increase financial incentives for deep-sea fishing adoption.
- Merging Palk Bay Deep-Sea Fishing Scheme with Pradhan Mantri Matsya Sampada Yojana (₹20,050 crore fund) to increase financial incentives for deep-sea fishing adoption.
- Deep-sea fishing has been suggested as an alternative, but its adoption remains slow due to: Higher costs (longer voyages, advanced vessels). Traditional mindset (generational fishing practices). Lack of adequate financial support (₹1,600-crore deep-sea fishing scheme has seen limited success).
Indian Railways' Role in Mission Amrit Sarovar
- Launched: April 2022.
- Ponds completed (as of October 2024): 68,000+.
- Multiple stakeholders involved (Railways, Rural Development Ministry, State Governments, Local Communities) may create bureaucratic delays.
- Water conservation and rejuvenation: Address water scarcity by constructing or reviving 75 ponds per district.
Automated Permanent Academic Account Registry (APAAR) ID
- Illegalities The Supreme Court (K.S. Puttaswamy v. Union of India, 2019) said Aadhaar cannot be mandatory for education, yet APAAR is making it virtually so.
- The Supreme Court (K.S. Puttaswamy v. Union of India, 2019) said Aadhaar cannot be mandatory for education, yet APAAR is making it virtually so.
- The Automated Permanent Academic Account Registry (APAAR) ID intends to standardize student records with DigiLocker and the Academic Bank of Credits (ABC). The Education Ministry says that enrolments are voluntary, but CBSE has instructed all schools to get a 100% registration, making it difficult for them to opt out.
Oilfields (Regulation and Development) Amendment Bill, 2024
- The bill comes at a time when India relies heavily on imports for 85% of its crude oil needs.
- The move will attract greater foreign investment and encourage more private players to enter the exploration & production (E&P) sector.
| Reform Area | Key Change |
|---|---|
| Delinking Petroleum from Mining | Introduces "Petroleum Lease" as a separate category from a mining lease, removing legal ambiguities. |
| Clear Granting & Extension of Leases | Provides legal clarity on how petroleum leases are issued and extended. |
| Expanded Hydrocarbon Scope | Uses the term "mineral oils" instead of just "oils," bringing more hydrocarbons under regulation. |
| Dispute Resolution Mechanism | Introduces a new mechanism for resolving disputes in exploration and production (E&P) activities. |
PM-KUSUM 2.0
- Should be more robust and flexible than the current version (launched in March 2019).
- PM-KUSUM 2.0 could enhance renewable energy adoption among farmers through solar and decentralized energy projects.
- PM-KUSUM 2.0: The Ministry of New and Renewable Energy (MNRE) is working on an updated version of the Pradhan Mantri Kisan Urja Suraksha evam Utthaan Mahabhiyan (PM-KUSUM) scheme. The proposal is being prepared for approval by the Expenditure Finance Committee (EFC). National Bioenergy Programme - Phase II: MNRE is also developing a proposal for the second phase, even as Phase-I runs until March 2026.
- Needs to incorporate learnings from the first phase.
Rising Kidney Disease Cases Among Young Indians
- Adequate sleep (6–8 hours) and stress management
- Limited Access to Treatment India performs only 15,000 kidney transplants yearly, while demand exceeds 2 lakh Dialysis requires large amounts of water (125L per session), making expansion difficult
- India performs only 15,000 kidney transplants yearly, while demand exceeds 2 lakh
- Lifestyle Factors Obesity, poor diet, excessive fast food, high sodium intake Low water consumption, especially among students and professionals Excessive use of painkillers, protein supplements (whey, creatine)
India’s First-Ever Auction of Exploration Licences for Critical Minerals
- Exclusive Exploration Rights: Private firms can explore up to 1,000 square meters per licence.
- Number of Exploration Blocks: 13.
- Strengthening the critical mineral supply chain will support sectors like electronics, renewable energy, and defense.
ISRO Successfully Accomplishes SpaDeX Satellite Undocking
- Nearly two months after successfully docking two satellites as part of the Space Docking Experiment (SpaDeX) mission, the Indian Space Research Organisation (ISRO) achieved a new milestone by executing their undocking on March 14, 2025, at 9:20 a.m.
- Launch Date: December 30, 2024, via PSLV C60.
- Docking Date: January 16, 2025.
- Orbit Details: 460 km circular orbit with a 45-degree inclination.
Prime Minister Internship Scheme (PMIS) App
- Announced in Budget 2024-25, the Prime Minister’s Internship Scheme (PMIS) aims to provide internship opportunities to one crore youth in top 500 companies over the next five years.
- The Ministry of Corporate Affairs (MCA) launched the scheme as a Pilot Project on October 3, 2024, with a target of 1,25,000 internships for FY 2024-25.
- First Round (2024-25): Over 1,27,000 internships were offered across various sectors.
- Financial Allocation: ₹840 crore allocated for the pilot project. ₹48 crore spent so far.
Hantavirus: A Rare but Deadly Disease
- Hemorrhagic Fever with Renal Syndrome (HFRS): Causes internal bleeding and kidney failure.
- Carried by Rodents: Common carriers include deer mice, white-footed mice, rice rats, and cotton rats.
- Incubation Period: Symptoms appear 1-8 weeks after exposure.
- Severe Symptoms: Respiratory Distress: Shortness of breath, chest tightness, and fluid in the lungs. Organ Failure: In HFRS, it can lead to kidney failure and internal bleeding.
Starlink’s Entry into India Through Bharti Airtel & Reliance Jio
- B2B Expansion: Partnerships may help telecom players grow their enterprise and business connectivity offerings in areas lacking fiber or fixed wireless access.
- Stock Market Outlook: Long-term Investors: May find buying opportunities on market dips, driven by 5G expansion and digital transformation. Short-term Caution: Regulatory challenges could cap near-term stock gains.
- Long-term Investors: May find buying opportunities on market dips, driven by 5G expansion and digital transformation.
- Bharti Airtel Partnership: Will provide Starlink’s high-speed satellite internet to customers.
Parliamentary Committee Calls for Revision of MGNREGS Wages
- Impact on Budget: Out of the ₹86,000 crore allocated for the scheme in the current fiscal year, nearly ₹23,446 crore will be used to clear past dues. Effective budget for new projects reduced to ₹62,553.73 crore, limiting the scheme’s effectiveness.
- Out of the ₹86,000 crore allocated for the scheme in the current fiscal year, nearly ₹23,446 crore will be used to clear past dues.
- Effective budget for new projects reduced to ₹62,553.73 crore, limiting the scheme’s effectiveness.
- Highlighted disparities in current wages, ranging from ₹234 (Nagaland & Arunachal Pradesh) to ₹374 (Haryana & Sikkim).
India’s Real-Money Gaming (RMG)
- A 2024 industry report estimates the illegal betting market size at ₹8.2 lakh crore and expanding.
- Illegal Market Growth Offshore gambling firms are growing at a 30% CAGR, mirroring early growth patterns of legal RMG before GST imposition. Legal RMG firms now see a slower growth rate of 10%-15%. A 2024 industry report estimates the illegal betting market size at ₹8.2 lakh crore and expanding.
- Legal RMG firms, including Dream11 and PokerBaazi, are subject to 28% GST.
- Offshore gambling firms are growing at a 30% CAGR, mirroring early growth patterns of legal RMG before GST imposition.
Aditya-L1 Mission
- Solar Cycle & Future Observations As the Sun approaches the peak of Solar Cycle 25, CME activity is expected to increase. Continuous monitoring by VELC will provide valuable data for both Indian and global researchers.
- Scientists from the Indian Institute of Astrophysics (IIA) have observed a flareless CME using the Visible Emission Line Coronagraph (VELC) onboard Aditya-L1, India’s first dedicated solar research mission. The CME, detected on July 5, 2024, had no associated solar flare, providing insights into alternative mechanisms behind these solar eruptions.
- Magnetic Instability & Differentiation The study aims to differentiate magnetic instabilities that cause flares and CMEs. Understanding their association is a key goal for solar physics.
- Understanding their association is a key goal for solar physics.
Understanding Flares vs. CMEs
- CMEs Massive plasma eruptions (weighing ~trillion kg). Travel up to 3,000 km/s through space. Association with flares remains unclear.
- Travel up to 3,000 km/s through space.
APAAR ID
- The Digital Personal Data Protection Act, 2023 has not yet taken effect, raising concerns about data security.
- The Education Ministry states APAAR is not mandatory, yet schools and education authorities are pushing for 100% enrolment.
- Religious minority institutions and administrators face scrutiny over data mismatches.
- Errors in names and records can result in students being denied access.
India-Bangladesh Naval Exercise Bongosagar 2025
- India-Mauritius Defence Partnership India-Mauritius Joint Vision 2025 reaffirms commitments to maritime security cooperation. Key agreements include: Increased ship and aircraft deployments for joint surveillance. Strengthening Mauritius' exclusive economic zone security. Expanding use of Agalega Island’s new runway and jetty for defence purposes. Setting up a National Maritime Information Sharing Centre in Mauritius.
- India-Mauritius Joint Vision 2025 reaffirms commitments to maritime security cooperation.
- Despite strained political ties since Sheikh Hasina’s removal in August 2024, the India-Bangladesh naval exercise "Bongosagar 2025" and the Coordinated Patrol in the Bay of Bengal proceeded as scheduled. This indicates that defence relations remain stable even as political tensions persist.
- Objective Enhance interoperability between the two navies. Strengthen coordination in tactical planning, joint operations, and maritime security.
PM-ABHIM Funds
- FY25: BE ₹3,200 crore, RE reduced to ₹3,000 crore, only ₹2,007 crore (66.9%) spent till February 2025.
- FY24: BE ₹4,200 crore, RE halved to ₹2,100 crore, actual spending ₹1,805 crore.
- FY23: BE ₹4,176 crore, RE ₹2,100 crore, actual spending ₹1,885 crore.
- Completion rate: Only 5,682 units (43%) finished
Greenhouse Gas Emission Impact on Orbital Space of Earth
- The study compared contemporary circumstances with predicted ones in the light of greenhouse gas levels from the year 2000 baseline.
- Increasing anthropogenic greenhouse gas emissions will shrink the mesosphere and thermosphere of the Earth, reducing the safety carrying capacity of satellites from 50% to 66% by the year 2100.
- Carbon Dioxide (CO2): The most abundant GHG, primarily from burning fossil fuels (coal, oil, and natural gas).
- Methane (CH4): A potent GHG, emitted from sources like livestock, landfills, and natural gas production.
Melioidosis in India
- Global Burden Annually, 165,000 cases worldwide, with South Asia (including India) accounting for 44% of cases (The Lancet, 2016).
- Annually, 165,000 cases worldwide, with South Asia (including India) accounting for 44% of cases (The Lancet, 2016).
- Can present as mild skin infection to severe sepsis (fatality rate up to 50% in septicemia).
- Objective: To investigate how climate and environmental factors influence melioidosis transmission in Odisha.
Treating Chikungunya using HIV/AIDS drug efavirenz
- Re-emergence in 2006 after 20-30 years.
- Results: Efavirenz inhibited virus replication by 99% at low micromolar concentrations. Drug was effective up to 6-8 hours post-infection, acting in the early replication phase.
- Efavirenz inhibited virus replication by 99% at low micromolar concentrations.
- Drug was effective up to 6-8 hours post-infection, acting in the early replication phase.
Madhav National Park Declared India’s 58th Tiger Reserve
- Recent Tiger Relocation (2023) Had no tigers before 2023. One male and two female tigers relocated. Population now increased to seven.
- Had no tigers before 2023.
- 2023 Tiger Census: Estimated 3,682 tigers.
- Originally notified as a National Park in 1956 under the MP National Parks Act, 1955.
Crisis in Public Health Education and Employment in India
- The All India Institute of Hygiene and Public Health (1932) and later community medicine courses were early public health training efforts.
- Growth surged after 2005 with the National Rural Health Mission (NRHM), leading to an increase in MPH programs from 1 (in 2000) to over 100 today.
- The U.S. decision to withdraw from WHO and reduce US-AID funding has disrupted global aid and health services. India, which relies on only 1% of international aid for healthcare, remains largely unaffected at a system level.
- Despite this expansion, government hiring plateaued, while graduates continued to increase, leading to an oversupply.
Tackling the Problem of Nutrition in India
- Key Statistics (NFHS-5 Data) 36% of children under five are stunted. 57% of women (15-49 years) are anaemic. 24% of women and 23% of men are overweight or obese. 14% take diabetes medication.
- 36% of children under five are stunted.
- 57% of women (15-49 years) are anaemic.
- 24% of women and 23% of men are overweight or obese.
Rising MGNREGA Demand
- GDP Growth Slowdown Q3 FY25 GDP growth at 6.2% is the slowest in nearly two years (excluding Q2). Requires an unrealistic 7.6% Q4 growth to meet the 6.5% full-year target. Indicates an economic deceleration, impacting rural employment.
- Q3 FY25 GDP growth at 6.2% is the slowest in nearly two years (excluding Q2).
- Requires an unrealistic 7.6% Q4 growth to meet the 6.5% full-year target.
- Manufacturing Weakness PMI fell to a 14-month low (56.3 in February), reflecting slowing industrial activity. Declining factory orders signal weak job creation in urban and semi-urban areas, pushing more people toward MGNREGA.
Pradhan Mantri Internship Scheme (PMIS) Mobile App
- And the last date of registration has now been extended to 31st March 2025, after which the candidates are expected to take their internships on or before 15th May 2025.
- In this pilot phase, 325 companies made the opportunity of sharing almost 118,000 internship opportunities.
- Approximately 115,000 candidates have registered, and till date, more than 240,000 applications have been received.
- CSR funding was never the standard for PMIS inclusion, but the government is considering an expansion of candidates outside the current top 500.
PM Surya Ghar Muft Bijli Yojana (PMSGMBY)
- Launched: February 2023
- Budgetary Allocations Initially ₹6,250 crore (2024-25), revised to ₹11,100 crore Further increased to ₹20,000 crore (2025-26)
- Initially ₹6,250 crore (2024-25), revised to ₹11,100 crore
- Further increased to ₹20,000 crore (2025-26)
Rise in Seasonal Influenza Cases
- Often confused with the common cold, but differs in: Severity and viral cause Symptoms: sudden cough, sore throat, high fever, muscle pain, body aches, headaches, fatigue, stuffy nose
- Surveillance was further strengthened post COVID-19.
Genetic Cause of Early Lung Cancer Relapse
- Lung cancer in India (2022): 81,748 new cases 75,031 deaths (WHO data)
- Lung adenocarcinoma: Most common type of lung cancer, affecting even non-smokers.
- Current treatment: Targeted drugs known as EGFR tyrosine kinase inhibitors (TKIs) are used for patients with mutations in the EGFR gene.
- Personalized Treatment Early detection of TSG mutations can help doctors tailor therapies to account for potential resistance. May delay or prevent early relapse.
| Aspect | Details |
|---|---|
| Study Scope | Analyzed data from 483 lung cancer patients with EGFR mutations. |
| Discovery | Presence of mutations in certain tumor suppressor genes (TSGs) along with EGFR mutation increases risk of early relapse. |
| Survival Impact | - Patients with TSG mutations had an average survival of 51.11 months compared to 99.3 months for others. - Progression-free survival was also significantly shorter. |
| Identified Genes | A group of 17 tumor suppressor genes found to contribute to therapy resistance and early relapse. |
Supreme Court on Lokpal's Jurisprudence
- The Lokpal classified High Court judges as public servants, similar to The Prime Minister Union Ministers Members of Parliament Central government officials Hence, asserting that judges fall under the Lokpal and Lokayuktas Act, 2013.
- Hence, asserting that judges fall under the Lokpal and Lokayuktas Act, 2013.
- Triggered by a January 27 order from the Lokpal, which claimed authority to investigate complaints against serving High Court judges.
- Union Ministers
The Future of Free Speech Global Survey
- 37% of Indians agree that governments should be able to prevent criticism of government policies — the highest among all surveyed nations. By contrast: U.K. (5%) and Denmark (3%) showed minimal support for such restrictions.
- By contrast: U.K. (5%) and Denmark (3%) showed minimal support for such restrictions.
- U.K. (5%) and Denmark (3%) showed minimal support for such restrictions.
- Trend: Support for free speech declining since 2021, especially in democratic countries (notably U.S., Israel, Japan). Some authoritarian-leaning countries show strong popular support, despite restrictive governments.
India AI Mission
- India aims to create domestic facilities for the manufacture and deployment of GPUs in the next 3–5 years.
- Following the success of setting up 100 labs for 5G training in universities, a similar approach will be taken for AI skill development.
- A common compute facility under the India AI Mission is made available with 14,000 GPUs.
- The India Artificial Intelligence (AI) Mission has signed an MoU with the Parliament to access its data for training indigenous large language models (LLMs). Other datasets from Doordarshan and All India Radio will be used.
Chandrayaan-3 Data About Water on Moon
- This experiment used 10 high accuracy platinum resistance temperature detector (RTD) sensors on board to monitor surface temperatures for approximately 10 days on Earth during the lunar day (around 8 hours).
- The study is founded upon the local ground level observations made by the Chandrayaan-3 Vikram lander, which set down on the lunar surface in August 2023.
- The team measured ambient surface temperatures and sub surface temperatures at Shiv Shakti Point (69.373° south, 32.319° east) on the south pole of the moon using Chandra's Surface Thermophysical Experiment (ChaSTE).
- Highest temperatures achieved during the lunar days were 82ºC while nighttime temperatures plummeted to about 181ºC.
Election Commission to Start Aadhaar-Voter Card Linkage Process
- The SC directed petitioners to submit representations to the EC within 10 days.
- In April 2023, the government informed Rajya Sabha that: Citizens who do not link Aadhaar with voter ID will not have their names removed from electoral rolls.
- The EC reiterated: Voting rights are guaranteed only to citizens of India (Article 326 of the Constitution).
- Political and judicial oversight will continue to shape the process.
What Is the APAAR ID?
- The Role of APAAR in NEP 2020 Being introduced as part of reforms in educational data, so as to strive towards evidence based policymaking and analysis. The Education Ministry is actively pursuing full saturation in CBSE affiliated institutions.
- It further prohibits the tracking or behavioral observations of children as per Section 9(3) of the Digital Personal Data Protection Act of 2023.
- Legal Risks Collection of minors' personal data on a massive scale, without any legislative authority, could infringe on constitutional guarantees. It further prohibits the tracking or behavioral observations of children as per Section 9(3) of the Digital Personal Data Protection Act of 2023. Existence of APIs could mean exposure to third parties without sufficient safeguards, increasing the chances of misuse.
- Aim Generate an independent, permanently valid academic ID as part of the "One Nation, One Student ID" initiative. Preserve student academic achievements for smoother inter institution transfers and record verification.
Union Cabinet Approved ₹4,500 Crore Greenfield Highway Project
- Logistics Efficiency Improvement Travel time will diminish from between 2–3 hours to little as 10 m by avoiding several congested urban points, including Palaspe Phata, Kalamboli junction, and Panvel.
- Travel time will diminish from between 2–3 hours to little as 10 m by avoiding several congested urban points, including Palaspe Phata, Kalamboli junction, and Panvel.
- Allows Preparation for Navi Mumbai International Airport Avi Mumbai Airport is likely to start operations around 2025. The highway promises smooth cargo movement and passenger movement.
- Avi Mumbai Airport is likely to start operations around 2025. The highway promises smooth cargo movement and passenger movement.
India's Monsoon Forecast
- Early projections in 2024 suggested that a strong La Niña would develop, supported by cold sea surface temperature (SST) anomalies deep in the eastern tropical Pacific.
- Hence, ETM probably disrupted the expected transition from El Niño (2023 24) to La Niña (2024 25) that resulted in the ongoing chaotic ENSO state.
- The 2025 climate forecasts are pretty murky: Some models predict the emergence of La Niña by fall. Others see it as a neutral year, or occasionally it might even paint a discharge for a strong El Niño scenario. This divergence makes the science of accurate monsoon forecasting increasingly difficult.
- India looks forward to the 2025 monsoon forecast for implications on agriculture, water resources, and economic stability. Will El Niño or La Niña rule the 2025 2026 season?Not to forget, El Niño and La Niña explained the high incidence of monsoon failing or surplus years to only 60 percent, but still remaining as great indications.
India’s Inward Remittances in FY24
- Growth driven by a 6.3% increase in foreign-born workers in the US labor force in 2022, up from 0.7% in 2019.
- The US remained the top contributor with 27.7% share in FY24, up from 23.4% in FY21.
- 78% of Indian migrants in the US are employed in high-earning sectors: Management Business Science Arts
- The UAE contributed 19.2% in FY24 (up from 18% in FY21).
| Country/Region | Share in FY21 (%) | Share in FY24 (%) |
|---|---|---|
| United States | 23.4 | 27.7 |
| United Arab Emirates | 18.0 | 19.2 |
| United Kingdom | 6.8 | 10.8 |
| Singapore | Not available | 6.6 |
| Canada | Not available | 3.8 |
| Australia | Not included in FY21 data | 2.3 |
Prime Minister Internship Scheme (PMIS)
- Actual spending (till mid February 2025): ₹21.10 crore
- Interns by Gender 72% Male 28% Female
- FY2024-25 Budget Estimate (BE): ₹2,000 crore Revised Estimate (RE): ₹380 crore
- Budget Estimate (BE): ₹2,000 crore
Chabahar Port and Sagarmala 2.0
- ₹4,000 crore capital expenditure is underway, focusing on: Acquiring modern cranes Mechanisation and terminal modernisation
- Budgetary corpus: ₹40,000 crore.
- Concerns over viability intensified after US President Donald Trump’s executive order (Feb 2025), directing sanctions reassessment, which could impact the Chabahar Port project.
- Ongoing discussions between the Ministry of Shipping and the Ministry of External Affairs on potential implications.
World Happiness Report 2025
- Lower-middle-aged Indians (30–44 years) are the least happy demographic with the steepest decline in happiness scores since 2006–10.
- BRICS Happiness Scores (2021–23 average) Brazil: 6.27 Russia: 5.79 India: 4.05 China: 5.97 South Africa: 5.42
- India ranks 126th out of 143 countries, with a happiness score of 4.054, placing it at the bottom among BRICS nations.
- Brazil: 6.27
| Age Group | Happiness Score | Change from 2006–2010 |
|---|---|---|
| Below 30 (Young) | 4.28 | -0.79 |
| Lower-middle age (30–44) | 3.76 (Lowest) | -1.12 (Sharpest fall) |
| Upper-middle age (45–60) | 4.01 | -0.94 |
| Above 60 (Old) | 4.10 | -0.87 |
| All Ages | 4.05 | -0.92 |
Inward remittances to India
- The Gulf Cooperation Council (GCC) countries UAE, Saudi Arabia, Kuwait, Qatar, Oman, and Bahrain contributed 38% of India's remittances in FY24, down from 50.2% in FY21.
- Gradual decline in the number of low skilled labor exports to GCC countries with an onward shift in the economic diversification of those countries.
| Source | FY21 Share (%) | FY24 Share (%) |
|---|---|---|
| Advanced Economies (US, UK, Singapore, Canada, Australia*) | 34.2% | 51.2% |
| GCC Countries (UAE, Saudi Arabia, Kuwait, Qatar, Oman, Bahrain) | 50.2% | 38% |
Swadesh Darshan Scheme
- Swadesh Darshan Scheme Launched in 2014-15 to develop theme-based tourist circuits. 76 projects sanctioned across 31 States/UTs with an allocation of ₹5,292.57 crore (2014-15 to 2018-19). Ministry: Ministry of Tourism
- Launched in 2014-15 to develop theme-based tourist circuits.
- 76 projects sanctioned across 31 States/UTs with an allocation of ₹5,292.57 crore (2014-15 to 2018-19).
- The Tourism Ministry claimed completion of 75 out of 76 projects.
Eli Lilly Launches Mounjaro (Tirzepatide) in India for Diabetes and Obesity
- GLP-1 class drug demand: Market worth hundreds of billions of dollars Semaglutide, a key drug in this class, to go off-patent in March 2026.
- Existing market leaders: Novo Nordisk’s Rybelsus (oral semaglutide) launched in 2022; holds 65% market share. Other weight-loss medications: dulaglutide, liraglutide.
- Novo Nordisk’s Rybelsus (oral semaglutide) launched in 2022; holds 65% market share.
- Anti-obesity drug market in India: ₹137 crore in November 2020 Expanded to ₹535 crore by November 2024 (as per Pharmatrac).
AI-Based Cloud Solution 'Vayu'
- Cost savings of 15–25% compared to large cloud service providers
SBI Report on Labour Migration
- Inflation decline: North-east: 3.4% South: only 2.6%
- North-east: 3.4%
- South: only 2.6%
- Southern states account for 30% of total state sales tax collection, the highest among regions.
National Centres of Excellence (CoEs) for Skilling
- Budget 2024 Announcement Finance Minister Nirmala Sitharaman announced the establishment of these five CoEs, emphasizing global partnerships for 'Make in India, Make for the World' manufacturing goals.
- Higher NSQF-Level Courses The CoEs will operationalise higher-level NSQF courses (levels 5 to 8), currently underrepresented in the skill development ecosystem.
- The CoEs will operationalise higher-level NSQF courses (levels 5 to 8), currently underrepresented in the skill development ecosystem.
- Existing NSTI Network There are currently 33 NSTIs in India, primarily responsible for training trainers for ITIs and industries through specialized, hands-on skill transfer methods.
World Happiness Report 2025
- India’s healthy life expectancy (2021): 58.1 years
- Pakistan’s healthy life expectancy (2021): 56.9 years
- The World Happiness Report 2025, uses three-year averages (2022–2024) for its rankings.
- India’s per capita income (2023): $2,480.8 (World Bank)
| Country | Happiness Score (2022–24) | Previous Score (2021–23) | Change in Rank | Change in Score (vs. 2006–10) |
|---|---|---|---|---|
| India | 4.39 | 4.05 | Improved from 126th to 118th | -0.58 |
| Pakistan | 4.77 | 4.66 | Dropped from 108th to 109th | -0.37 |
| Nepal | 5.31 | — | — | +0.71 |
| Sri Lanka | 3.89 | — | — | -0.38 |
| Bangladesh | 3.85 | — | — | -0.92 |
Web Browser Ulaa
- However, after a 2014 security breach, where fake SSL certificates were issued from government systems, major browsers stopped trusting CCA’s certificates.
- The Indian government has awarded ₹1 crore to Tenkasi-based Zoho Corporation for developing an indigenous web browser named Ulaa.
- The core requirement for the browser is to trust India’s own root certifying authority.
- India’s Controller of Certifying Authorities (CCA) under the IT Ministry has its own root certificate.
Parliamentary Committee Recommends Expansion of PLI Scheme
- The Production-Linked Incentive (PLI) scheme currently covers 14 sectors with an outlay of ₹1.97 trillion.
- IES provided export credit cost relief but ceased on December 31 and was merged with the ₹2,250 crore Export Promotion Mission.
- The committee suggests extending PLI coverage to labour-intensive sectors such as: Chemicals Leather Apparel Handicrafts
- Monitoring recommendation: The committee has stressed the need for a robust framework to monitor and report PLI’s impact, which is crucial for course corrections and efficient fund allocation.
| Area | Opportunities | Challenges/Concerns |
|---|---|---|
| PLI Expansion | Employment generation in labour-intensive sectors; strategic autonomy | Need for careful fund management and measurable impact monitoring |
| E-Commerce Policy Delay | Untapped potential in rapidly growing digital markets | Regulatory uncertainty may deter investments |
| Export Promotion | Lowering export credit costs to drive competitiveness | Budgetary constraints and delayed scheme rollout |
| FTAs and Trade Balance | Greater market access and investment flows | Risk of continued trade deficits unless addressed proactively |
Launch of Tavasya
- Triput, the first indigenous frigate, was launched in July 2023.
- The Defence Ministry signed a formal contract with GSL in January 2019.
- In October 2016, India and Russia signed an Inter-Governmental Agreement for four follow-on Krivak-class frigates.
- In November 2018, GSL signed a $500 million contract with Rosoboronexport for material, design, and specialist assistance.
India-France Naval Exercise Varuna 2024
- The French Carrier Strike Group (CSG), led by Charles de Gaulle, has been deployed in the Indian Ocean Region since November 2024 as part of Mission Clemenceau 25, underscoring France’s strategic focus on the Indo-Pacific region.
- Air warfare integrating MiG-29K and Rafale-M fighter jets from both carriers.
- India and France deployed their aircraft carriers INS Vikrant and Charles de Gaulle for the bilateral naval exercise Varuna from March 19 to 22, 2024, off the coast of Goa. The exercise offered India a valuable opportunity to closely observe and operate the French Navy’s Rafale-M fighter jets, which India is set to acquire soon. The joint exercise also placed significant emphasis on anti-submarine warfare (ASW) operations.
- The exercise covered comprehensive naval warfare domains: Sub-surface operations involving Indian submarines. Surface warfare with coordinated engagements between Indian and French frigates. Air warfare integrating MiG-29K and Rafale-M fighter jets from both carriers.
Kerala Launches ‘Look East’ Campaign
- Inbound Promotion: In April, Kerala will host 40 tour operators and 15 social media influencers from these eight target countries to promote Kerala’s tourism offerings.
- In April, Kerala will host 40 tour operators and 15 social media influencers from these eight target countries to promote Kerala’s tourism offerings.
- Kerala’s foreign tourist arrivals stand at only 62% of pre-pandemic levels. Despite being Asia’s largest outbound travel market, China contributes almost no visitors to Kerala.
- Airline Partnership: Kerala has formed a strategic understanding with Malaysia’s airways to facilitate better connectivity.
PLI Schemes in India
- Reuters Report Claim: Production under PLI was at $151.93 billion (₹13 lakh crore), only 37% of the target. Incentives issued were below 8% of allocated funds.
- The Centre’s Production-Linked Incentive (PLI) schemes, aimed at boosting manufacturing across 14 key sectors, have attracted ₹1.61 lakh crore in investments and generated sales worth ₹14 lakh crore, according to the Ministry of Commerce.
- Incentives disbursed: ₹14,020 crore across 10 sectors.
- PLI-enabled exports have surpassed ₹5.31 lakh crore (approx. $61.76 billion).
Influenza Cases Surge in Delhi-NCR
- Surveillance between 2016–2018 showed: 15.4% of ARI cases and 12.7% of SARI cases were due to influenza.
- WHO recommendations for 2025–26 flu vaccine composition were announced on Feb 28, 2025, giving manufacturers time to prepare.
- In the U.S., as of Feb 15, 2025: 57 million adults and 47% of children had been vaccinated.
- In India, vaccine uptake remains below 5%: A 2022 study found only 1.5% of adults aged 45+ had ever been vaccinated. Despite severe outbreaks in 2015, 2017, 2019, and 2024, uptake remains stagnant.
Study Challenges Infant Memory Assumptions
- Conducted by Tristan Yates and colleagues from Columbia University, the study involved infants aged 4 to 25 months.
- A new fMRI study, published in Science, reveals that infants as young as 12 months can encode individual memories.
- Instead, researchers suggest that memory retrieval failures, rather than encoding problems, are the likely cause of this phenomenon.
- Infantile amnesia refers to the inability to remember events from the first three years of life.
Tuberculosis (TB) Trends and Performance in India
- TB incidence in India fell below 200 per lakh population in 2022, compared to 237 per lakh in 2015, marking a 16% decline.
- TB mortality rate in 2022 was 23 per lakh population, reflecting an 18% decline compared to 2015.
- Severely Drug-Resistant TB (resistant to isoniazid, rifampicin, any fluoroquinolone, and at least one second-line injectable drug): Treatment success rate: 45% — the lowest among all TB types.
- Treatment success rate: 45% — the lowest among all TB types.
Scientists Discover Four Scorpion Species
- The research was carried out by: Gaurav Barhadiya and Aisha Sultana (Delhi University) Pratyush P. Mohapatra (Zoological Survey of India) Pragya Pandey and Sanjay Keshari Das (Guru Gobind Singh Indraprastha University)
- Gaurav Barhadiya and Aisha Sultana (Delhi University)
- Pragya Pandey and Sanjay Keshari Das (Guru Gobind Singh Indraprastha University)
- Four scorpion species recorded: Chersonesometrus fulvipes Isometrus maculatus Compsobuthus rugosulus Lychas cf. biharensis
India’s Urbanisation Journey
- Mobility: City mobility plans and major investments in metro rail projects (30% of urban budget during NDA).
- Finance Commissions imposed conditionalities on fund transfers: Example: 15th Finance Commission’s condition to link property tax enhancement with State GDP growth.
- Redefine fiscal devolution: 70% of the Union Budget for urban development should go as direct transfers to States and city governments. Remaining 30% should be retained for national priorities (like climate resilience).
- 70% of the Union Budget for urban development should go as direct transfers to States and city governments.
DNA Fingerprinting and Its Role in Identification
- Structure: DNA is packaged in chromosomes (e.g., Chromosome 3 holds 6.5% of total DNA). DNA consists of two complementary, anti-parallel strands made up of adenine (A), cytosine (C), guanine (G), and thymine (T).
- DNA is packaged in chromosomes (e.g., Chromosome 3 holds 6.5% of total DNA).
- Step 2: Annealing — Cool to 60°C to allow primers to bind to specific DNA regions.
- Historical Analysis: Extract DNA from ancient remains (up to 65,000 years old).
Guidelines on Deletion of MGNREGS Job Cards
- Publication of Deleted Names: Deleted workers/job card details must be published in public domain for at least 30 days.
- Deleted workers/job card details must be published in public domain for at least 30 days.
- Over 10.43 crore workers have been removed from the Mahatma Gandhi National Rural Employment Guarantee Scheme (MGNREGS) in the past four years. Aadhaar-linked payments: The deletions coincide with the implementation of Aadhaar-based payment systems, though the government denies any direct correlation.
- Biannual Reviews in Gram Sabhas: Twice a year, Gram Sabhas must convene to: Discuss the draft list of flagged job cards. Address objections raised by affected workers.
India’s Genomic Sequencing Initiative for Tuberculosis
- India’s target: Eradicate TB by 2025, five years ahead of WHO’s 2030 target.
- Drug Resistance: 7% of sequenced TB strains showed resistance to a single drug.
- 7% of sequenced TB strains showed resistance to a single drug.
- Demographic Insights: Majority of TB patients are between 18-45 years of age. Many patients are diabetic and underweight, indicating comorbidities.
India to Conduct First-Ever ‘Aikeyme’ Naval Exercise
- Crew Composition: Indian sailors + 44 personnel from nine ‘friendly foreign countries’
- Dates: April 13 to 18, 2025
- Launch Date: April 5, 2025
- Deployment Period: April 5 to May 8, 2025
Collegium System
- First Judges Case (1981)
- For the next 12 years, the government had the upper hand in deciding who became judges.
- The government tried to change the system by introducing the National Judicial Appointments Commission (NJAC) in 2014.
- But the Supreme Court struck down the NJAC in 2015, saying it would hurt the independence of the judiciary.
SAHYOG Portal
- These notices are issued by the Appropriate Government or its agencies under the IT Act, 2000.
- The portal has been developed by the Ministry of Home Affairs (MHA).
- It aims to bring central and state government agencies and online platforms (intermediaries) onto one platform to make the process of sending and acting on blocking orders smoother and more organized.
Current Use
- Both Central and State governments are already issuing blocking orders through the SAHYOG portal.
- However, platforms like X (formerly Twitter) are resisting being part of this portal, arguing that it could bypass existing legal safeguards and turn into a censorship tool.
JSW Steel Becomes World’s Most Valuable Steelmaker
- Tata Steel, established in 1907 and part of Tata Sons, ranks fifth globally with a market cap of $23.09 billion.
- JSW Steel leads in market valuation but ArcelorMittal remains ahead in terms of revenue ($62.4 billion) compared to JSW’s $21.1 billion.
- JSW Steel trades at a price-to-earnings (P/E) ratio of 28.5x, significantly higher than ArcelorMittal’s 20.3x, indicating strong investor confidence and growth potential.
- Experts point out that the shift in global steel rankings reflects the growing prominence of Indian producers in the global steel industry.
| Rank | Company | Country | Mcap ($ bn) | TTM Revenue ($ bn) | Profit ($ bn) |
|---|---|---|---|---|---|
| 1 | JSW Steel | India | 30.31 | 21.1 | 1.1 |
| 2 | Nucor Corporation | United States | 29.40 | 30.7 | 2.0 |
| 3 | ArcelorMittal | Luxembourg | 27.14 | 62.4 | 1.3 |
| 4 | Nippon Steel | Japan | 24.43 | 58.0 | 3.1 |
| 5 | Tata Steel | India | 23.09 | 27.5 | -0.5 |
| 6 | Tenaris | Luxembourg | 22.98 | 12.5 | 2.0 |
| 7 | Baoshan Iron & Steel | China | 22.72 | 46.1 | 1.3 |
| 8 | Steel Dynamics | United States | 18.99 | 17.5 | 1.5 |
| 9 | Posco Holdings | South Korea | 17.35 | 53.3 | 0.8 |
| 10 | Inner Mongolia BaoTou Steel | China | 11.54 | 9.3 | -0.1 |
Astronomers Unveil New Theory on the Origins of Water in the Universe
- The Big Bang aftermath: About 13.8 billion years ago, the Big Bang formed all matter, and the first stars emerged a few hundred million years later, composed solely of hydrogen and helium.
- Research approach: Led by astronomer D.H. Whalen from the University of Portsmouth, the team used advanced 3D simulations to study Population III supernovae.
- Findings: Conditions for water formation existed between 50 million and 1 billion years after the Big Bang. Supernovae from these gigantic stars expelled oxygen, which combined with hydrogen to form water — a vital ingredient for life.
- Water's cosmic presence: Water is the third most abundant molecule in the universe after hydrogen and carbon monoxide, yet its origins have remained uncertain.
How Global Warming Is Impacting Mountain Regions Across the World
- The UNESCO report titled “Mountains and Glaciers: Water Towers”, released on the first World Day for Glaciers (March 21, 2025), highlights the rapid and largely irreversible impacts of global warming on mountain ecosystems.
- Since 1975, glaciers (excluding Greenland and Antarctica) have lost over 9,000 billion tonnes of ice — equivalent to an ice block the size of Germany.
- A study published in Nature (2024) shows a 7.79% global decline in persistent snow cover between 1979 and 2022.
- Between 2006 and 2016, glaciers lost 335 billion tonnes of ice annually, contributing nearly 1 mm per year to sea-level rise.
India's Social Welfare Coverage: ILO Report
- India’s social protection coverage has doubled from 24.4% in 2021 to 49% in 2024. The International Labour Organization (ILO) expanded its assessment, now recognizing 34 major central schemes (earlier only 7 were considered). India believes ILO’s 48.8% estimate is still an underestimation, as it does not include in-kind benefits or state-level programs.
- 10 states (UP, Rajasthan, Maharashtra, MP, Tamil Nadu, Odisha, Andhra Pradesh, Telangana, Karnataka, Gujarat) have been asked to submit data.
- India advocates for broader social protection indicators, including housing and food security under the UN Sustainable Development Goals (SDGs).
- Employment & Pension: MGNREGA, Atal Pension Yojana (APY)
GSAT-18
- Six transponders on GSAT-18 (launched in 2016) will remain unutilized until 2027 due to overlap with GSAT-14.
- The realization of GSAT-14, including six Ext C-band and six Ku-band transponders, cost ₹110 crore in 2014 (excluding launch costs).
- Ensuring continuity of service: GSAT-18 was designed to take over from GSAT-14 after its mission life ends in 2027 and will operate until 2032.
- Revenue loss of ₹117 crore has already occurred due to the non-utilization of these transponders.
X Challenges SAHYOG Portal
- A follow-up to an October 2023 memorandum from the Ministry of Electronics and IT (MeitY) under Section 79 of the IT Act, which empowers government agencies to block online content.
- Potential for Unchecked Censorship: The portal removes opportunities to challenge takedown requests, unlike Section 69A. There is no independent oversight, raising concerns of arbitrary content blocking.
- Bypassing Section 69A Protections: Section 69A of the IT Act allows content blocking only on specific grounds like national security and public order. It requires procedural safeguards, such as written justification, independent review, and approval by a designated officer. SAHYOG sidesteps these safeguards by enabling multiple government bodies, including state agencies and police, to issue takedown orders.
- Section 69A of the IT Act allows content blocking only on specific grounds like national security and public order.
India's Progress on Sustainable Development Goals (SDGs)
- India's SDG index improved from 57 in 2018 to 71 in 2023-24.
- Top-performing states: Kerala and Uttarakhand lead with eight goals exceeding 80% achievement.
- Odisha: 16.4% expenditure on Goal 4 (Quality Education) but saw a 5-point decline.
- Meghalaya: 12.8% spending on Goal 1 (No Poverty) yet a 14-point decline.
Immigration and Foreigners Bill, 2025
- The Lok Sabha approved the Immigration and Foreigners Bill, 2025, introducing stringent measures to regulate immigration and oversee the movement of foreigners in India.
- Long-Term Vision: Aligns with India's goal of becoming a developed nation by 2047.
- Opposition MPs argue that the Bill gives unchecked authority to immigration officers.
- Demand for Further Scrutiny: Opposition sought referral of the Bill to a joint parliamentary committee, which was rejected. Amendments proposed by opposition members were negated.
Mental Health Insurance in India
- IRDAI mandates insurers to cover mental illness under the Mental Healthcare Act (MHCA), 2017, yet claims remain minimal.
- Less than 1% of total health insurance claims in India are for mental health treatment.
- 42% of survey participants were either unaware of their mental health coverage or did not have it.
- 6 policies (2 providers) explicitly excluded mental illness—violating MHCA and IRDAI guidelines.
Light Combat Helicopters
- Contract Signed with HAL: The Defence Ministry signed two contracts with Hindustan Aeronautics Ltd. (HAL) for the procurement of 156 indigenous Light Combat Helicopters (LCH) and associated training equipment.
- Indian Army: First LCH squadron raised on June 1, 2022, in Bengaluru, later moved to Misamari, Assam.
- First LCH squadron raised on June 1, 2022, in Bengaluru, later moved to Misamari, Assam.
- India’s Defence Ministry Signs ₹62,700 Crore Deal for 156 Light Combat Helicopters
Indian Ports Bill 2025
- Repeals the Indian Ports Act, 1908 to modernize port regulations.
- Union ports, shipping and waterways minister Sarbananda Sonowal introduced the Indian Ports Bill 2025 in the Lok Sabha, proposing several amendments to the 117-year-old legislation.
- Ownership & Control Regulations Mandatory central government clearance for any significant ownership/control changes.
- Mandatory central government clearance for any significant ownership/control changes.
Crore Electronics Component Manufacturing Scheme
- Scheme Approval: The Union Cabinet approved a ₹22,919-crore scheme to boost electronics component manufacturing over six years.
- Cabinet Approves ₹22,919-Crore Electronics Component Manufacturing Scheme
- Investment Generation: ₹59,350 crore in new investments.
- Production Boost: Expected to drive ₹4,56,500 crore in electronics production.
Gig Workers’ Registration on eShram
- The Parliamentary Standing Committee on Labour estimates that 35 lakh more gig workers will be eligible to register in FY26.
- Over 70,000 gig workers across 36 states/UTs have registered on the eShram portal to access social security and healthcare benefits.
- Low Registration Numbers: Despite millions of gig workers in India, only 70,000 have registered so far. The government must accelerate awareness campaigns and simplify the registration process.
- Ten major e-commerce platforms, including Zomato, Uber, Blinkit, Swiggy, Ola, and Rapido, have onboarded their workers.
India’s Carbon Market Expansion
- This step operationalizes India’s Carbon Credit Trading Scheme, first notified in June 2023, strengthening the institutional framework for carbon markets.
- The offset mechanism, introduced in December 2023, allows non-obligated entities to earn carbon credits through voluntary climate mitigation projects.
- Strengthens India’s Climate Commitments: Aligns with India’s Net Zero target for 2070 by incentivizing low-carbon technologies.
- Eight sectors have been identified, including renewable energy, green hydrogen, industrial energy efficiency, landfill methane recovery, and mangrove afforestation/reforestation.
Women’s Workforce Participation Rises to 25% in 2024: MoSPI Report
- Women’s workforce participation increased to 25% in 2024, up from 21.8% in 2019.
- Overall, employment-related activity participation increased to 49.9% in 2024 from 46.4% in 2019.
- Overall employment participation: Rose to 35.3% in 2024, from 34.1% in 2019.
- Men’s participation (aged 15-59) also rose to 75% from 70.9% in the same period.
Facts To Remember · 84
Starmer to host Ukraine summit tomorrow; NATO leaders to attend
- U.K. Prime Minister Keir Starmer will host a Sunday summit with over 45 European leaders to bolster support for Ukraine and discuss security. Ukrainian President Volodymyr Zelenskyy will attend, alongside NATO and EU leaders.
F1 Academy signs the 10-year-old Atiqa for its driver programme
- Atiqa Mir, the 10-year-old karting sensation, became the first Indian and Asian to be signed by Formula 1 Academy for its driver programme, a testament to her rapid growth in the world of motorsports.
Fiscal deficit hits ₹11.7 tn in April-Jan period of FY25
- India’s fiscal deficit for the April-January (FY25) period stood at₹11.70 trillion, 74.5% of the estimate for 2024-25, according to the data released by the Controller General of Accounts (CGA).
IMF approves and completes 3rd review of Sri Lanka’s 48-month Extended Fund Facility
- The International Monetary Fund (IMF) has approved and completed the third review of Sri Lanka’s 48-month Extended Fund Facility (EFF), enabling an immediate disbursement of approximately 334 million US dollars.
Sri Lanka gets fourth tranche of bailout package from IMF
- The IMF has agreed to release the fourth tranche of $334 million from its $2.9 billion bailout package to Sri Lanka to strengthen the island nation's recovery from its 2022 bankruptcy.
Uttarakhand approves ‘Mukhyamantri Ekal Mahila Swarozgar Yojana’
- The Uttarakhand government has approved the “Mukhyamantri Ekal Mahila Swarozgar Yojana,” aimed at empowering unmarried, divorced, abandoned, destitute, and differently-abled single women by providing them with financial assistance of up to 2 lakh rupees.
India’s R&D spending doubled in last decade: Union Minister Jitendra Singh
- Union Minister Dr. Jitendra Singh has said that the country’s Research and Development spending has doubled in the last decade, from more than sixty thousand crore in 2013-14 to 1.27 Lakh Crore rupees.
Health Minister JP Nadda chairs 9th Mission Steering Group Meeting of NHM
- Union Minister for Health and Family Welfare, Jagat Prakash Nadda, today chaired the 9th meeting of the Mission Steering Group of the National Health Mission (NHM) at Bharat Mandapam in New Delhi.
Arab leaders adopt Egypt’s Gaza reconstruction plan
- Arab leaders have approved a 53 billion dollar reconstruction plan for Gaza, that aims to avoid displacing Palestinians from the enclave. The plan was accepted at the closing of the emergency Arab summit in Cairo yesterday with full support from participating Arab leaders. Egyptian Foreign Minister Badr Abdelatty said that the plan includes the establishment of a seaport and an airport in the Gaza Strip and the recycling of the rubble left by the destruction in Gaza.
President Murmu to inaugurate “Nari Shakti Se Viksit Bharat” conference on Women’s Day
- President Droupadi Murmu will inaugurate a national conference in New Delhi on International Women’s Day on the 8th of this month. The Conference is being organised on the theme of “Nari Shakti Se Viksit Bharat” by the Women and Child Development Ministry.
RBI Governor engages with Fin-Techs, Payment System Operators
- Reserve Bank of India’s Governor Sanjay Malhotra held an interaction with non-bank Payment System Operators and FinTechs along with their associations and SROs yesterday.
South Korean fighter jets accidentally drop bombs, civilians among 15 injured
- Two South Korean Air Force fighter jets accidentally dropped eight bombs on a village during a joint training exercise with U.S. forces on Thursday, officials said, with civilians among 15 persons injured.
PM Narendra Modi launches various development projects at Silvasa in UT of Dadra & Nagar Haveli and Daman and Diu
- Prime Minister Narendra Modi inaugurated and laid the foundation stone for various projects worth 2,587 crore rupees at Silvasa in Daman, Diu, and Dadra Nagar Haveli.
Bihar boosts dairy exports: CM flags off Ghee, Gulab Jamun & Makhana shipments to USA, Canada
- In a major boost to the export of dairy products from Bihar, three consignments of Ghee, Gulab Jamun and Makhana worth over 48 lakh rupees were today flagged off to the USA and Canada.
RBI likely to cut rates by 50-75 bps in 2025-26 to support consumption: CRISIL Report
- The Reserve Bank of India (RBI) is expected to cut benchmark rates by 50-75 basis points during 2025-26 to support consumption and lower borrowing costs, credit rating Agency Crisil’s India Outlook 2025 report has said.
Aravindh Chithambaram leads Prague Chess Festival 2025 Masters
- At the 7th Prague International Chess Festival 2025 Masters, Indian Grand Master Aravindh Chithambaram drew with David Navara in the penultimate round and made a sole lead of 5.5/7 yesterday.
U.S. cancels $400 million in grants to Columbia
- U.S. President Donald Trump has cancelled grants and contracts totalling $400 million to Columbia University due to “inaction in the face of persistent harassment of Jewish students”, the Education Department said.
Myanmar will hold elections in January, says Min Aung Hlaing
- Myanmar's junta chief General Min Aung Hlaing said he would hold an election in December or January, the first in the war-torn nation since the military staged a coup in 2021.
54th National Safety Week being observed with theme ‘Safety & Well-being Crucial for Viksit Bharat’
- The 54th National Safety Week is being observed across the country. The week is celebrated between the 4th to 10th of March annually in the country, to raise awareness about safety precautions across various sectors.
India imposes anti-dumping duty up to $986/tonne on water treatment chemical from China, Japan
- India has imposed an anti-dumping duty of up to 986 US dollars per tonne for five years on a chemical, used for water treatment, imported from China and Japan to protect the domestic industry from cheap inbound shipments
President appoints Justice Bagchi to SC
- The President on Monday appointed Calcutta high court’s Justice Joymalya Bagchi to Supreme Court. Justice Bagchi is scheduled to become the Chief Justice of India on May 26, 2031, the second from Calcutta HC to rise to the top post in 40 years.
Govt advertises for Irdai chief post
- Finance ministry has invited applications for the post of chairman of the Insurance Regulatory and Development Authority of India (Irdai), with the position set to fall vacant on March 13, 2025, after Debasish Panda’s tenure ends.
Sun Pharma to buy US oncology firm for $355 million
- Sun Pharmaceutical Industries Ltd has agreed to buy US-based immunotherapy and oncology firm Checkpoint Therapeutics Inc. for an upfront payment of $355 million, as India’s largest drugmaker bolsters its specialty therapy portfolio.
EU chief calls for defence ‘surge’, says the ‘time of illusions’ is over
- EU chief Ursula von der Leyen called for a “surge” in European defence spending, as the 27-nation bloc faces an aggressive Russia and faltering U.S. support.
India, Qatar sign MoU for economic cooperation
- India and Qatar have signed an agreement to promote and develop mutual collaboration in publicprivate partnership framework and investment, use of financing tools, as well as economic policies, the finance ministry said.
Syria’s Jolani expected at Brussels donor summit in first Europe trip
- Syria’s interim President Abu Mohammad al-Jolani, also known as Ahmed al-Sharaa, is expected to attend a Brussels donor summit on March 17, his first European visit since becoming interim President after Bashar al-Assad’s ouster.
Google launches AI models for robotics
- CEO Tenure Cut: RBI recently approved only a one-year extension for current CEO Sumant Kathpalia, reducing his term to March 23, 2026. This is the second time RBI has shortened his tenure, previously cutting it to two years instead of three in 2023.
- 6. IIT-Delhi Leads Indian Institutes in QS World University Rankings by Subject
- 5. RBI Seeks External Candidates for IndusInd Bank CEO Role
Govt announces 1 billion dollar fund for creators’ economy, ahead of WAVES 2025
- Union Information and Broadcasting Minister Ashwini Vaishnaw has announced a 1 billion-dollar fund for the creator’s economy as part of the World Audio-Visual and Entertainment Summit (WAVES) 2025.
RBI Sets Final Redemption Price for Sovereign Gold Bonds (SGBs) at ₹8,624 per Unit
- Final Redemption Price: ₹8,624 per unit for SGBs maturing on March 17, 2025.
- Calculation Method: Based on the simple average of closing gold prices from March 10-13, 2025.
ISRO successfully conducts flight acceptance hot test of Cryogenic Engine for LVM3 launch vehicle in Tamil Nadu
- The Indian Space Research Organisation (ISRO) has successfully completed the flight acceptance hot testing of the cryogenic engine designated for the sixth operational mission of the LVM3 launch vehicle (LVM-M6).
India’s foreign exchange reserves surge by over 15 billion dollars, crossing 653 billion dollar mark
- India’s foreign exchange reserves surged by 15.26 billion dollars, reaching over 653.96 billion dollars in the week ending March 7, bolstered by the Reserve Bank of India’s (RBI) currency swap operations last month.
Pradhan Mantri Aawas Yojana-Gramin (PMAY-G) scheme
- A preliminary survey by the Odisha government has found that 44,743 rural households lack land, posing a major hurdle in providing houses under the Pradhan Mantri Aawas Yojana-Gramin (PMAY-G) scheme.
PM Modi commends RBI for being selected for Digital Transformation Award 2025
- Prime Minister Narendra Modi today commended the Reserve Bank of India for being selected for the Digital Transformation Award 2025 by Central Banking, London, UK.
Wholesale price inflation rises to 2.38% in February
- The Wholesale Price Index (WPI) inflation slightly increased to 2.38 per cent last month.
India’s first-ever comprehensive river dolphin survey estimated presence of 6,327 river dolphins across the country
- India’s first-ever comprehensive river dolphin survey has estimated the presence of 6,327 river dolphins across the country, with Assam recording 635 individuals in its five rivers.
Bajaj to buy out Allianz’s stakes in insurance JVs
- In the biggest insurance sector deal in India, Bajaj group will buy out Allianz’s 26% stakes in their life and non-life insurance ventures for Rs 13,780 crore and Rs 10,400 crore, respectively. The deal will make both insurers fully Indian-owned.
Public Sector Banks recover ₹2.27 lakh crore in written-off loans: FM Sitharaman
- Union Finance Minister Nirmala Sitharaman has said that Public Sector Banks have made the recovery of written-off loans worth over two lakh 27 thousand crore rupees.
Russia to participate in Smart Cities India Expo 2025
- A Russian delegation will participate in the Smart Cities India Expo 2025, which will be held from March 19 to 21 in New Delhi.
IOC Board approves boxing for inclusion in 2028 Los Angeles Olympic Games
- The International Olympic Committee (IOC) has approved the inclusion of boxing in the 2028 Los Angeles Olympics games.
GeM Surpasses ₹5 Lakh Crore GMV, Achieves Milestone in Public Procurement
- The Government e-Marketplace (GeM) has achieved a significant milestone by surpassing Rs 5 lakh crore in Gross Merchandise Value (GMV) on its portal before the close of the financial year 2024-25
PM-JAY to be implemented in Delhi from April 10: Minister
- Delhi Health Minister Pankaj Kumar Singh said a Memorandum of Understanding will be signed with the Centre on April 10 to extend the Union government’s health insurance scheme Ayushman Bharat Pradhan Mantri Jan Arogya Yojana to the city residents.
Sidbi Venture Cap Leads ₹16cr Round in Nourish You
- Superfood and plant-based nutrition startup Nourish You has raised ₹16 crore in its Series A funding round, led by Sidbi Venture Capital.
Book on India’s historic Hockey World Cup triumph releases
- India won its maiden Hockey World Cup in 1975 and a book about the historic triumph was released on Tuesday to commemorate the Golden Jubilee of the rare feat.
India, World Bank may sign $ 500 mn housing project
- The World Bank is in talks with the Union government to provide nearly $500 million in funding for the Sustainable Housing Integrated Efficient Living and DisasterResilience initiative under the Pradhan Mantri Awas Yojana Gramin (PMAYG).
Alphabet to acquire cybersecurity firm Wiz for $ 32 billion
- Alphabet said on Tuesday it would buy Wiz for about $32 billion in its biggest deal as the Google parent doubles down on cybersecurity to sharpen its edge in the cloudcomputing race against Amazon and Microsoft.
India aims for own space station by 2035, astronaut on moon by 2040
- India has planned to have its space station namely Bharat Antariksh Station and if all plan goes well an Indian astronaut will be on the Moon by 2040.
Khelo India Para Games 2025 launches anthem, mascot, logo
- Khelo India Para Games 2025 has launched its anthem, mascot and logo. The launch was done in the presence of Minister for Youth Affairs and Sports Dr. Mansukh Mandaviya in New Delhi yesterday.
SaaS Firm Icertis Steps Up AI Play with Agentic Platform
- Partnerships and Integration: Collaborating with other companies and new-age AI startups. Aims to integrate AI solutions directly into enterprise workflows.
- Aims to integrate AI solutions directly into enterprise workflows.
Ramnath Goenka Awards given to The Hindu journalists
- Two journalists at The Hindu were felicitated by President Droupadi Murmu at the 19th Ramnath Goenka Excellence in Journalism Awards 2025. Maitri Porecha, senior assistant editor, won the award for Politics and Government in the print category, and Satyasundar Barik, The Hindu’s Odisha correspondent, won the award in the Uncovering Invisible India category.
Fitch Ratings retains India´s FY26 GDP forecast at 6.5%
- Fitch Ratings has kept India´s GDP growth forecast for financial year 202526 (FY26) unchanged at 6.5 per cent and revised upwards its FY27 growth projection by 10 basis points to 6.3 per cent in its March Global Economic Outlook report.
Reserve Bank of India appoints Indranil Bhattacharyya as Executive Director
- The Reserve Bank of India (RBI) has appointed Indranil Bhattacharyya as Executive Director (ED), effective March 19, 2025, the banking regulator said in a statement. In his new role as ED, Bhattacharyya will look after the Department of Economic and Policy Research.
World Sparrow Day being observed to raise awareness on sparrow conservation
- World Sparrow Day is being observed worldwide today, marking an annual effort to raise awareness about the rapid decline in sparrow populations. Celebrated every year on March 20, the day was first observed in 2010 across various parts of the world.
Corporate Affairs Ministry hosts 2nd open house for PM Internship Scheme
- Ministry of Corporate Affairs hosted its second open house for the PM Internship Scheme to engage and support eligible candidates of the scheme.
Centre approves revised Rashtriya Gokul Mission to boost growth in livestock sector
- The government has approved the revised Rashtriya Gokul Mission to boost growth in the livestock sector. The implementation of the revised mission is being carried out with an additional outlay of one thousand crore rupees.
Indian economy continues to show resilience amid global challenges: RBI
- The Reserve Bank’s monthly bulletin for March 2025 states that the Indian economy continues to demonstrate resilience despite global challenges. According to an article titled “State of the Economy” in the bulletin, the global economy is being tested by escalating trade tensions and a heightened wave of uncertainty around the scope, timing, and intensity of tariffs.
Tuberculosis cases in India decline more than double global reduction rate: MoS Health Anupriya Patel
- The government has said that India is moving fast to become a TB-free nation this year. The incidence rate of TB in the country has shown a 17.7 per cent decline from 237 per lakh population in 2015 to 195 per lakh population in 2023, which is more than double the global reduction.
India submits bid to host 2030 Commonwealth Games in Gujarat
- India has taken a major step toward hosting global sporting events by officially submitting an expression of interest to organize the Centenary Commonwealth Games in Ahmedabad, Gujarat, in 2030.
Namibia inaugurates its first woman President Nandi-Ndaitwah
- Namibia on Friday inaugurated its first female President, Netumbo Nandi-Ndaitwah, aged 72, extending SWAPO’s 35-year rule.
Forex reserves climb to over 3 month high
- The country´s foreign exchange reserves rose by $300 million toa more than threemonth high of $654.27 billion as of March 14, data released by the Reserve Bank of India (RBI).
India’s GDP Doubles in a Decade, Set to Overtake Japan: IMF
- India has doubled its Gross Domestic Product (GDP) in the last 10 years at a growth of 105 percent, from 2.1 trillion dollars in 2015 to 4.3 trillion dollars in 2025.
Oeko-Tex Certification for Eri Silk
- The North Eastern Handicrafts and Handlooms Development Corporation Ltd. (NEHHDC), functioning under the Ministry of Development of North Eastern Region, obtained the internationally recognized Oeko-Tex certification for eri silk from Germany in March 2025.
India-EU Hold 4th Maritime Security Dialogue
- The 4th India-EU Maritime Security Dialogue was held in New Delhi yesterday. The Indian delegation was led by Joint Secretary (Disarmament and International Security Affairs) in Ministry of External Affairs, Muanpuii Saiawi and the EU delegation by Director for Security and Defence Policy, European External Action Service, Maciej Stadejek.
Kotak Mahindra Bank appoints Bhavnish Lathia as CTO
- Kotak Mahindra Bank’s board of directors, at their meeting on Saturday, appointed Bhavnish Lathia as the new Chief Technology Officer (CTO) and Vyomesh Kapasi as a member of the Group Management Council.
₹144 Crore Disbursed to Farmers for Border Fencing Land: CM Omar Abdullah
- In Jammu and Kashmir, Chief Minister Omar Abdullah today said that over 144 crore Rs. have been disbursed to farmers whose lands were affected by fencing along the International Border (IB).
India clinches both Men’s & Women’s Kabaddi World Cup 2025
- India has clinched both the Men’s and Women’s Kabaddi World Cup 2025 at Wolverhampton in England. The Men’s team defeated the home side England in the final match 44-41.
India Wins Silver in Women’s Doubles, Bronze in Men’s at ISTAF Sepak Takraw World Cup 2025
- In the Doubles events category of the ISTAF Sepak Takraw World Cup 2025 at Patna, the Indian Women’s team showcased splendid gameplay by winning the silver medal.
Nation Remembers Bhagat Singh, Rajguru & Sukhdev on Martyrs’ Day; PM Modi Pays Tribute
- The Nation is paying homage to the three of its heroic revolutionaries of the Indian freedom struggle – Shaheed-E-Azam Bhagat Singh, Shivaram Rajguru and Sukhdev Thapar – who were executed at the Central Jail in Lahore on this day in 1931.
Lok Sabha Passes Finance Bill 2025, Tax Relief Up to ₹12 Lakh Announced
- The Lok Sabha has passed the Finance Bill, 2025. The Bill seeks to give effect to the financial proposals of the Central Government for the financial year 2025-2026.
1,737 Gram Panchayats developed under ‘Sansad Adarsh Gram Yojana’ since 2014: Govt
- The government has said that one thousand 737 Gram Panchayats across the country have been developed under the ‘Sansad Adarsh Gram Yojana’ so far by completing the projects and activities planned under the Village Development Plan.
Nagaland govt to set up Solar Mission team for PM Surya Ghar Muft Bijli Yojana implementation
- The Nagaland government will set up a Solar Mission Team at the Directorate level and a Solar Mission Cell at the Secretariat level to oversee the implementation of the PM Surya Ghar Muft Bijli Yojana.
BCCI announces Indian Women’s team retainership for 2024-25
- The Board of Control for Cricket in India (BCCI) has announced the retainers for the Indian Women’s team for the 2024-25 season, covering the period from the 1st of October, 2024 to 30th of September, 2025.
Irdai: SwaminathanS Iyer appointed as member
- The Appointments Committee of the Cabinet (ACC) has approved the appointment of SwaminathanS Iyer as Whole Time Member (Life) of the Insurance Regulatory and Development Authority of India (Irdai). He is appointed for five years from the date of assumption of charge or until he attains the age of 62 years or until further orders, whichever is the earliest.
Groww to raise $250mn led by GIC at $6.8bn valuation
- Investment platform Groww is in the process of raising a pre-IPO funding of about $250 million, from a bunch of investors led by Singapore’s sovereign wealth fund GIC, at a valuation of $6.8 billion, said sources familiar with the matter.
Over 4000 children adopted in country in financial year 2023-24: Union Minister Savitri Thakur
- Over four thousand children were adopted in the country in the financial year 2023-24. This was stated by the Minister of State in the Women and Child Development Ministry, Savitri Thakur, in a written reply in Rajya Sabha today.
Regulations should not create ‘unintended barriers’ to deepening financial inclusion: RBI Governor Sanjay Malhotra
- Reserve Bank of India Governor Sanjay Malhotra has emphasised that regulations should not create “unintended barriers” to deepening financial inclusion.
ILO says, India’s social security coverage doubled from 24.4 % in 2021 to 48.8 % in 2024
- India’s social security coverage has seen a significant rise. According to International Labour Organization (ILO), India’s social security coverage has doubled from 24.4 percent in 2021 to 48.8 percent in 2024.
India achieves significant milestone in global tea industry, becomes world’s 2nd-largest exporter of tea in 2024
- India has achieved a significant milestone in the global tea industry, surpassing Sri Lanka to become the world’s second-largest exporter of tea in 2024.
India wins 2nd bronze in Senior Asian Wrestling Championship 2025
- Indian wrestlers continued their good run on the second day of the Senior Asian Wrestling Championship 2025, with Nitesh clinching the second bronze medal for the country in Amman, Jordan, yesterday.
Tamil Nadu Assembly Adopts Resolution Against Waqf (Amendment) Bill, 2024
- The Tamil Nadu Assembly, led by Chief Minister M.K. Stalin, passed a Special Government Resolution urging the Centre to withdraw the Waqf (Amendment) Bill, 2024.
PM Modi to visit Thailand for BIMSTEC summit, followed by Sri Lanka State visit
- Prime Minister Narendra Modi will travel to Bangkok, Thailand, for a two-day visit from April 3rd to participate in the 6th BIMSTEC Summit.
Over 8.9 crore hospital admissions authorized under Ayushman Bharat: Health Minister JP Nadda
- Health Minister JP Nadda today said that more than 8.9 crore hospital admissions worth 1.26 lakh crore rupees have been authorized under Ayushman Bharat -Pradhan Mantri Jan Aarogya Yojana as of 1st March this year.
Nod for ₹37,216-cr. fertilizer subsidy during kharif season
- The Union Cabinet, on Friday, approved the nutrient-based subsidy rates for the upcoming kharif season on phosphatic and potassic (P&K) fertilizers. The budgetary requirement for this subsidy will be ₹37,216.15 crore.
Elon Musk Sells X to xAI in $33 Billion Deal
- Tech billionaire Elon Musk has sold social media site X to his own xAI artificial intelligence company in a 33 billion US dollars deal, the billionaire announced last night.
Manisha Bhanwala clinches India’s first gold medal in Asian Wrestling Championship
- In the Asian Wrestling Championship-2025, Manisha Bhanwala clinched India’s first gold medal since 2021 edition, while Antim Panghal settled for a bronze at Amman in Jordan on Friday night.
Banking/Finance · 173
The Matched Plan of SEBI on Mutual Fund Insurance
- Proposed by Former SEBI Chairperson Madhabi Puri Buch (January 2025) to make investments more affordable and accessible.
- Investor Base Expansion Efforts Such initiatives like reducing the minimum investment from ₹500 to ₹250 are meant to attract a large retail market.
- Such initiatives like reducing the minimum investment from ₹500 to ₹250 are meant to attract a large retail market.
- Past Experience Earlier, many such combo products were available till June 2022, when SEBI banned them on account of structural concerns.
SEBI to Appeal Against Court Order on Alleged Listing Permission Irregularities
- The complaints levelled against the accused have to do mostly with irregularity in granting listing permission almost 30 years ago.
- The Securities and Exchange Board of India (SEBI) has expressed that it will now appeal an injunction of the Higher Court directing the police in the alleged listing irregularities regarding a company's BSE listing in 1994.
- The institution's focus is on former SEBI chairperson Madhabi Puri Buch, three current whole time members, and two BSE officials.
- Doubtful Applicant SEBI calls the complainant a frivolous and habitual litigant; they are in the know that similar matters of previous applications being dismissed.
RBI's Harsh Accommodative Stance Under Governor Sanjay Malhotra
- First rate cut in five years The Monetary Policy Committee (MPC) cut the repo rate by 25 basis points (bps) in February, which marks the beginning of a move towards a less restrictive monetary policy.
- Liquidity deficit soared up to ₹3 trillion in January, highest since April 2010.
- Relaxed risk weightings on loans to NBFCs & Microfinance Institutions (MFIs) from 125% to 100% → Injecting ₹40,000 crore into banking (~₹4 trillion in loanable funds).
- India’s GDP growth fella at 5.4% (seven quarter low) in July September.
Irdai's Move toward Equity Derivatives
- Life insurers generally assign 30-35% of their portfolio to equities, with the remaining portion in fixed income instruments. This is probably higher than general insurers and hence gives them more exposure to equity market risks.
- The average equity to debt ratio is 35:65, with substantial variation across insurers.
- Interest rate derivatives in rupees, consisting of: Forward Rate Agreements (FRAs) Interest Rate Swaps Exchange Traded Interest Rate Futures (IRFs) Credit Default Swaps (CDS) for protection to buyers.
- Credit Default Swaps (CDS) for protection to buyers.
Financial Frankenstein
- Drowning under constant for fee based income, banks persuaded heavily into mutual fund and insurance sales through their branches. By the time they realized their folly, it was all too late.
Strategies in Response
- The CASA Ratio of a bank determines its ability to keep its cost of funds low. A healthy CASA balance can ensure a bank gives a net interest margin (NIM) of around 4% without posing a threat to asset quality.
- Private Banks Offer higher interest rates (up to 8%) to lure depositors.
- Offer higher interest rates (up to 8%) to lure depositors.
- Innovative Approaches Banks are exploring giving incentives like insurance covers, discounts for retail loans, and premium banking benefits.
Virtual Digital Assets (VDAs)
- VDA dealers (such as exchanges, wallet providers, and traders) must report transactions in a prescribed format (Section 509).
- Legal Classification & Taxation For the first time, the VDAs have been explicitly classified in India as: Property (Section 92(5)(f)) Capital Assets (Section 76(1))
- Fixed 30% tax on income arising from the transfer of VDAs (no deductions allowed, except for the cost of acquisition).
- Tax Deducted at Source (TDS) at the rate of 1% will be applicable to all transactions involving VDAs, including peer to peer (P2P) transactions.
| Country | Legal Status of VDAs | Tax Treatment |
|---|---|---|
| U.K. | Property | Subject to Capital Gains Tax (CGT) |
| U.S. | Securities | Regulated under SEC financial market laws |
| New Zealand | Property | Subject to income tax on trades |
| UAE | Regulated by VARA | 0% personal income tax on certain gains |
Slow IPO Market
- Brokerage Stocks Suffered An onslaught of selling for a long period combined with possible SEBI changes in regulations related to the derivatives markets meant declines of up to 18% in a couple of brokerage stocks.
- An onslaught of selling for a long period combined with possible SEBI changes in regulations related to the derivatives markets meant declines of up to 18% in a couple of brokerage stocks.
- Just 14 companies filed Draft Red Herring Prospectus (DRHP) forms in February as opposed to 29 in January, the lowest ever to show since November 2024.Decline in Fundraising: The overall amount being sought for IPOs dipped to ₹9,695 crore, which is a low of 9 months.
- Political Uncertainty The apprehension of investors has heightened since the likely return of Donald Trump to the White House in January.
Bank Deposit Insurance
- Current Coverage Deposit insurance covers "principal + interest" up to ₹5 lakh per bank. If ₹5 lakh is principal, forfeiture of interest in a bank failure.
- Deposit insurance covers "principal + interest" up to ₹5 lakh per bank.
- If ₹5 lakh is principal, forfeiture of interest in a bank failure.
- Risk Management Strategies for Depositors Distributing deposits among multiple banks reduces risk exposure. Different sequences of joint accounts: They will be insured separately for ₹5 lakh each.
Multi-Asset Allocation Fund (MAAF)
- The Taxation Impact on Asset Allocation Equity taxation: Requires minimum 65% allocation to equities. Hybrid taxation: Requires at least 35% equity exposure.
- Equity taxation: Requires minimum 65% allocation to equities.
- Hybrid taxation: Requires at least 35% equity exposure.
- Risk Appetite Matching MAAF Selection Investors with higher risk tolerance might prefer an equity oriented scheme with a longer investment horizon. Those who are conservative and are looking for a shorter time frame would have gone for debt heavy MAAFs.
SEBI Consultation Paper Regarding Market Regulations
- SEBI states that 89% of index derivative positions in November were within the proposed limit, meaning only 11% exceeded it.
- Top stock weight capped at 20% (vs. HDFC Bank's present 33% in Nifty Bank)
- SEBI has proposed a limit of ₹500 crore net future equivalent for each entity.
- The intention behind the ruling is to prevent systemic risks should OI exceed ₹10,000 crore, which is a rare occurrence.
Mitraa Platform
- Pre 2006 MF Accounts Lacked PAN Requirement Prior to PAN becoming a mandatory requirement in 2006, a number of mutual fund investors opened accounts unlinked to PAN. Consequently, such accounts practically became dormant, leaving them difficult to trace.
- Prior to PAN becoming a mandatory requirement in 2006, a number of mutual fund investors opened accounts unlinked to PAN.
- Under this definition, SEBI termed an inactive folio wherein the investor has not initiated any transactions (financial or otherwise) for 10 years but still holds units.
- Search Parameters Primary Identifiers: PAN, registered phone number, email, or bank account number. Additional Identifiers: Name, address, PIN code, city or nominee details. Investors can visit MFcentral.com to access Mitraa.
RBI to Inject Rs. 1.9 Trillion in Banking System
- Rupee Gains in a Weaker Dollar On March 5, 2025, the rupee appreciated by 0.36% from 87.27/USD to 86.96/USD.
- On March 5, 2025, the rupee appreciated by 0.36% from 87.27/USD to 86.96/USD.
- The Reserve Bank of India (RBI) announced on Wednesday its its plan to infuse Rs 1.9 lakh crore into the banking system through open market purchases of government securities and USD/INR swaps in March.
- Liquidity Measures By RBI "OMO Auctions" of 60,000 crores worth of buying government securities in 3 tranches.
RBI Announces G-Sec Purchases
- Open Market Purchase of Government Securities (G-Secs) worth ₹1 Lakh Crore.Liquidity injection to be conducted in two tranches:- ₹50,000 crore on March 12- ₹50,000 crore on March 18Forex Swap of $10 billion (36 month tenor) on March 24.
Fintech Engagement by RBI
- The discussions saw participation from the Deputy Governors M. Rajeshwar Rao, T Rabi Sankar, Swaminathan J., and executive directors.
- Expansion of use cases for central bank digital currency (CBDC).
- CBDC Use Cases Bank of Baroda modeled a small merchant loyalty program on CBDC for banks.
- Bank of Baroda modeled a small merchant loyalty program on CBDC for banks.
SEBI Issues Warning Against Sunshine Global Agro Property Transactions
- 2019 Directive: SEBI barred the company and its directors from selling or disposing of assets, except for refunding investors.
- 2014 Ban: SEBI prohibited Sunshine Global Agro (formerly Sunshine Forestry Pvt. Ltd.) from raising funds from investors or launching any new schemes. The company was found to be running an unauthorized Collective Investment Scheme (CIS) involving the sale of Jatropha Bush Groups and plant/trees.
- Markets regulator SEBI has warned the public against buying or dealing with properties owned by Sunshine Global Agro and its directors.
- Non-Compliance & Recovery Action: After Sunshine Global Agro failed to comply, SEBI initiated recovery proceedings against the company and its directors.
RBI Moves to Boost Liquidity
- Liquidity swung from a ₹1.35 trillion surplus in Nov 2024 to a ₹2.07 trillion deficit in Jan 2025, improving to ₹1.59 trillion deficit in Feb 2025.
- 7.10% GS 2029
- 7.18% GS 2033
- 7.10% GS 2034
Digital Footprint-Based Credit Assessment Model for MSMEs
- Announced in: Union Budget 2024-25
- Automated loan assessment for both: Existing to Bank (ETB) borrowers New to Bank (NTB) borrowers
- Existing to Bank (ETB) borrowers
- New to Bank (NTB) borrowers
SEBI’s New Chairperson Prioritizes “Optimum Regulation”
- Former SEBI Chairperson Madhabi Puri Buch faced scrutiny over alleged offshore fund holdings and a stake in an advisory firm, raising concerns about SEBI’s objectivity.
- Pandey, in his first public address, emphasized that transparency must extend to SEBI itself.
- SEBI acknowledges the stability provided by domestic institutional investors (DIIs) while recognizing the need to attract Foreign Portfolio Investors (FPIs).
- Financial inclusion initiatives include: Low-value mutual fund SIPs (to encourage retail investment). SME REITs (to widen investment options for small investors). Specialized investment funds (catering to niche investor segments).
RBI’s Gold Reserves
- The Reserve Bank of India (RBI) has been aggressively increasing its gold reserves since 2020, making it the second-largest buyer globally after China. This shift signals a deeper strategic and economic intent beyond mere diversification.
- India is the second-largest gold buyer (post-2020), trailing only China. Total gold added (2020-2024):
- India: 244 tonnes
- China: 336 tonnes
Nestlé India Receives SEBI Warning Over Insider Trading Breach
- Compliance Officer Notified: Nestlé India's compliance officer received the administrative warning letter from SEBI on Thursday.
- Limited Disclosure: Nestlé India did not disclose the findings of the letter. The identity of the person involved remains undisclosed.
- The identity of the person involved remains undisclosed.
- No Immediate Response: Nestlé India has yet to provide an official comment to Reuters.
RBI’s VRR Auctions Signal Easing Liquidity Tightness
- Dividend Transfers from RBI (May 2025) Expected to further boost liquidity, potentially allowing for more accommodative monetary policies.
- Ensuring Policy Transmission: RBI’s priority is to make sure the recent repo rate cut (first in 5 years) translates into lower borrowing costs.
- Despite offering substantial funds, banks have shown reduced appetite for liquidity through VRR auctions. This shift implies that the liquidity crunch, which had been a major concern since late 2024, is easing. The banking sector appears to have sufficient funds, diminishing the need for borrowing from RBI.
Futures and Options (F&O) Trading
- Profit & Loss If the market price rises above the agreed price, the buyer profits while the seller incurs a loss. The seller profits and the buyer incurs loss if the market price tumbles.
- If the market price rises above the agreed price, the buyer profits while the seller incurs a loss.
- The seller profits and the buyer incurs loss if the market price tumbles.
- Use Cases Traders and institutions use it frequently for hedging against price fluctuations or speculating about their possible price changes in the future.
| Feature | Futures | Options |
|---|---|---|
| Obligation | Buyer and seller must execute contract | Buyer has a choice; seller is obligated if exercised |
| Risk | Unlimited for both parties | Limited for buyer, unlimited for seller |
| Profit Potential | Depends on price movement | Buyer’s profit depends on market movement, seller gains limited to premium |
| Flexibility | No flexibility; must settle at expiry | High flexibility; can expire worthless or be exercised |
| Cost | No upfront premium, margin required | Buyer pays a premium, which is the maximum loss |
Issues for the New SEBI Chief to Address
- Investor education has been underfunded, with only ₹2.8 crore allocated in 2023-24.
- Small investors’ participation is crucial for market stability, and their education must be prioritized.
- India lacks a strong network of trained and ethical investment advisors, particularly in rural areas.
- The SMARTS program, aimed at training advisors, needs more momentum to replace product pushers.
SBI Asmita Digital SME Loan & Nari Shakti Debit Card
- Eco-friendly card: Made from 100% recycled plastic.
- 100% locker rent concession.
- State Bank of India (SBI) has launched two women-centric financial products: ‘SBI Asmita’: A collateral-free digital SME loan for women entrepreneurs. ‘Nari Shakti’ Platinum Debit Card: A RuPay-powered debit card catering to women's financial needs.
- Special Add-On: Top-performing women entrepreneurs under the scheme will receive entrepreneurial and management training.
US Creates Strategic Crypto Reserve
- Trading Volume Surge: The announcement led to an inflow of nearly ₹300 billion overnight in the crypto market.
- Exposure Limit: Crypto allocation should not exceed 15% of an investor's portfolio.
- Flat 30% Tax on crypto profits, plus surcharge and cess.
- Tax Deducted at Source (TDS) of 1% applies to most transactions.
SEBI's Proposed Short selling Reforms
- Current Provision Penalty leviable 0.05% on the value of shortages for failed deliveries. The exchange must initiate action against brokers for the failures related to settlements.
- Penalty leviable 0.05% on the value of shortages for failed deliveries.
- At Present The institutional trader must disclose upfront any transaction qualifying as a short sale. The retail trader must report by the end of the day. Weekly short sale position reporting is done by brokers and exchanges.
- Proposed Broaden short selling to cover all stocks except for the ones in the Trade to Trade(T2T) segment.
SEBI Tightens Rules on SME IPOs
- Existing shareholders are prevented from offloading greater than 20 percent of shares within the context of an SME-IPO limitation.
- Capping Offer for Sale (OFS) to 20% Existing shareholders are prevented from offloading greater than 20 percent of shares within the context of an SME-IPO limitation. Ensure the company will raise fresh capital rather than just allowing early investors to exit.
- Ensure the company will raise fresh capital rather than just allowing early investors to exit.
- IPO proceeds are used for business growth rather than exit of existing shareholders.
SME-IPO Boom Amid Mainboard Slowdown
- Investor Appetite for High-Growth Companies SMEs, often in emerging sectors, present high-growth opportunities that attract investors willing to take calculated risks. The retail investor base, particularly in Tier 2 and Tier 3 cities, is increasingly participating in SME IPOs, fueling demand.
- SMEs, often in emerging sectors, present high-growth opportunities that attract investors willing to take calculated risks.
- The retail investor base, particularly in Tier 2 and Tier 3 cities, is increasingly participating in SME IPOs, fueling demand.
- Investors remain selective about mainboard IPOs, focusing on profitability and sustainability rather than mere growth prospects.
| Month | SME IPOs | Funds Raised (₹ Cr) | Mainboard IPOs | Funds Raised (₹ Cr) |
|---|---|---|---|---|
| January | 20 | 880 | 6 | 4,845 |
| February | 20 | 930 | 3 | 10,878 |
| March (as of March 11) | 6 | 170 | 0 | 0 |
Regulatory Concerns in the SME IPO Segment
- The BSE SME IPO index (tracking prices of SME-listed stocks) rose 2.5 times in 2024, compared to a 32% increase in the BSE IPO index for mainboard companies.
- Exponential Growth in Retail Participation The average number of retail applications per SME IPO surged from 297 in 2020 to 188,000 in 2024. This increase is largely driven by listing gains that have jumped from 1% to 60% in the same period.
- However, despite past success, SME IPOs have recently experienced a sharp correction. On a year-to-date basis, the BSE SME IPO index is down by 26%, while the mainboard index has declined by 19%.
- This increase is largely driven by listing gains that have jumped from 1% to 60% in the same period.
Indian Banks Struggle to Boost Deposit Growth Amid Rising Loan Demand
- As of February 7, 2025, the incremental LDR (rolling 3-month basis) hit 126%, meaning banks are loaning out ₹126 for every ₹100 in fresh deposits.
- Overall, fiscal year LDR stands at 103%, signaling a persistent weakness in deposit mobilization.
- Credit growth (YoY): 11.3%
- Deposit growth (YoY): 10.6%
MDR on UPI & RuPay Debit Card Transactions
- Threshold for applicability: Merchants with GST-based annual turnover of more than ₹40 lakh.
- What MDR percentage will be charged? Industry speculation suggests 0.3% to 1%, but no official figure has been proposed yet.
- Industry speculation suggests 0.3% to 1%, but no official figure has been proposed yet.
- Impact on Merchants: Large businesses may pass the MDR cost onto consumers via higher prices. Some merchants may discourage UPI transactions in favor of cash or other low-cost alternatives.
Software as a Service (SaaS)
- B2B stands for business-to-business, which refers to the exchange of products, services, or information between businesses. It's different from business-to-consumer (B2C), which is when a business sells to an individual.
- B2B transactions can involve the purchase of raw materials, outsourcing tasks, or enhancing products.
- B2B transactions are part of the supply chain, which moves goods and services from supplier to customer.
- B2B transactions are often driven by cost-effectiveness, quality, reliability, and long-term business relationships.
Household Debt in India
- On one hand, household borrowing is increasing, but on the other hand, household assets are on the decline (110.4% of GDP in 2021→108.3% in 2024).
- Since September 2023, credit control measures introduced by the RBI have had the effect of tightening borrowing among sub prime borrowers.
- Delinquencies in personal loans and credit cards rose in September 2024, which indicates financial stress is rising.
- Prime Borrowers 64% of their loans are for asset utilization.
Alternative Investment Funds (AIFs)
- Investor cap per scheme: Maximum 1,000 investors (except Angel Funds, which allow up to 49).
- AIFs operate under the SEBI (Alternative Investment Funds) Regulations, 2012 and can be structured as a company, Limited Liability Partnership (LLP), trust, or other legal entities.
- Angel Funds Invest in early-stage start-ups that lack access to venture capital. Minimum investment per angel investor: ₹25 lakh.
- Minimum investment per angel investor: ₹25 lakh.
IndusInd Bank Stock Crashes 27%
- Estimate of Losses The bank recorded a 2.35% hit to its net worth as of December 2024 due to derivative losses.
- The bank recorded a 2.35% hit to its net worth as of December 2024 due to derivative losses.
- Stock Plunge IndusInd Bank's shares crashed by 27%, which meant market value being wiped away worth ₹19,000 crores.
- IndusInd Bank's shares crashed by 27%, which meant market value being wiped away worth ₹19,000 crores.
Unified Lending Interface (ULI)
- 0.6 million loans worth ₹27,000 crore disbursed via ULI as of December 2024.
- 36 lenders, including banks and NBFCs, onboarded.
- Dynamic Recollection Models Exploring variable repayment plans based on weekly/monthly earnings of borrowers.
- Exploring variable repayment plans based on weekly/monthly earnings of borrowers.
IRDAI Allows Bond Forwards for Insurers
- Insurers can only take long positions in bond forwards and must report transactions quarterly.
- Experts believe bond forwards could replace FRAs, making them redundant for insurers.
| Feature | Bond Forwards | Forward-Rate Agreements (FRAs) |
|---|---|---|
| Settlement Type | Actual bond delivery at maturity | Cash settlement based on yield difference |
| Market Availability Risk | Lower risk (bond is pre-contracted) | Higher risk (insurers must procure bond separately) |
| Preferred By Insurers? | Yes, due to reduced settlement risks | Becoming less attractive |
SEBI Reduces Rights Issue Processing Time
- Faster Rights Issue Timeline Reduced from an average of 317 days to just 23 working days. Faster than preferential allotment, which takes 40 working days.
- Reduced from an average of 317 days to just 23 working days.
- Faster than preferential allotment, which takes 40 working days.
- Flexibility in Allotment Companies now have more freedom to allot shares to specific investors in a rights issue.
RBI Investigates Unhedged Forex Liabilities in Banking System
- Internal review uncovered discrepancies in derivative portfolio, potentially impacting 2.35% of net worth (~₹1,600 crore loss in Q4 FY24).
- Review triggered by an RBI circular (Sept 2023), prompting scrutiny of derivative practices.
- 3 to 6-year yen borrowings and 8 to 10-year dollar borrowings.
- Issues stemmed from internal trades using low-liquidity forex instruments: 3 to 6-year yen borrowings and 8 to 10-year dollar borrowings. Instead of hedging directly with external counterparties, the bank used internal desks. Discrepancies arose due to differences between swap valuations and mark-to-market pricing.
The Credit-Deposit (CD) Ratio
- Example: A bank with a CD ratio of 75% means that three-fourths of its deposits have been used for lending.
- HDFC Bank repurchased nearly ₹7,000 crore worth of its high-cost bonds in the last six months. Move aimed at lowering its credit-deposit (CD) ratio, which surged to 110% post-merger with Housing Development Finance Corp (HDFC) in July 2023. Bond buyback represents a small fraction of HDFC Bank’s ₹4 lakh crore outstanding borrowings (March 2024).
- Some experts say that an ideal CD ratio would be between 65% and 75%
- The Credit-Deposit (CD) ratio measures the proportion of a bank's total deposits that have been disbursed as loans, reflecting how efficiently a bank uses its deposits to generate income and indicating its liquidity and credit risk.
Self-Regulatory Organization (SRO)
- Financial Industry Regulatory Authority (FINRA) – Regulates broker-dealers in the U.S.
- The Reserve Bank of India (RBI) invited applications from entities to becomea self regulatory organization (SRO) in the account aggregator (AA) space by June 15. According to RBI, the AA ecosystem is distinct in its complexity, involving exchange of data amonga diverse array of regulated entities (REs) operating under varied regulatory environments.
- Governmental Oversight: Though independent, SROs often operate under regulatory supervision.
- Regulation & Compliance Members must adhere to established rules. Violations can lead to penalties or expulsion.
| Feature | SROs | Government Regulators (e.g., SEC) |
|---|---|---|
| Authority | Industry-based | Legislative mandate |
| Oversight | Self-governed, with some external regulation | Fully government-controlled |
| Compliance Enforcement | Member-driven | Legally binding |
| Examples | FINRA, NYSE, AMFI | SEC, RBI, EU regulators |
Corporate Bond Market Sees Heavy Issuances
- Canara Bank’s ₹ 4,000 crore Tier-II bond issuance signals that banks are securing capital buffers amid regulatory shifts and potential asset quality risks.
- Liquidity Tightening & Advanced Tax Outflows System liquidity deficit exceeds ₹ 1 trillion, exacerbated by tax outflows and sustained credit demand. The RBI’s ₹ 50,000 crore OMO may provide short-term relief, but liquidity constraints will likely persist.
- System liquidity deficit exceeds ₹ 1 trillion, exacerbated by tax outflows and sustained credit demand.
- The RBI’s ₹ 50,000 crore OMO may provide short-term relief, but liquidity constraints will likely persist.
SEBI’s New RPT Disclosure Norms
- On February 14, 2024, the Securities and Exchange Board of India (SEBI) issued stricter disclosure requirements for Related-Party Transactions (RPTs) to
- At a March 5 governance and risk management event, he remarked:“If you take these rules seriously, you will have a problem. It is better to read them, laugh at them, and move on.”
- Increased transparency Stricter disclosures may reduce conflicts of interest and protect minority shareholders.
- Stricter disclosures may reduce conflicts of interest and protect minority shareholders.
RBI Examines Banks Derivatives Exposures
- On March 11, 2024, IndusInd Bank admitted a forex derivatives accounting lapse.
- This resulted in a 2.35% reduction in its net worth, prompting regulatory scrutiny.
- Before April 1, 2024, banks were allowed to engage in internal swaps, where one cash flow is exchanged for another.
- India’s central bank, the Reserve Bank of India (RBI), has launched a review of derivatives exposures at both private and state-run banks. This follows IndusInd Bank’s recent disclosure of lapses in its forex derivatives accounting, leading to a 2.35% hit to its net worth. The RBI seeks to determine whether this issue is isolated or part of a broader risk across the banking sector.
LIC, New India Assurance, GIC Re remain D-SIIs
- State-owned insurers LIC, The New India Assurance, and GIC Re have retained their D-SIIs designation for 2024-25, as per IRDAI. Implications of D-SIIs Status:
- Significance: First private reinsurer licensed under the revamped regulatory framework. ₹210 crore initial paid-up capital for operations. Strengthens competition in India’s reinsurance sector.
- ₹210 crore initial paid-up capital for operations.
- These insurers are considered crucial to financial system stability due to their size and market influence.
RBI Nears Finalization of Climate Risk Disclosure
- Following public consultations on the draft framework (February 2024), RBI is now incorporating feedback for final guidelines.
- The Reserve Bank of India (RBI) is close to finalizing climate risk disclosure norms for regulated entities and preparing a guidance note for lenders to conduct climate scenario analysis and stress testing, Governor Sanjay Malhotra announced on Thursday.
- Collaboration among financial sector regulators, regulated entities, and government agencies is crucial for effective risk mitigation.
- Collaboration with the government and regulators to ensure harmonization and consistency in climate policies.
RBI's Rate Cut Trajectory
- February 2025 CPI inflation: 3.61% (lowest since July 2024), down from 4.3% in January.
- In February 2025, the RBI cut the repo rate by 25 bp to 6.25%, marking its first rate reduction in nearly five years.
- UBS Securities projection: Average CPI inflation of 4.2% in FY25-26.
- Banking system liquidity remains in deficit (₹1.38 trillion as of March 12), delaying the full transmission of the rate cut.
| Economist (Institution) | Rate Cut Forecast | Outlook |
|---|---|---|
| Gaura Sen Gupta (IDFC Bank) | 25 bp in April, 25 bp in June | RBI to proceed cautiously, keeping external factors in view. |
| Madan Sabnavis (Bank of Baroda) | 25 bp in April, pause in June | RBI may reassess based on liquidity and monsoon impact. |
| Rahul Bajoria (Bank of America) | 100 bp total rate cut | RBI may adopt a more aggressive easing stance. |
| Tanvee Gupta Jain (UBS Securities) | 50 bp total rate cut, starting April | Policy support will strengthen domestic growth amid global uncertainties. |
RBI Imposes Penalties on JM Financial Products and Experian Credit Information
- Experian Credit Information Company of India Penalty Amount: ₹2 lakh Reason: Violation of provisions under the Credit Information Companies (Regulation) Act, 2005, and related rules.
- Reason: Violation of provisions under the Credit Information Companies (Regulation) Act, 2005, and related rules.
- JM Financial Products Limited Penalty Amount: ₹3.1 lakh Reason: Non-compliance with certain provisions related to Non-Banking Financial Companies (NBFCs).
- Penalty Amount: ₹3.1 lakh
ICRA: Securitised Asset Pools Under Pressure
- Upcoming Regulations: Stricter microfinance lending norms from April 2025 may limit disbursements, increasing stress on highly leveraged borrowers.
- Microfinance loans: Collection efficiency dropped from 97% at the beginning of FY25 to 90% in Q3 FY25.
- Secured SME Loans: Collection efficiency in the range of 91% to 104% in the first nine months of FY25.
- Microfinance Loans: Signs of improvement from December 2024, but further stress expected in Q1 FY26 due to stricter regulations.
Unpublished Price-Sensitive Information (UPSI)
- Statutory Penalties: Fines up to ₹25 crore or three times the illegal profit.
- Criminal Liability: Insider trading can lead to imprisonment (up to 10 years).
- SEBI issued a notification on March 11, 2025, amending Insider Trading Regulations.
- UPSI refers to non-public information that, if disclosed, could materially affect a company’s stock price. It is governed by the SEBI (Prohibition of Insider Trading) Regulations, 2015, preventing the misuse of confidential corporate data for unfair trading advantages.
Microfinance Sector Seeks Refinancing Body & IMEF Reforms
- IMEF Corpus Increase: Currently at ₹300 crore, industry demands an increase in corpus to support more MFIs.
- Higher Loan Limits: Maximum funding per MFI is ₹5 crore; proposal to raise this limit for better financial support.
- Sector Growth Trends Total Microfinance Assets: ₹4.14 trillion (Q3FY25). Annual Growth: 7.6% YoY increase. Quarterly Decline: 4.3% QoQ drop, indicating potential funding constraints.
- Total Microfinance Assets: ₹4.14 trillion (Q3FY25).
Way Forward
- Industry players are awaiting policy decisions from the Finance Ministry and RBI to enhance funding sustainability for MFIs.
MSME Industry Seeks E-commerce Export Reforms from RBI
- High Compliance Costs Shipping bill regularization fees range from ₹200 to ₹2,500 per shipment, disrupting cash flow. Small exporters face excessive banking fees, unpredictable logistics costs, and high warehousing expenses.
- Shipping bill regularization fees range from ₹200 to ₹2,500 per shipment, disrupting cash flow.
- Standardized fees for shipping bill regularization (e.g., ₹5,000 annual reconciliation fee for exporters under ₹5 crore turnover).
- Limit per-bill charges to ₹100 for transactions over $1,000.
NaBFID’s Credit Enhancement & Infrastructure Financing Plans
- Top 20 borrower accounts: Constitute 90.5% of the loan book (as of June 2024). 63.18% in AAA category, 23% in AA-AA+ segment.
- Constitute 90.5% of the loan book (as of June 2024).
- Current Loan Book: ₹ 60,000 crore (~$7.2 billion).
- Market Share: ~2% of India’s ₹ 30 trillion infrastructure finance market.
Digital Debt Collection in Microfinance
- Stressed assets (31-180 DPD) rose from 2.15% in March 2024 to 4.3% in September 2024 (RBI data).
- Collection efficiency for personal loans dropped from 95% (June 2023) to 93% (December 2023) (ICRA data).
- Increased Delinquencies Stress in microfinance sector doubled (April–September FY25). Stressed assets (31-180 DPD) rose from 2.15% in March 2024 to 4.3% in September 2024 (RBI data). Collection efficiency for personal loans dropped from 95% (June 2023) to 93% (December 2023) (ICRA data).
- Stress in microfinance sector doubled (April–September FY25).
Why Mutual Funds Are Outpacing Bank Deposits?
- The removal of 80C tax benefits for 5-year bank FDs has reduced their appeal, especially for tax-conscious investors.
- Slower Bank Deposit Growth Bank deposit growth slowed to 9.2%, while mutual funds grew 90%, indicating a liquidity shift from savings to investments. The slowdown in time deposits reflects a lower reliance on traditional saving instruments.
- Bank deposit growth slowed to 9.2%, while mutual funds grew 90%, indicating a liquidity shift from savings to investments.
- Mutual Fund AUM Outpacing Deposits: MF industry AUM rose 24% YoY, compared to an 8% growth in total bank deposits, showing a structural change in capital allocation.
RBI Assures Financial Stability of IndusInd Bank
- Liquidity Coverage Ratio (LCR) 113% (as for March 9, 2025), surpassing the regulatory requirement of 100%. The bank has already engaged an external audit team to review its systems and assess the actual impact of the discrepancy.
- The bank's share price fell after a discrepancy in its derivatives portfolio was discovered, with the disclosure expected to put 2.35% value at stake.
- The Central Bank insisted that the bank was under consideration by the RBI and insisted that remedial action must end in Q4FY25 with needed disclosures to all concerned stakeholders.
- 113% (as for March 9, 2025), surpassing the regulatory requirement of 100%.
Global Capability Centres (GCCs)
- Resilience post-pandemic – High attrition (up to 70% at service providers) prompted banks to in-source operations.
- JP Morgan alone has 21,000 engineers working on AI, cloud computing, blockchain, and digital banking.
- US Banks: First Citizens Bank, PNC Financial, Fifth Third Bank.
- 130 BFSI GCCs operating in India, employing 537,000+ people (EYWizmatic study).
RBI's Currency Management Modernization Project
- RBI received 11 Expressions of Interest (EoIs) and shortlisted six entities: Engineers India Limited (EIL) MECON Accenture Solutions Colliers International (India) Property Services PricewaterhouseCoopers The Boston Consulting Group (India)
- Engineers India Limited (EIL)
- Colliers International (India) Property Services
- PricewaterhouseCoopers
IndusInd Bank Leadership and RBI’s Role in CEO Appointments
- March 15, 2025: RBI assured the public that: IndusInd Bank remains well-capitalized and financially stable. The bank must complete corrective actions within the current quarter. Depositors should not panic over speculative reports.
- Estimated impact: ₹1,600 crore, or 2.35% of net worth (as of Dec 2024).
- Stock market impact March 11: IndusInd Bank stock fell 3.86%. March 12: Historic crash of 27.6%, wiping out ₹18,000 crore in market value.
- March 11: IndusInd Bank stock fell 3.86%.
Rupee Symbol Controversy
- The 2010 adoption of the ₹ symbol was a strategic decision aimed at: Global recognition: A distinct visual identity, similar to how Bitcoin (₿) uses a recognizable glyph. Cross-lingual familiarity: Designed from Devanagari 'र', but modified to resemble Latin 'R', appealing to English-speaking global markets. Psychological impact: The horizontal stroke enhances readability, making it instantly recognizable in financial transactions.
- Tamil Nadu’s decision to replace the rupee (₹) symbol with a Tamil script equivalent sparked Centre-state tensions.
- The controversy aligns with Tamil Nadu’s historical resistance to central linguistic policies.
- Global Brand Power: Much like the dollar ($) and euro (€), brand strength matters in financial markets. Replacing the symbol weakens international consistency, creating potential confusion in global trade.
Banks' Direct Integration with I4C
- Rising Financial Fraud Only 10% of stolen funds were blocked in three years till 2022. In 2022, out of ₹2,294.8 crore reported stolen, only ₹57 lakh was recovered.
- Only 10% of stolen funds were blocked in three years till 2022.
- In 2022, out of ₹2,294.8 crore reported stolen, only ₹57 lakh was recovered.
- Government Deadline Finance Ministry set January 31 as the deadline for integration. NPCI (National Payments Corporation of India) is already integrated for UPI transactions.
FIA vs. SEBI
- Introduce a more practical threshold: EOD (End-of-Day) Net Future Equivalent limit of ₹7,500 crore.
- EOD (End-of-Day) Net Future Equivalent limit of ₹7,500 crore.
- Objective Bring back alignment between the F&O markets and cash markets Reduce instances of ban of stocks Strengthen risk management
- FIA’s Concerns The Futures Industry Association (FIA) representing global derivatives players including clearing corporations and FPIs strongly opposes SEBI's proposals.
| Issue | FIA’s Concern |
|---|---|
| Liquidity Drain | Could lead to wider bid-ask spreads, reduce institutional participation, and undermine market depth. |
| Increased Trading Costs | Higher operational and compliance costs due to complex calculations and monitoring requirements. |
| Market Volatility | Restrictions may cause higher price swings and instability. |
| Price Manipulation Risks | Paradoxically, inefficiencies could increase the chance of price manipulation. |
| Operational Challenges | Delta-adjusted OI method is rare globally, adding significant complexity and error risk. |
| Position Limit Gaps | Potential loopholes, with large positions still possible in short-term out-of-the-money options. |
Futures and Options (F&O)
- 2. Speculators
- 3. Arbitrageurs
- Aim to reduce risk from price fluctuations.
- Traders use leverage, meaning they only deposit a small percentage (margin) to control larger positions.
| Aspect | Futures | Options |
|---|---|---|
| Obligation | Mandatory to buy/sell on the agreed date | Right (but not obligation) to buy/sell |
| Risk | Higher (both parties are liable to fulfill the contract) | Limited for buyer (only premium lost if not profitable) |
| Flexibility | Less flexible | More flexible (buyer can withdraw if unfavorable) |
Statutory Liquidity Ratio (SLR)
- The SLR is set and regulated by the RBI under Section 24(2A) of the Banking Regulation Act, 1949.
- SLR = % of deposits banks must hold in liquid assets.
- SLR is the minimum percentage of a commercial bank's net demand and time liabilities (NDTL) that it must maintain in the form of: Liquid cash Gold Approved government securities
| Aspect | SLR (Statutory Liquidity Ratio) | CRR (Cash Reserve Ratio) |
|---|---|---|
| Definition | Minimum percentage of deposits to be kept in liquid assets by the bank itself | Minimum percentage of deposits to be kept as cash with RBI |
| Form | Cash, gold, or approved government securities | Only cash |
| Held With | Maintained by the bank in its own vaults | Maintained with RBI |
| Interest | Banks earn interest on government securities kept as SLR | No interest is paid on CRR reserves |
| Flexibility | Used to manage liquidity and support government borrowing | More actively used for controlling liquidity and inflation |
RBI Governor Urges Banks and NBFCs to Strengthen Customer Grievance Redress
- Complaints under the RBI Integrated Ombudsman Scheme grew at nearly 50% annually over the past two years.
- RBI Ombudsman processed 294,000 complaints in FY24, up 25% from FY23.
- Nearly 57% of complaints required formal intervention or mediation, highlighting the inefficiency of current systems.
- Data on Complaint Surge Complaints under the RBI Integrated Ombudsman Scheme grew at nearly 50% annually over the past two years. 934,000 complaints were received in FY24. RBI Ombudsman processed 294,000 complaints in FY24, up 25% from FY23. Nearly 57% of complaints required formal intervention or mediation, highlighting the inefficiency of current systems. Scheduled commercial banks received over 10 million complaints in FY24.
RBI Revises State Bond Auction Amount
- Revised Auction Size The Reserve Bank of India revised the scheduled state bond auction amount for to ₹52,120 crore, up from the previously planned ₹40,120 crore.
- The Reserve Bank of India revised the scheduled state bond auction amount for to ₹52,120 crore, up from the previously planned ₹40,120 crore.
- Previous Auction Recap In the previous auction, 20 states raised a total of ₹49,522 crore through debt sales.
- In the previous auction, 20 states raised a total of ₹49,522 crore through debt sales.
India’s Retail Options Trading Plunge
- 30-day rolling average of options contracts by individual investors down 77% since November 2023.
- Derivatives traders at a 17-month low in January 2024.
- Regulations included Limiting weekly options, Increasing lot sizes (making it costlier to trade), Other phased restrictions to protect investors.
- Other phased restrictions to protect investors.
Paytm Money Receives SEBI Research Analyst Certification
- Anti-money laundering violations: In 2021, RBI detected violations of anti-money laundering violations and the bank was warned about it but continued to persist.
- Dormant accounts: Out of 35 crore e-wallets, 31 crore were dormant accounts and only 4 crore remaining had some to no activity. This high number of dormant accounts can mean an increase in the mule accounts.
- Audit: RBI instructed PPBL to onboard new clients in 2022 and appoint an external firm to do a comprehensive audit of the system. Many accounts were ceased by various digital agencies across the countries as they were used in committing digital frauds.
- This certification allows Paytm Money to Provide research reports Offer investment analyses to both retail and institutional investors
SBI Shelves Bond Issuance Plans for Current Fiscal
- State Bank of India (SBI) has decided to defer its plan to raise ₹15,000 crore through bond issuance in the current fiscal year (ending March).
- Originally intended to raise ₹5,000 crore via Basel III-compliant additional Tier-I perpetual bonds ₹10,000 crore via 15-year infrastructure bonds
- ₹5,000 crore via Basel III-compliant additional Tier-I perpetual bonds
- ₹10,000 crore via 15-year infrastructure bonds
RBI Governor Advocates AI Use
- 95 commercial banks in India received over 10 million customer complaints in FY 2023-2024.
- Customer Interaction Tools Implement AI-driven chatbots and voice recognition to overcome language barriers in India’s linguistically diverse population.
- Implement AI-driven chatbots and voice recognition to overcome language barriers in India’s linguistically diverse population.
Mutual Funds Mix Debt
- The restructured funds will Invest slightly less than 65% of their corpus in fixed income instruments. Invest the balance in arbitrage (simultaneous buy and sell of shares and futures to exploit price differentials).
- Invest slightly less than 65% of their corpus in fixed income instruments.
- Gains from these schemes, if held for more than 24 months, will be taxed as long-term capital gains (LTCG) at 12.5%.
- In contrast, plain debt schemes are taxed at individual tax slabs (up to 30% for high-income individuals and corporates).
| Existing Fund Name | New Name |
|---|---|
| Kotak All Weather Debt FoF | Kotak Income Plus Arbitrage FoF |
| Bandhan All Seasons Bond Fund | Bandhan Income Plus Arbitrage Fund of Fund |
| Axis All Seasons Debt Fund of Funds | Axis Income Advantage Fund of Funds |
| ABSL Active Debt Multi Manager FoF | ABSL Debt Plus Arbitrage FoF |
Short-Term Borrowings Likely to Get Cheaper for Indian Banks
- ₹4.1 lakh crore infused through Open Market Operations (OMO).
- ₹1 lakh crore more planned through two OMO auctions in March.
- The aggregate liquidity infusion via swaps could total around ₹2.15 lakh crore by the next quarter.
- The Weighted Average Call Rate (WACR) spiked to 6.81% in January, but fell to 6.21% by March 12.
Option Trading
- Buyers gain the right to exercise the option anytime before the expiration (American style) or on the expiration date (European style).
- Sellers (writers) are obligated to fulfill the contract if the buyer chooses to exercise.
- Options are derivatives, meaning their value is derived from the price of an underlying asset (stock, index, ETF, etc.).
| Type | Meaning |
|---|---|
| Call Option | Right to buy the asset at a set price before expiry (if profitable). |
| Put Option | Right to sell the asset at a set price before expiry (if profitable). |
S&P upgrades ratings for Shriram Finance, Muthoot & Sammaan Capital
- Established in October 2022.
- Minimum 9% Common equity Tier 1 capital to risk weighted assets as per capital adequacy norms.
- The Standard and Poor's 500, or simply the S&P 500, is a stock market index tracking the stock performance of 500 of the largest companies listed on stock exchanges in the United States.
Moody's Review of IndusInd Bank's Ratings
- Even amidst the accounting controversy, IndusInd Bank raised Rs 110 billion ($1.27 billion) through short term notes (Certificates of Deposit).
- Moody’s affirms the following ratings with a stable outlook Long term and short term foreign currency bank deposits: Ba1/NP Local currency bank deposits and issuer ratings: Ba1/NP Counterparty risk ratings: Ba1/NP
- Long term and short term foreign currency bank deposits: Ba1/NP
- Local currency bank deposits and issuer ratings: Ba1/NP
Paytm Money Receives Certification to Work as a Research Analyst by SEBI
- It endeavors to enrich the user experience with insights based on expert opinions for retail and institutional investors alike.
Income Tax Bill 2025 Expands AMT Scope
- The Bill omits a provision from the IT Act, 1961, which limited AMT applicability to those claiming Chapter VIA deductions (such as donations, infrastructure profits, employment generation incentives).
- Currently, LTCG (Long-Term Capital Gains) is taxed at a preferential rate of 12.5% under AMT calculation.
- The new Bill proposes removal of this special treatment, potentially raising the effective tax rate to 18.5%, increasing tax liability.
- Section 206 states: AMT applies if tax payable by an LLP on adjusted income is less than 18.5%, with no specific carve-outs.
| Aspect | Current Law (IT Act, 1961) | Proposed (IT Bill, 2025) |
|---|---|---|
| LTCG tax rate under AMT | 12.5% preferential rate | Special treatment removed; likely taxed at 18.5% |
| Applicability limited to | Entities claiming Chapter VIA deductions | No limitation; likely applies to all LLPs and partnership firms |
| Relevant section | Separate provisions, with carve-outs (like Section 115JEE) | Consolidated under Section 206, without clear carve-outs |
The National Asset Reconstruction Company Limited (NARCL)
- Earlier, Yes Bank had assigned its loan to JC Flowers ARC, now holding a 24.39% share of McLeod’s debt.
- IndusInd Bank holds 4.90% shares.
- Debt assignment/expression of interest was invited by lenders in December 2024 for selling/assigning debts aggregating to ₹1,104.69 crore, with a reserve price of ₹700 crore.
- The results of an Assignment Agreement executed on March 12, 2025, signify that ICICI Bank as lead bank and seven other banks (SBI, HDFC Bank, Axis Bank, PNB, UCO Bank, Indian Bank, RBL Bank) have assigned their loan accounts to NARCL.
Augmented Banking Services
- Urbanization More than 70% of complaints for about FY24 are coming from urban and metro centers, leading to the conclusion that the rural and semi urban customers are still underserved.
- More than 70% of complaints for about FY24 are coming from urban and metro centers, leading to the conclusion that the rural and semi urban customers are still underserved.
- Leadership Vacancies Some 40% of the director level positions at the PSBs have remained unfilled, according to details given by the government in Parliament. It threatens governance, strategic decisions, and customer centric operations.
- Some 40% of the director level positions at the PSBs have remained unfilled, according to details given by the government in Parliament.
SEBI May Reconsider Gross Limit Proposal for Index Options
- Aim: To restrict large manipulative positions mainly in individual stocks and index derivatives.
- Brokers, proprietary desks, and institutional traders are fearing that the market will become less liquid and wider bid/ask spreads would greatly inflate the cost and inefficiency of trading.
- Instead of having different limits on many parameters, it sees gross limit setting as a simplified risk management device.
- Delta measures how much an option's price changes with a change in the underlying index/stock.
SEBI’s Settlement Mechanism Faces Criticism
- Settlement amounts collected in FY25 (till 15 March): ₹851 crore.
- Comparatively higher than ₹125 crore in FY23 and ₹94 crore in FY24.
- Excluding the ₹643-crore NSE case, collections are still significantly higher.
- Enforcement orders coming for settlement increased from 10% to 45% in the past five years.
SEBI’s Proposal of a Gross Limit for Index Options
- Impact on Large Traders A broking firm official noted that large funds could not hedge their portfolios effectively under the gross limit rule. Reportedly, most brokers opposed a gross limit of ₹1,500 crore at the end of the day.
- Reportedly, most brokers opposed a gross limit of ₹1,500 crore at the end of the day.
- Concerns of the Brokers Dryness of the limit would reduce liquidity in the market. Costliness to trade as the bid ask spread is likely to widen.
- Loss of liquidity is what brokers expect, leading to costs that clients suffer from.
Canara Bank Launches Digital Balance Confirmation Certificate
- Auditors were required to: Approach each bank individually. Provide authority letters to request Balance Confirmation Certificates. Wait for manual verification and processing — a time-consuming and tedious task.
- Provide authority letters to request Balance Confirmation Certificates.
- ObjectiveTo eliminate manual processes and improve efficiency in obtaining Balance Confirmation Certificates.
- Auditors will now receive direct confirmations via the online portal.
Government Announces ₹1,500 crore UPI Incentive Scheme for FY 2024-25
- To achieve a target of ₹20,000 crore through UPI transaction volumes in the coming FYs 2024 25.
- During FY 2023 24, the government has spent ₹3,631 crore in incentive disbursement to banks, which is more than the last two years combined.
- Incentive rate 0.15%for each qualified transaction to the banks.
- 0.15%for each qualified transaction to the banks.
RBI Bulletin: State of the Economy
- A full-blown tariff war could: Raise US inflation by 1.0–1.2%. Lower US GDP growth by 0.6 percentage points in 2025. Result in the US economy being 0.3–0.4% smaller in the long run.
- The headline inflation rate dropped to a 7-month low of 3.6% in February 2025 (down from 4.3% in January) due to falling food prices.
- In February 2025, the RBI reduced the policy repo rate by 25 basis points, the first cut in nearly five years.
- CD issuances in the primary market have grown by 34% year-on-year, reaching an all-time high of ₹10.58 trillion (up to March 7, 2025).
SEBI Consultation Paper on Open Interest (OI)
- SEBI proposes an increase in the end of day (EoD) limit for entities to be ₹1,500 crore instead of ₹500 crore. FIA states that if delta methodology is adopted, the EoD limit should be ₹7,500 crore to accommodate such fluctuating risk thresholds.
- Adversely Impacts Frequent Trading Strategies Strategies such as index arbitrage or long options positions would be subjected to penalties under delta threshold but would incur no coverage increase in risk.
- Since February 24, 2025, the SEBI consultation paper has affected OI calculations, limits on positions, and new trading sessions before and after continued derivatives trading. The delta calculation has been staunchly opposed by the Futures Industry Association, or FIA, a global body representing foreign portfolio investors.
- Delta Based Position Limits: Delta (ranging from 1 to +1) would become the benchmark for position limits, representing option price sensitivity relative to underlying asset movements.
SEBI’s $7 Billion Mutual Fund Limit
- Minimum Investment: $75,000 (approximately ₹66 lakh).
- LRS Limit: Up to $250,000 can be remitted in a financial year.
- Geographic Split: 75% in the United States 20% in Europe 5% in Canada
- 75% in the United States
SEBI to Strengthen and Standardise Internal Audit Mechanism at Market Infrastructure Institutions (MIIs)
- Internal auditors’ observations must be: Sent to heads of departments (HODs) for their comments. Shared with the audit committee.
- Only key managerial personnel (KMPs) can attend audit committee meetings with prior approval from the committee chairman.
- Managing Directors (MDs) may potentially be barred from being part of audit committees.
- Aim: Ensure independence and objectivity in the audit process.
RBI’s State of the Economy Report
- Headline inflation has dropped significantly from above 6% in October 2023 to 3.6% in February 2024.
- The RBI reduced the policy rate by 25 basis points to 6.26% in February 2024.
- Outward remittances under the Liberalised Remittance Scheme (LRS) rose to $2.8 billion in January from $2.3 billion in December.
- Since October, foreign portfolio investors (FPIs) have withdrawn $29 billion from Indian stocks, marking the largest six-month outflow.
SEBI Partners with DigiLocker to Reduce Unclaimed Financial Assets
- SEBI’s circular states that: Investors using DigiLocker can automatically fetch their CAS on January 1st each year. This feature aims to ensure investors regularly review and track their financial assets, reducing the likelihood of assets becoming unclaimed.
- Investors using DigiLocker can automatically fetch their CAS on January 1st each year.
- Investors can now store and access key financial documents such as: Demat account holdings Mutual fund statements Consolidated Account Statements (CAS)directly through DigiLocker.
- Unclaimed financial assets are funds or financial instruments that remain inactive, dormant, or unclaimed by their rightful owners for a legally defined period, such as bank deposits, shares, insurance policies, or dividends.
RBI Governor Calls Out Banks for Poor Customer Service
- Complaints under RBI’s ombudsman scheme have been growing at a 50% CAGR over the past two years, highlighting a systemic issue.
- RBI Governor Sanjay Malhotra sharply criticized Indian banks for their poor customer service and complaint management. Banks in India held ₹103 lakh crore ($1.2 trillion) in fixed deposits in 2023, but small customers continue to face negligence.
- Banks received over 1 crore complaints in FY24.
- Banks disbursed up to 60% of housing loans despite knowing that construction had not even begun, indicating possible misconduct.
SEBI May Raise FPI Disclosure Threshold to ₹50,000 Crore
- FPI debt market inflows reached a 1-year high with ₹3,052 crore invested in a single day, according to NSDL data.
- Domestic equity benchmarks surged for the fourth straight day, supported by positive investor sentiment following the US Federal Reserve’s projection of two rate cuts in 2025.
- SEBI may also ease regulations for: Research analysts and investment advisors regarding advance fee collections. Alternative Investment Funds (AIFs), aiming to make the ecosystem more attractive.
- Research analysts and investment advisors regarding advance fee collections.
Payment Banks in India
- The last revision in deposit limits happened in April 2021, when it was raised from ₹1 lakh to ₹2 lakh.
- Out of the 11 payments bank licences granted in 2015, only six remain active: Airtel Payments Bank, Paytm Payments Bank, India Post Payments Bank, Fino Payments Bank, NSDL Payments Bank, and Jio Payments Bank.
- As per RBI norms, payments banks can apply for conversion after five years of operations and meeting capital requirements, including a minimum paid-up equity capital of ₹200 crore.
- IPPB currently operates 650 branches and over 163,000 access points across India and offers a range of financial services, including savings accounts, virtual debit cards, bill payments, and insurance.
UPI Incentive Cuts Raise Concerns in Fintech Sector
- RBI Data Insights UPI’s contribution to India’s digital payments ecosystem has surged from 34% in 2019 to 83% in 2024, highlighting its dominance.
- UPI’s contribution to India’s digital payments ecosystem has surged from 34% in 2019 to 83% in 2024, highlighting its dominance.
- Government Incentive Reduction Allocation for promoting low-value BHIM-UPI transactions cut to ₹1,500 crore for FY25. Down from ₹3,268 crore allocated in FY24.
- Allocation for promoting low-value BHIM-UPI transactions cut to ₹1,500 crore for FY25.
IndusInd Bank Raises ₹14,750 Crore via CDs, PSBs Lead Contribution
- IndusInd Bank raised a total of ₹14,750 crore through certificates of deposit (CDs) this week to address cash shortages caused by tight system liquidity.
- On Thursday alone, the bank raised ₹1,000 crore via CDs at a rate of 7.9%.
- Punjab National Bank (PNB) also raised ₹4,950 crore through various maturities at yields between 7.56% and 7.57%.
- Rising CD Rates Amid Liquidity Tightness Smaller banks are facing even higher borrowing costs, with CSB Bank raising ₹100 crore through one-year CDs at 8.5%, and Utkarsh Small Finance Bank issuing three-month CDs at 8.05%.
| Bank | Amount Raised (₹ crore) | Maturity | Yield (%) |
|---|---|---|---|
| Punjab National Bank (PNB) | 4,950 | 3 & 12 months | 7.56 – 7.57 |
| IndusInd Bank | 1,000 | 6 months | 7.90 |
| Jammu & Kashmir Bank | 275 | 3 months | 7.75 |
| CSB Bank | 100 | 12 months | 8.50 |
| Utkarsh Small Finance Bank | 50 | 3 months | 8.05 |
SEBI Board Meeting Agenda Under New Chairperson Tuhin Kanta Pandey
- Current rules (August 2023): FPIs with Assets Under Custody (AUC) over ₹25,000 crore or with 50%+ exposure to a single corporate group must provide detailed ownership disclosures.
- Introduced in April 2020 to regulate FDI from countries sharing land borders with India, including China.
- FPIs have withdrawn over ₹2 trillion from Indian equities in the past six months.
- SEBI aims to make small-ticket SIPs (as low as ₹250) more cost-effective for asset management companies.
IndusInd Bank Crisis Raises Concerns Over Governance and Regulatory Transparency
- The bank disclosed derivatives accounting discrepancies amounting to 2.35% of its net worth.
- The bank’s stock plummeted by over 25% in a single trading day.
- Required provisioning of around ₹1,600 crore due to these issues.
- The issue was identified following an RBI circular in September 2023, mandating the discontinuation of such internal trades from April 1, 2024.
SEBI Considers ESOP Relaxation for Startup Founders
- Under current Companies (Share Capital and Debentures) Rules, 2014, ESOPs (Employee Stock Ownership Plans) are only issued to employees and prohibited for promoters. Many startup founders, initially employees, later become classified as promoters as their shareholding increases or after company reclassification. This ambiguity has led to confusion about whether they can retain or exercise ESOPs granted before they became promoters.
- SEBI is considering allowing startup founders, identified as promoters or part of the promoter group, to hold or exercise ESOP benefits granted one year before the IPO.
- The move aims to align incentives, especially for founders with diluted stakes who continue contributing to company growth.
- Founders of new-age technology firms often receive ESOPs or equity-linked instruments instead of large cash compensation to align their interests with long-term company success.
| Aspect | Current Regulation | Proposed Change |
|---|---|---|
| ESOP eligibility for promoters | Prohibited for promoters or promoter groups | Allow founders to hold/exercise ESOPs granted 1 year prior to IPO |
| Ambiguity for founders | Founders reclassified as promoters lose clarity on ESOPs | Proposed change aims to provide clarity and policy certainty |
| Cooling-off period | Not specified | Cooling-off period between ESOP grant and IPO to prevent misuse |
SEBI Proposes Key Changes to EBP and RFQ Platforms
- Faster settlement cycles (T+1) and quicker listing timelines (T+2) will increase efficiency.
| Key Proposal | Current Norms | Proposed Change |
|---|---|---|
| EBP threshold for private placements | Mandatory for issue sizes over ₹50 crore | Lowered to ₹20 crore |
| EBP for InvITs and REITs | No specific requirement | Mandatory for private placements above ₹1,000 crore |
| Greenshoe portion | Up to 5 times the base issue size | Reduced to 3 times the base issue size |
| Settlement cycle | T+2 cycle | Move to T+1 cycle |
| Listing time | T+3 days | Reduced to T+2 days |
| Bidding process for large issues | Not mandatory | Mandatory open bidding for issues over ₹1,000 crore |
Finfluencers Under Scrutiny
- Only 2% of finfluencers are registered with the Securities and Exchange Board of India (SEBI).
- 33% of finfluencers provide explicit stock recommendations, despite lacking regulatory approval.
- 63% fail to disclose sponsorships or financial affiliations, creating potential conflicts of interest.
- Lack of Regulation & Accountability:Finfluencers operate in a largely unregulated environment, which increases the risk of misinformation and misguided investment decisions.
| Data Point | Key Insight |
|---|---|
| 8% of investors duped | Older investors (40+ years) are more susceptible to misleading advice. |
| Investors aged 26–30 | Prioritize the number of followers over credibility or regulatory status. |
| 50%+ of cautious investors unaware | Despite valuing SEBI registration, many investors are unaware of finfluencer registration status. |
IDFC FIRST Bank Launches ‘Ace’ Feature on Mobile App
- It offers access to detailed information on over 2,500 mutual funds across various categories.
- IDFC FIRST Bank has introduced the ‘Ace’ feature on its mobile banking app.
- Customers can browse funds by category: Equity, Debt, Tax-Saving, Hybrid, and Index funds.
- The feature is designed to promote DIY (do-it-yourself) investing among customers.
SEBI Proposes Key Reforms on ESOPs and Lock-In Norms for IPO-Bound Promoters
- Founders forced to classify themselves as promoters (holding ≥10% stake) were at risk of losing ESOP benefits under existing norms.
- Stock Appreciation Rights (SARs)
- Condition: These ESOPs or SARs must have been granted at least one year before the initial public offering (IPO).
- Current rules disallow promoters and promoter group members from receiving ESOPs.
SEBI Eases Norms on AMC Executives’ Mandatory Investments
- Exemption for Lower-Income Employees Employees earning less than ₹25 lakh annually are now exempt from mandatory investments.
- Employees earning less than ₹25 lakh annually are now exempt from mandatory investments.
- Effective Date: April 1, 2025.
- The flexibility shows a balancing act between aligning fund managers’ interests and ensuring practical compliance.
IndusInd Bank Derivative Discrepancies
- On March 10, 2025, IndusInd Bank disclosed discrepancies in its derivative portfolio, which are expected to have over 2% impact on its net worth. The bank appointed PwC to conduct a review; the report is still awaited.
- Since the March 10 disclosure, IndusInd Bank’s stock has fallen by over 24%.
- On March 21, 2025, shares closed at ₹ 685.75 on the BSE.
- The bank has aggressively borrowed around ₹ 15,000 crore in the certificate of deposits (CD) market at elevated rates, tapping state-owned banks and mutual funds for liquidity support.
| Metric | Value | Definition |
|---|---|---|
| Capital Adequacy Ratio (CAR) | 16.46% | The Capital Adequacy Ratio (CAR) is a financial metric that measures a bank's ability to absorb losses and maintain stability by ensuring it has enough capital relative to its risk-weighted assets, also known as Capital to Risk (Weighted) Assets Ratio (CRAR). |
| Provision Coverage Ratio (PCR) | 70.20% (as of Dec 31, 2024) | The Provision Coverage Ratio (PCR) measures how well a bank is prepared to cover potential losses from bad loans or Non-Performing Assets (NPAs) by calculating the percentage of provisions made against the total value of gross NPAs. |
| Liquidity Coverage Ratio (LCR) | 113% (vs. 100% requirement) | The Liquidity Coverage Ratio (LCR) is a financial metric that requires banks to hold enough high-quality liquid assets (HQLA) to cover potential net cash outflows during a 30-day stress scenario, ensuring they can meet short-term obligations. |
Bank Credit and Deposit Growth Gap Widens
- Credit growth Bank credit in India grew 11.1% year-on-year (YoY) in the fortnight ended March 7, 2025. Absolute credit growth was ₹1.38 trillion over the previous fortnight. Outstanding credit reached ₹225.10 trillion.
- Bank credit in India grew 11.1% year-on-year (YoY) in the fortnight ended March 7, 2025.
- Absolute credit growth was ₹1.38 trillion over the previous fortnight.
- Outstanding credit reached ₹225.10 trillion.
Sebi Eases 'Skin-in-the-Game' Norms for AMC Employees
- Replaces the 2021 rule that mandated 20% of senior executives’ salaries in mutual fund units.
- Slab 0 (CTC < ₹25 lakh): No mandatory investment.
- Slab 1 (CTC ₹25–50 lakh): Must invest 10% of gross CTC or 12.5% (excluding ESOPs) in schemes they oversee.
- Must invest 10% of gross CTC or 12.5% (excluding ESOPs) in schemes they oversee.
Sebi's Crackdown on Misinformation and Finfluencers
- As of February 2025: FPI holdings: ₹62 trillion in equity and ₹5.9 trillion in debt.
- Aim to use the accredited investor model to focus on risk-aware and capable investors.
- FPI holdings: ₹62 trillion in equity and ₹5.9 trillion in debt.
- Since October 2024, over 70,000 misleading online posts and accounts have been removed.
Sebi’s Directive on Social Media Advertisements
- Investment advisers
- Stock brokers
- All intermediaries must register with SMPPs using: Email IDs Mobile numbers(These should match the details available on the Sebi intermediary portal.)
- Mobile numbers(These should match the details available on the Sebi intermediary portal.)
Sebi Extends Deadline for Related Party Transaction Compliance
- The compliance deadline has been moved to 1 July 2025 (previously set for 1 April 2025).
- Listed entities must provide minimum specified information for review by: The Audit Committee Shareholders when seeking approval for related party transactions.
- Shareholders when seeking approval for related party transactions.
- The new disclosure framework is aimed at: Enhancing transparency in RPTs. Standardizing the quality and completeness of information presented to oversight bodies and shareholders.
SEBI Proposes to Allow Stock Brokers to Operate in GIFT-IFSC Without Prior Approval
- Since October 2023, SEBI has taken down over 70,000 misleading social media posts and accounts with help from social media platforms.
- Investors availing services from SBUs will not have access to SEBI’s SCORES platform, nor the grievance redressal mechanisms or investor protection funds of Indian stock exchanges.
- Brokers who previously set up subsidiaries or joint ventures for securities market activities in GIFT-IFSC may now dismantle these structures and conduct activities directly under an SBU.
- SEBI’s whole-time member, Ananth Narayan, highlighted the growing threat of unregistered investment advisers and fraudulent research analysts.
Bank of Baroda Launches 'mDigiNext' Mobile App
- 24x7 access to cash management tools for corporates.
- Enhanced security: OTP verification. Three-factor authentication (3FA) for secure operations.
- Three-factor authentication (3FA) for secure operations.
- Currently launched on Android; iOS version to follow soon.
AdvaRisk launches AI-Powered Collateral Management for Banks, NBFCs
- As per government data, gross NPAs of public sector banks stood at ₹3.16 lakh crore (3% of outstanding loans) as of September 2024.
- Automated red-flagging and legal audits, significantly reducing procedural errors and human negligence.
- Real-time account monitoring, aligned with RBI mandates for lenders.
- Integration of AI and machine learning to: Flag discrepancies early in the loan process. Mitigate cybersecurity and procedural risks. Support compliance with new RBI directives.
Why Banking IPOs in India Have Been a Poor Investment
- IndusInd Bank has become the latest example, plunging over 30% in recent weeks, hitting price levels last seen in 2014 (excluding the COVID dip).
- In 2015, these accounted for 82.5% of Nifty Bank’s market cap; now 86.5%.
- Globally too, scale matters. During the 2023 U.S. banking crisis, small banks like Silicon Valley Bank collapsed, while JP Morgan Chase and Bank of America thrived.
- Over the last decade: Nifty Bank Index: 10% CAGR IndusInd Bank: Negative 3% CAGR
Terrorism Risk Insurance Premiums Set to Fall in India
- After international reinsurers withdrew terrorism risk capacity following the 9/11 attacks in 2001, India established a terrorism risk insurance pool on April 1, 2002, administered by GIC Re.
- Initial indemnity limit: ₹200 crore per location.
- Current limit: Increased to ₹2,000 crore per location.
- Premium income: ₹1,654.63 crore (down from ₹1,809.01 crore in FY23).
IndusInd Bank Appoints Grant Thornton for Forensic Audit
- On March 10, IndusInd disclosed that its derivatives portfolio was overvalued by 2.35% (approximately $175 million), due to noncompliant internal trades.
- Since the March 10 disclosure, IndusInd’s shares have declined by 23.4%.
- Reuters reported that the RBI has advised IndusInd Bank’s CEO and deputy CEO to step down after replacements are found.
- This discrepancy violated Reserve Bank of India (RBI) guidelines.
How Insurtech Is Transforming the Insurance Industry
- Consumers now expect faster, personalised services.
- IoT is helping insurers underwrite risk with real-time data insights.
- Machine learning algorithms analyse large datasets, allowing insurers to assess risks and create customised products for diverse customer segments.
- IoT devices collect real-time data, helping insurers monitor risk continuously.
The Rise of NBFCs
- Financial Health (as of September 2024): Capital adequacy: 26.1% Net interest margins: 5.1% Return on assets: 2.9% Gross NPAs: 3.4%
- Capital Backing: Nearly ₹6,000 crore in equity was invested at the outset despite challenging times marked by IL&FS and DHFL collapses. Multiples PE and Bain Capital among key investors supporting this evolution.
- Nearly ₹6,000 crore in equity was invested at the outset despite challenging times marked by IL&FS and DHFL collapses.
- Capital adequacy: 26.1%
Why Bond Yields Diverge Despite RBI Rate Cuts
- Recent data: FIIs pulled out ₹34,574 crore in February 2025, totaling ₹1.12 trillion outflows in the first two months of 2025. Since October 2024, the cumulative outflow is ₹2.12 trillion.
- FIIs pulled out ₹34,574 crore in February 2025, totaling ₹1.12 trillion outflows in the first two months of 2025.
- Since October 2024, the cumulative outflow is ₹2.12 trillion.
- Rupee Depreciation Factor: Between October 2024 and February 2025, the rupee depreciated by over 4%, moving from ₹83.81 to ₹87.50 per dollar. This deters foreign investments as US bonds offer 4.5% risk-free returns with lower currency risk.
Paytm Faces Setback as Government Cuts UPI Incentives for FY25
- Following RBI’s action against Paytm Payments Bank in January 2024 and the government's reduced allocation, Paytm’s UPI income could fall by around ₹150 crore for FY25.
- In FY24, Paytm earned ₹288 crore under the scheme, accounted for in Q4FY24.
- In FY24, total incentives for the UPI industry were ₹3,268 crore, nearly 80% higher than the previous year.
- For perspective, Paytm reported an adjusted EBITDA loss of ₹772 crore (before ESOP) in 9MFY25.
Banks Block Indian Promoters’ Foreign NBFC Plans
- Larger capital outflows: ODI allows remittance up to four times a company’s net worth, significantly more than the $250,000 cap under the Liberalized Remittance Scheme (LRS) for individuals. Banks fear ODI may become a route for promoters to bypass LRS limits.
- ODI allows remittance up to four times a company’s net worth, significantly more than the $250,000 cap under the Liberalized Remittance Scheme (LRS) for individuals.
- Definition ODI involves investing in foreign entities, including acquiring unlisted equity capital, subscribing to a foreign entity's memorandum of association, or investing 10% or more of the paid-up equity capital of a listed foreign entity.
- ODI involves investing in foreign entities, including acquiring unlisted equity capital, subscribing to a foreign entity's memorandum of association, or investing 10% or more of the paid-up equity capital of a listed foreign entity.
Banks Remain Cautious on Foreign Currency Deposits
- Rate adjustments have been minimal: Banks such as Indian Overseas Bank have kept FCNR-B deposit rates unchanged since October 2024. CSB Bank MD, Pralay Mondal, stated that current inflows sufficiently meet their foreign currency loan requirements.
- Banks such as Indian Overseas Bank have kept FCNR-B deposit rates unchanged since October 2024.
- “Softening interest rates in global markets have made it easier for domestic banks to raise US dollar funds,” said Ajay Kumar Srivastava, MD, Indian Overseas Bank.
- Karur Vysya Bank MD, B Ramesh Babu, noted that the bank prefers alternative, cost-effective funding sources.
P2P Lending Slows
- In June 2024, the RBI introduced tighter guidelines prohibiting Fixed return guarantees Credit enhancement facilities Non-compliance led to penalties, In August 2024, RBI fined Liquiloans and LenDen Club ₹1.9 crore each.
- Non-compliance led to penalties, In August 2024, RBI fined Liquiloans and LenDen Club ₹1.9 crore each.
- According to RBI’s response to a December 2024 RTI filed by Capitalmind: Bad loans in the P2P sector stand at ₹1,163 crore. While RBI had no official AUM data, industry estimates pegged it around ₹6,500 crore at that time.
- The sector’s assets under management (AUM) have dropped sharply from around ₹10,000 crore to less than ₹3,000 crore in the past year.
A Cautious Optimism
- February’s Consumer Price Index (CPI) rose by 3.6% YoY, below the RBI’s 4% target.
- Food inflation was modest at 3.75%, signaling relief from previous highs.
- Although markets appear to be ignoring these risks (Sensex up 5.4% from recent lows), these threats could destabilize trade flows.
- This ends a six-month decline (Oct 2024–Feb 2025) when FPIs sold $22.7 billion in Indian equity and debt markets.
SEBI Board to Discuss Conflict-of-Interest Disclosure Framework
- The proposed framework is likely to mandate that SEBI board members and their spouses: Disclose all assets to SEBI Report any potential conflicts of interest proactively
- The Securities and Exchange Board of India (SEBI) is set to hold its first board meeting under new chairman Tuhin Kanta Pandey on March 24. Key topics on the agenda:
- Introduction of a conflict-of-interest disclosure framework for board members
- Proposal on the appointment process for key management personnel at market infrastructure institutions (MIIs), such as stock exchanges
Transparency, FPI Threshold, and Governance Reforms
- Foreign Portfolio Investors (FPIs): Disclosure threshold doubled from ₹25,000 crore to ₹50,000 crore to reduce compliance burden and align with market growth.
- Disclosure threshold doubled from ₹25,000 crore to ₹50,000 crore to reduce compliance burden and align with market growth.
- Purpose: Review conflict of interest provisions. Strengthen disclosure norms and other governance matters for top SEBI officials.
- Strengthen disclosure norms and other governance matters for top SEBI officials.
SEBI to set up High-Level Committee on Conflict of Interest
- The threshold for granular ownership disclosures by Foreign Portfolio Investors (FPIs) has been doubled from ₹25,000 crore to ₹50,000 crore.
- The concentration limit of 50% of AUC in a single corporate group remains unchanged.
- The conflict-of-interest framework, last updated in 2008, will be revisited to enhance operational disclosures, including self-recusal mechanisms.
- Investment Advisors (IAs) and Research Analysts (RAs) are now allowed to charge advance fees for up to one year, subject to client agreement.
IMF’s FSSA Report Highlights
- India’s financial system has become more resilient and diverse since the last FSAP in 2017.
- Over 548.4 million bank accounts have been opened under the Jan Dhan Yojana, with total balances exceeding ₹2.45 trillion.
- India’s Financial Inclusion Index has risen from 43.4 in 2017 to 64.2 in March 2024.
- Indian banks need to adopt International Financial Reporting Standards (IFRS 9) for robust credit risk management.
RBI Revises Priority Sector Lending Norm
- Overall PSL target revised to 60% of Adjusted Net Bank Credit (ANBC) or Credit Equivalent of Off-Balance Sheet Exposure (CEOBSE), whichever is higher
- Population > 5 million: Loan up to ₹50 lakh Maximum dwelling unit cost: ₹63 lakh
- Loan up to ₹50 lakh
- Maximum dwelling unit cost: ₹63 lakh
Record Dividend Payouts by Central Public Sector Enterprises (CPSEs) in FY25
- SBI contributed over 40% of public sector bank profits in FY24.
- The bank reported profits of ₹ 61,077 crore, 22% higher than the previous fiscal (₹ 50,232 crore).
- Dividends paid by Central Public Sector Enterprises (CPSEs) in FY25 have reached a record ₹ 69,873 crore so far.
- The government is optimistic that this figure will touch ₹ 70,000 crore by the end of the financial year.
India’s Derivatives Market
- Average premium per index option increased from ₹1,300 (Nov 2024) to ₹3,000 (Feb 2025).
- Cash market volumes dropped by 12% (Feb vs. Nov 2024), aligning with derivatives moderation.
- In March 2025, derivative volumes rebounded by 20% month-on-month with improving market sentiment.
- Concerns: Overheated market activity and 90% loss rate among retail investors (SEBI study).
RBI Revises Priority Sector Lending (PSL) Guidelines for 2025
- The overall PSL target for Urban Cooperative Banks (UCBs) has been revised to 60% of either: Adjusted Net Bank Credit (ANBC), or Credit Equivalent of Off-Balance Sheet Exposures (CEOBSE),whichever is higher.
- These revised guidelines will come into effect from 1 April 2025.
- The Reserve Bank of India (RBI) has issued revised guidelines on priority sector lending (PSL), aimed at facilitating better targeting of bank credit to priority sectors of the economy.
- Several loan limit enhancements have been introduced to ensure greater PSL coverage, especially in sectors like housing and renewable energy.
Brokers Seek RBI Clarity on Retail G-Sec Trading Framework
- The RBI has been making efforts to promote retail participation by: Launching a mobile app for G-Sec investment. Reducing the minimum investment amount to ₹10,000 last year to make G-Secs more accessible.
- Reducing the minimum investment amount to ₹10,000 last year to make G-Secs more accessible.
- Implementation Guidelines Pending:Although the RBI announced access to NDS-OM for non-bank brokers in its February monetary policy, no implementation timelines or draft regulations have been issued yet.
- A group of stock brokers has approached the Reserve Bank of India (RBI), requesting a detailed procedural framework for retail participation in government securities (G-Secs) trading on the NDS-OM (Negotiated Dealing System-Order Matching) platform.
| Issue | Concern/Requirement |
|---|---|
| Procedural clarity | Implementation details, account structure (Demat or SGL), and UCC usage needed |
| Technology integration | Brokers need time and resources to integrate back offices with NDS-OM |
| Retail investor education | Awareness about yields, price movement, and secondary markets is lacking |
| Competition with FDs | FDs remain simpler and more familiar for retail investors |
| Minimum investment threshold | Lowered to ₹10,000 by RBI to attract retail investors |
RBI Revises Priority Sector Lending Norms; Enhances Housing Loan Limits
- The overall PSL target remains at 40% of a bank’s total lending, with sub-targets across various categories.
- Urban Cooperative Bank (UCB) investments in bonds issued by NHB/HUDCO on or after April 1, 2007, are not eligible for PSL classification.
- The RBI has increased loan limits for housing loans eligible under PSL: Area Previous Limit Revised Limit Metropolitan cities ₹35 lakh ₹50 lakh Towns with population < 5 mn ₹25 lakh ₹45 lakh Towns with population ≤ 1 mn New classification ₹35 lakh
- The Reserve Bank of India (RBI) has released revised guidelines on priority sector lending (PSL), effective from April 1, 2025. The move aims to better target bank credit towards priority sectors such as agriculture, MSMEs, export credit, education, housing, social infrastructure, and renewable energy.
| Priority Sector | Included Categories |
|---|---|
| Agriculture | Crop loans, agri-infrastructure, ancillary activities |
| Micro, Small & Medium Enterprises (MSME) | Manufacturing, services, and trading-based MSMEs |
| Export Credit | Credit to exporters for goods and services |
| Education | Loans to students for higher education in India and abroad |
| Housing | Enhanced limits as per revised guidelines |
| Social Infrastructure | Loans for schools, healthcare facilities, drinking water facilities, sanitation, etc. |
| Renewable Energy | Loans for solar, wind, and other renewable energy projects with broadened classification |
Payments Council of India Flags Financial Sustainability Challenges for UPI Ecosystem
- The Zero MDR (Merchant Discount Rate) policy, in place since January 2020, has put further pressure on the financial sustainability of digital payment service providers.
- The incentive outlay has been reduced from ₹3,500 crore in FY24 to ₹1,500 crore in FY25, raising concerns about the financial viability of the ecosystem.
- A reasonable MDR of 0.3% for UPI transactions, applicable only to large merchants.
- This structure aligns with existing MDR rates for other payment instruments: Credit cards: ~2% Non-RuPay debit cards: ~0.9%
IMF-World Bank Report
- India’s financial system has become stronger and more diversified since 2017, according to the latest Financial System Assessment Program (FSAP) report conducted jointly by the IMF and the World Bank. The IMF recently released this report, highlighting significant regulatory, structural, and operational improvements.
- RBI’s scale-based regulatory framework and liquidity coverage requirements have strengthened oversight.
- Stable and well-regulated, but growing risks from climate change and cybersecurity threats require enhanced risk management frameworks.
| Area | Challenges Identified | Recommendations by IMF |
|---|---|---|
| Legal and Tax Frameworks | Need strengthening to support long-term growth | Implement robust legal reforms and consistent tax structures |
| Climate Change Risk | Emerging threat to financial stability | Develop climate risk guidelines for insurers and banks |
| Cybersecurity | Increasing risk to digital financial systems | Strengthen cyber-resilience frameworks |
| Public Digital Infrastructure | Risk of exclusion without proper safeguards | Broaden outreach, ensure equitable digital access |
SEBI Raises FPI Disclosure Threshold to ₹50,000 Crore
- The August 2023 circular mandated detailed disclosures for FPIs investing over ₹25,000 crore and those with over half of their portfolio in a single entity.
- The Securities and Exchange Board of India (SEBI) has raised the threshold for granular disclosure requirements by Foreign Portfolio Investors (FPIs) to ₹50,000 crore, from the earlier ₹25,000 crore.
- FPIs with investment exceeding ₹50,000 crore in Indian equities will now need to disclose: Beneficial ownership details Returns and other specifics of the investing entities
- This move follows the doubling of the cash equity market size in India over the past few years.
Paytm Instructs Merchants to Cut Ties with Third-Party Payment Orchestrators Like Juspay
- BharatPe has increased its stake in Trillionloans to 62.2%, after acquiring a 51% controlling stake in 2023.
- According to fintech insiders, Paytm is also expected to impose an additional 1% fee on merchants after they migrate away from orchestration platforms like Juspay.
- From April 1, 2025, all merchant transactions will be routed exclusively through PPSL.
- Fintech giant Paytm has directed its merchants to stop using third-party payment orchestration platforms such as Juspay, effective from April 1.
BHIM 3.0
- NPCI BHIM Services (NBSL), a wholly owned subsidiary of the National Payments Corporation of India (NPCI), rolled out BHIM version 3.0.
- The untapped market of 900+ million potential users highlights enormous scope for further UPI and BHIM adoption.
- The rollout will happen in phases, with full implementation expected by April 2025.
- Family Mode for managing payments across multiple users.
RBI’s Revised Priority Sector Lending Norms to Boost Credit Flow
- In FY24, organic PSL shortfalls were observed in: RBL Bank — 26% of ANBC (vs. required 40%) IndusInd Bank — 32% Federal Bank — 32%
- RBL Bank — 26% of ANBC (vs. required 40%)
- IndusInd Bank — 32%
- Federal Bank — 32%
Finance Ministry Discontinues Medium- and Long-Term Deposits under Gold Monetisation Scheme (GMS)
- Launched: September 15, 2015
- Original Components: Short-Term Bank Deposits (STBD): 1–3 years Medium-Term Government Deposits (MTGD): 5–7 years Long-Term Government Deposits (LTGD): 12–15 years
- Short-Term Bank Deposits (STBD): 1–3 years
- Medium-Term Government Deposits (MTGD): 5–7 years
Implications for Stakeholders
| Stakeholder | Impact |
|---|---|
| Households/Institutions | Limited to short-term deposits, reducing long-horizon monetisation opportunities. |
| Banks | Continued participation through STBDs, subject to profitability. |
| RBI | Will issue revised guidelines on short-term deposit handling. |
NPCI, RBI Approve Increase in ATM Interchange Fees
- The National Payments Corporation of India (NPCI), with approval from the Reserve Bank of India (RBI), has announced an increase in ATM interchange fees for cash withdrawals from ₹17 to ₹19, effective May 1, 2025.
- Circular Date: March 13, 2025
- RBI Approval: Confirmed via RBI letter dated March 11, 2025.
- Implementation Date: May 1, 2025.
| Transaction Type | Previous Interchange Fee | Revised Interchange Fee |
|---|---|---|
| Cash Withdrawal (Domestic) | ₹17 | ₹19 |
| Non-Financial Transactions (Domestic) | ₹6 | ₹7 |
| Balance Enquiries (Nepal & Bhutan) | ₹6 | ₹7 (excluding GST) |
India’s Regulatory Framework
- Creation of sectoral regulators: TRAI for telecom Insurance Regulatory and Development Authority (IRDA) Airports Economic Regulatory Authority (AERA) Central Electricity Regulatory Commission (CERC) Competition Commission of India (CCI)
- Independent regulators to enforce policies through autonomous rulemaking.
- Examples: First CERC Chairperson: An economist. TRAI: Headed by a retired judge and later a banker. SEBI (capital market regulator): Initially headed by a banker. CCI: Headed by a retired IAS officer.
- First CERC Chairperson: An economist.
RBI’s Proposed Ban on Prepayment Charges
- The Reserve Bank of India (RBI) has proposed banning foreclosure or prepayment charges on loans to small firms (up to ₹7.5 crore).
- The move is aimed at curbing “divergent practices” that lead to customer grievances and restrict borrowers from switching lenders for better rates.
- Transparency empowers borrowers and allows informed decision-making.
- Recent research (by Nitin Vishen and Prasanna Tantri) shows that greater transparency lowers borrowing costs and boosts lending to small firms.
SEBI’s Shift Under Tuhin Kanta Pandey
- Relaxed advance fee collection rules for research analysts and investment advisers from the earlier 3-6 month limit to one year
- Deferred oversight on the appointment of Key Managerial Personnel (KMPs) in Market Infrastructure Institutions (MIIs)
- Postponed stricter norms for investment bankers and custodians due to concerns over complexity and cost
- Scrapped the rule mandating merchant bankers to transfer non-listed business to subsidiaries
RBI Infuses ₹44K Cr More into System via Year’s 5th OMO
- The RBI’s liquidity-enhancement measures include: ₹2 lakh crore injected via OMO auctions (till March 2025, excluding this latest auction). $15 billion infused through foreign exchange swaps.
- ₹2 lakh crore injected via OMO auctions (till March 2025, excluding this latest auction).
- The 7.26% GS 2033 security saw the highest demand.
- The Reserve Bank of India (RBI) conducted its fifth open market operation (OMO) purchase in 2025.
Fintech Founders Unite to Form Regulatory Body, Seek RBI Nod
- Founders of top fintech startups Jupiter, Fi, Lendingkart, OneCard, and Signzy — have come together to form a new industry body. The objective is to secure a self-regulatory organisation (SRO) licence from the Reserve Bank of India (RBI).
- The RBI has encouraged formation of a broad-based SRO representing diverse fintech voices.
- Last year, the RBI recognised FACE (Fintech Association of Consumer Empowerment) as the first fintech SRO.
- FCC and Digital Lenders’ Association of India were other key contenders for SRO recognition.
GST Framework for Simplified Compliance
- Declining Indirect Tax Contribution: Dropped from 38.76% (2017-18) to 36.92% (2019-20).
- The Finance Ministry must streamline the GST framework by eliminating unnecessary procedures that complicate compliance. A revamped GST 2.0 should be developed after stakeholder consultations to enhance efficiency.
- Improve user-friendliness by providing step-by-step guidance to taxpayers.
- Harsh Penalties for Errors: Honest taxpayers face criminal penalties for unintentional mistakes—PAC urges more lenient measures.
RBI Governor Advocates Balanced Approach to AML & CFT Regulations
- The FATF Private Sector Collaborative Forum (PSCF) 2025 is being hosted in India for the first time.
- However, Mr. Malhotra cautioned that no risk model is perfect, and regulators must continuously refine and improve assessments.
Supreme Court Ruling Eases GST Compliance for Businesses
- Filed GST returns on time but later found clerical errors in December 2023.
- CGST Act, 2017 allows corrections only until November 30 of the relevant year.
- Reduces litigation and compliance burden caused by rigid timelines under Sections 37(3) & 39(9) of CGST Act.
- Human errors are normal and should not lead to denial of input tax credit (ITC).
Balanced Regulations for Financial Inclusion
- India committed to G20 roadmap for cross-border payment improvements by 2027.
- Regulations should not create barriers to financial inclusion.
- Central KYC Records Registry with over 1 billion records simplifies due diligence.
- India remains committed to G20’s goal of making cross-border payments: Faster Cheaper More Transparent More Inclusive
Banking Laws (Amendment) Bill, 2024
- Directorate of Enforcement handled 912 bank fraud cases in the last five years.
- Threshold increased from ₹5 lakh to ₹2 crore.
- Extended from 8 years to 10 years for directors (excluding chairman & whole-time directors).
- PSBs reported a record ₹1.41 trillion profit in FY24.
Sebi’s DigiLocker Integration
- Data is pushed directly from Registrar & Transfer Agents (RTAs) to DigiLocker (starting April 1, 2025).
- Objective: Reduce unclaimed assets and simplify nominee access to investments.
- Asset Management Companies (AMCs) and Registrars must register as issuers on DigiLocker.
- If different nominees are listed, DigiLocker helps pass on information to legal heirs, expediting the process.
NHB Increases Surprise Inspections to Assess Housing Finance Companies’ Compliance
- NHB issued two key directives: December 10, 2024: HFCs must obtain explicit borrower consent before selling bundled insurance. March 12, 2025: HFCs must offer insurance from at least two providers, ensuring transparency and competitive pricing.
- March 12, 2025: HFCs must offer insurance from at least two providers, ensuring transparency and competitive pricing.
- HFCs must report bad loan data on the 1st of each month to prevent data manipulation.
- December 10, 2024: HFCs must obtain explicit borrower consent before selling bundled insurance.
EPFO to Speed Up Claims Settlement
- Claim settlements have surged from 90 lakh last year to 1.9 crore this fiscal.
- EPFO is set to integrate payments up to ₹1 lakh with UPI for faster transactions.
- The number of validations has been reduced from 27 to 18, and a committee has suggested cutting it further to just 6.
- Auto settlements now take 3 days, compared to several weeks earlier.
NSE IPO Faces Delays
- NSE must address SEBI’s concerns over the next two years before its IPO can move forward.
| Shareholder | Stake (%) |
|---|---|
| Life Insurance Corporation of India (LIC) | 10.72 |
| Aranda Investments (Mauritius) | 5.00 |
| Stock Holding Corporation of India Ltd. | 4.44 |
| SBI Capital Markets Ltd. | 4.33 |
| Mahagony Ltd. | 3.93 |
| State Bank of India (SBI) | 3.23 |
RBI Plans to Double Foreign Investor Cap in Listed Firms
- Previously, only Non-Resident Indians (NRIs) and Overseas Citizens of India (OCIs) could hold up to 5% in an Indian company under Foreign Exchange Management Act (FEMA) Schedule III.
- If a single foreign investor and associates hold more than 34%, it could trigger mandatory takeover offers under Indian laws.
- The Reserve Bank of India (RBI) plans to increase the cap on individual foreign investors in listed companies from 5% to 10%. The combined holding limit for all overseas individual investors in a listed company is proposed to rise from 10% to 24%. The move is aimed at boosting capital inflows amid $28 billion in FPI outflows since September.
- The RBI now proposes to extend this benefit to all foreign investors.
RBI to Discuss Liquidity Management with Bankers
- Recent liquidity trends: Deficit of ₹1.57 trillion (March 26). Peaked at ₹3.2 trillion deficit in January 2025.
- Peaked at ₹3.2 trillion deficit in January 2025.
- RBI's expected comfort level: 1.5%–2% of NDTL.
- Net liquidity narrowed to ₹40,788 crore (March 27).
Sebi Proposes Standardization of Equity Derivatives Expiry Days
- Equity derivatives expiries to be restricted to Tuesdays or Thursdays for each exchange.
- NSE: Thursday
- Enhances regulatory clarity for traders and investors.
Self-Regulatory Organization (SRO) in Fintech Sector
- Defined by RBI’s May 2024 framework, an SRO is meant to: Oversee fintech innovation within regulatory boundaries. Promote compliance with laws while encouraging innovation. Implement light-touch regulations for self-governance.
- Two key players: Fintech Convergence Council (FCC) – Formed a new entity to apply for SRO status. Digital Lenders' Association of India (DLAI) – Competing for the second SRO position.
- Digital Lenders' Association of India (DLAI) – Competing for the second SRO position.
- Oversee fintech innovation within regulatory boundaries.
India’s ATM Network Faces Challenges Amid Rising Interchange Fees
- Effective Date: New fee structure kicks in from May 1, 2025.
- Bank Mergers & De-duplication: Consolidation of ATM networks reduces overall availability.
- Interchange Fees Explained: Banks pay each other for customers’ usage of ATMs outside their network.
- Stabilizing ATM Numbers: Higher interchange fees could improve ATM profitability, preventing further closures.
RBI Likely to Cut Policy Rate by 25 Basis Points in April: Ind-Ra
- Current Repo Rate: 6.25%, after a 25 bps cut in February 2025—the first in five years
- Projected Cuts in FY26: Up to three cuts expected, totaling 75 bps. Could bring the real repo rate to 1.5%
- Tariff Announcement: US to impose 25% tariffs on car and auto component imports from April 2
- Anticipated Rate Cut: 25 basis points (bps) during the April 7-9 MPC meeting
Finance Bill 2025
- Opposition’s Concern: Accusations that India withdrew the 2% digital tax under pressure from US tariffs
- The Finance Bill 2025 reinforces tax stability, simplifies compliance, and fosters economic growth. With customs reforms and a balanced fiscal approach, the government is focused on long-term business competitiveness and economic expansion
- FM’s Response: Dismissed claims, stating that the decision was made in July 2024, before Trump took office
- Ease of Doing Business: Supports domestic businesses, salaried individuals, and exporters
Bank Loans Grow at a Slower Pace in February
- 10.9% YoY growth (as of February 21, 2025) vs. 20.6% YoY growth a year earlier
- 11.7% YoY growth, down from 28.1% in the previous year
- 12% YoY growth, significantly lower than 24.3% a year ago
- 7.3% YoY growth, slightly down from 8.4% last year
Banks May Delay Cutting Special Deposit Rates
- HDFC Bank: 7.35% for 35 months 7.85% for senior citizens
- SBI Amrit Vrishti: 7.25% for 444 days 7.75% for senior citizens
- 7.25% for 444 days
- 7.75% for senior citizens
RBI Mandates Special Clearing for Government Transactions on March 31
- Over-the-counter (OTC) transactions at branches handling government business will remain open till normal working hours on March 31, 2025.
- The Reserve Bank of India (RBI) has directed all banks to participate in special clearing operations on March 31, 2025.
- This is to ensure the accounting of all government transactions within the financial year 2024-25.
- Clearing Timings on March 31, 2025: Presentation Time: 5:00 PM – 5:30 PM Return Session: 7:00 PM – 7:30 PM
8th State Level Coordination Committee (SLCC) Meeting
- Implementation of BUDS Rules: Reviewed progress on enforcing Banning of Unregulated Deposit Schemes (BUDS) Act, 2019 in Sikkim.
- Reviewed progress on enforcing Banning of Unregulated Deposit Schemes (BUDS) Act, 2019 in Sikkim.
- Date & Venue: March 26, 2025, at Tashiling Secretariat, Gangtok
- Financial Frauds & Recovery: Discussed fraud reports from Helpline 1930 and recovery efforts by Sikkim Police.
RBI Deputy Governor Warns NBFCs on Risk Management & Fair Lending
- Expectations from Auditors: Maintain audit rigor. Uphold objectivity, transparency, and ethics in financial reporting.
NSE Submits Response to SEBI on IPO Readiness
- Settlement of Pending Legal Matters Expressed interest in resolving outstanding issues amicably via SEBI’s settlement mechanism. Awaiting SEBI’s final FY24 annual inspection report before addressing any further deficiencies.
- Prioritizing Public Interest NSE stated that 67% of total employee expenses are allocated to public-interest verticals.
- NSE stated that 67% of total employee expenses are allocated to public-interest verticals.
- Awaiting SEBI’s final FY24 annual inspection report before addressing any further deficiencies.
BSE Shares Surge 17% as SEBI Limits Derivatives Expiry Days
- BSE’s Growing Market Share Over the last two months, BSE’s market share jumped from 13% to 19% (QoQ). Options premium volume surged 30% quarter-on-quarter. More brokers and high-frequency traders are now preferring BSE.
- Over the last two months, BSE’s market share jumped from 13% to 19% (QoQ).
- Options premium volume surged 30% quarter-on-quarter.
- BSE stock surged 17% on Friday, marking its best single-day gain in six months, closing at ₹5,438.
RBI Urges NBFCs to Ensure Fair Lending and Strong Redressal Systems
- NBFCs must establish strong grievance redressal systems to protect borrowers from unfair lending practices.
- Increased Regulatory Oversight RBI is actively monitoring lending practices to curb exploitative interest rates. NBFCs need to strengthen compliance frameworks to avoid regulatory actions.
Economy · 64
EU-India FTA
- Crisis of credibility for the WHO An increasing influence of major powers like China has raised concern over its credibility among others.
- An increasing influence of major powers like China has raised concern over its credibility among others.
- Under Donald Trump, the U.S. left the Paris Climate Agreement and crippled the WTO's appellate body, refusing to appoint new members.
- Tariff wars cargoed the global trade norms and coalesced country specific protectionist agonies.
India's GDP growth rate for Q3FY25 at 6.2%
- Inflation & RBI Outlook For its part, the Reserve Bank expects inflatory pressure to average around 4.8% in FY25, easy to 4.2% the following year in FY26, in keeping with its 4.0% medium term target. Questions remain over data veracity, though.
- For its part, the Reserve Bank expects inflatory pressure to average around 4.8% in FY25, easy to 4.2% the following year in FY26, in keeping with its 4.0% medium term target. Questions remain over data veracity, though.
- Sectoral Performance Growth was mainly due to the primary sector, which grew sharply to 5.2% from 1.8% last year. However, manufacturing (4.8%) and services (7.4%) slowed sharply relative to 12.4% and 8.3% in the previous year.
- Growth was mainly due to the primary sector, which grew sharply to 5.2% from 1.8% last year.
Manufacturing PMI
- New Orders & Exports Strong domestic and global demand kept new business intakes rising for the 44th consecutive month.
- New Orders (30%)
- Output (25%)
- Employment (20%)
India to Overtake Japan as the Fourth Largest Economy
- So, India now stands as having economy of ₹331 trillion ($4.2 trillion in FY25) and thus is getting closer to Japan's $4 trillion GDP (2024).
- Looking at Japan's steady and slow growth, it appears that India would soon overtake Japan's economy in 2025.
- It is estimated that India's GDP would grow by 6.5% in FY25, marginally greater than the earlier projection of 6.4%.
- Middle income trap Though growth is rapid, India is still trapped in the lower middle income category. Rupee depreciation may get a real iGDP effect if it shows annual decline of about 2.25% against the dollar.
| Country | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024* |
|---|---|---|---|---|---|---|---|---|
| India | 6.8 | 6.5 | 3.9 | -5.8 | 9.7 | 7.6 | 9.2 | 6.5* |
| US | 2.4 | 3.0 | 2.6 | -2.2 | 6.0 | 2.5 | 2.9 | 2.8 |
| China | 6.9 | 6.7 | 5.9 | 2.2 | 8.4 | 2.9 | 5.2 | 5.0 |
| Japan | 1.7 | 0.6 | -0.4 | -4.2 | 2.7 | 1.1 | 1.5 | 0.1 |
Recommendations by RBI for MSME Lending
- A new horizon in credit appraisal Move from traditional parameters to dynamic lending based on trustworthiness in terms of repayment.
- Move from traditional parameters to dynamic lending based on trustworthiness in terms of repayment.
Single Nodal Agency (SNA) System
- Changes Transparency In terms of the most recent Budget statement, ₹1 trillion from CSS happened to remain in state accounts unspent.
- In terms of the most recent Budget statement, ₹1 trillion from CSS happened to remain in state accounts unspent.
- Facilitates cash float management Thus, punctual fund availability will be ensured for projects such as Jal Jeevan Mission, Pradhan Mantri Awas Yojana, and Swachh Bharat Mission.
- Thus, punctual fund availability will be ensured for projects such as Jal Jeevan Mission, Pradhan Mantri Awas Yojana, and Swachh Bharat Mission.
MGNREGA Work Demand Remains High
- Pending dues in total: ₹14,239.17 crore.
- Unskilled wages: 929.14 crore (6.52% of total dues).
- States with highest negative balances: Tamil Nadu: ₹3,443 crore Uttar Pradesh: ₹2,817 crore Maharashtra: ₹2,758 crore Bihar: ₹2,082 crore
- Tamil Nadu: ₹3,443 crore
FTAs and Customs Duty Impact in India
- Customs duty foregone in FY25: ₹94,172 crore.
- Major revenue losses by region ASEAN: ₹37,875 crore Japan: ₹12,038 crore South Korea: ₹10,335 crore
- ASEAN: ₹37,875 crore
- Japan: ₹12,038 crore
India Financial System Stability Assessment: IMF
- 56% of NBFC lending was financed through market instruments, the remainder by bank borrowings (which have increased since FY19).
- 63% of power sector loans in FY24 came from just three large infrastructure financing NBFCs, rising from 55% in FY20.
- Public sector banks (PSBs) may struggle to maintain the minimum requirement of the 9% Capital Adequacy Ratio (CAR).
- For Policymakers: Ensure financial stability within the purview of NBFC bank linkages and preparations for potential external risks.
RBI Likely to Cut Repo Rate Again!
- As of Monday, the deficit in banking system liquidity stood at ₹1.09 trillion for the last 11 continuous weeks.
- DBS Bank: Expects a 25 bps cut in April and possibly thereafter shift towards an accommodative stance.
- HDFC Bank: The rationale for further rate cuts is supported by moderate Q3 GDP growth.
- Economists project a cut in the repo rate by 25 basis points (bps) in April in support of economic growth.The February meeting of the MPC saw the policy repo rate cut by 25 bps to 6.25%, this was the first cut after nearly five years.
Trump's Reciprocal Tariff Threat
- Manufacturing tariffs: 13.4% greatly over 3x higher in comparison to the US (3.6%) and EU (3.8%).
- Agricultural tariffs: 40%, far exceeding that of the US (7.1%) and EU (9.4%).
- Many goods are subject to tariffs greater than 50%, restricting the Indian trade policy.
- To retaliate, Trump has imposed 100% tariffs on Indian export, which can effectively cripple these industries like textile, engineering goods, and auto components.
India Push for Simplified Trade Norms
- Historically, the EU is India's primary trading partner, emanating 12.2% of the trade share in total Indian trade in 2023.
- Strong confidence in the growth of the Indian market 92% of European businesses feel that there will be a positive impact of the proposed EU-India Free Trade Agreement (FTA).
- 92% of European businesses feel that there will be a positive impact of the proposed EU-India Free Trade Agreement (FTA).
- 72% will most likely invest more in India within two years.
World Bank Report on India's Growth
- Investment & Capital Formation 40% investment to GDP ratio by 2035. Strengthen private sector participation & financial markets. Reduced investment friction and increased infrastructure spending.
- 40% investment to GDP ratio by 2035.
- Forge a path to women accounting for only 55% by 2050 in the suitable workforce.
- Human Capital & Regional Development Forge a path to women accounting for only 55% by 2050 in the suitable workforce. Target the laggard states with the implementation of resources in addressing regional disparity. Improve public expenditure efficiency in these low income areas.
Rupee Gains and Dollar Weakens
- Weakness of the Dollar Dollar index down by 0.6% to 104.9 (lowest since Nov 2024). Market fears regarding US economic growth & trade tariffs.
- Dollar index down by 0.6% to 104.9 (lowest since Nov 2024).
- US Tariffs Update 25% on imports from Mexico & Canada. Import duties on China now doubled to 20%. Trump said India would be hit by reciprocal tariffs from April 2.
- 25% on imports from Mexico & Canada.
India's Bigger Share in US Electronics Market
- Current Market Share: In 2023, India accounted for only 1.9% of the US’s $520 billion electronics imports, with total exports valued at $10 billion.
- The US has imposed a 20% tariff on smartphones, while India's tariff stands at 16.5%, creating an opportunity for Indian exports.
- Mexico lost its Free Trade Agreement (FTA) benefits, now facing a 25% tariff, providing India a chance to expand its presence in desktops, servers, colour TVs, and air conditioners.
- China leads in smartphones (75%), laptops (77%), and wearables (43%).
| Category | Total US Imports ($B) | China | Vietnam | Mexico | India |
|---|---|---|---|---|---|
| Smartphones | 60 | 45 (75%) | 8 | 5 | - |
| Switching & Routing | 51 | 7.9 | 11 | 8.4 | 1.2 |
| Laptops & Tablets | 46.3 | 35.9 (77%) | 7.9 | 0.1 | - |
| Desktops & Servers | 37.1 | 0.65 | 0.09 | 25 (67%) | - |
| Colour TVs | 12 | 1.19 | 1.13 | 9.2 (76%) | - |
| Air Conditioners | 14 | 3 | 0.06 | 6.8 (48%) | 0.04 |
| Wearables & Audio | 12.4 | 5.4 (43%) | 3.3 | 1.8 | - |
Private Investment in India
- Capital expenditure rose from 1.67% of GDP (2019-20) to 3.4% (2024-25).
- Weak Export Performance Exports-to-GDP ratio fell from 25% (2013) to 18.7% (2019), now recovering but still below peak. Investment & economic expansion closely tied to export performance.
- Exports-to-GDP ratio fell from 25% (2013) to 18.7% (2019), now recovering but still below peak.
- Capacity Utilization: Stands at ~75% (just above long-term average). Typically, firms expand at this level, but investment hesitancy persists.
India’s Economic Growth Forecast for FY26 – Crisil Report
- India’s economy is projected to grow at 6.5% in FY26.
- Manufacturing Growth: Expected to average 9% annually between FY25-FY31 (compared to 6% pre-pandemic).
- Manufacturing’s GDP share to increase to 20% by FY31, driven by investments and efficiency improvements.
- India has built “safe harbours” against external shocks: Healthy economic growth. Low current account deficit & external public debt. Adequate forex reserves, providing policy flexibility.
Pradhan Mantri Mudra Yojana (PMMY) – Disbursement Update (2015–2025)
- ₹31.85 trillion disbursed out of ₹32.61 trillion allocated under PMMY (April 2015 – Feb 2025).
- Launched: 8 April 2015.
- Loan Limit Increase: Raised from ₹10 lakh to ₹20 lakh, effective October 2024 (as per Union Budget 2024-25).
- Loan Accounts Approved (2015–2025):516 million, with the highest numbers in: Bihar – 58 million Tamil Nadu – 57 million Uttar Pradesh & West Bengal – 50 million each Karnataka – 49 million
India’s Services PMI Rebounds Amid Economic Challenges
- Manufacturing PMI, however, fell to 56.3, a 14-month low, but both sectors remain in expansion mode (PMI > 50).
- GDP Growth (Q3FY25): The National Statistical Office (NSO) reported 6.2% real GDP growth, reinforcing economic resilience despite capital outflows.
- AI Disruption in Services The IT sector’s growth forecast: Expected to rise 5.1% in FY25 (from 3.8% in FY24), but below its historical 16% CAGR. AI is reshaping the industry, reducing earnings from new contracts and changing hiring & training practices.
- The IT sector’s growth forecast: Expected to rise 5.1% in FY25 (from 3.8% in FY24), but below its historical 16% CAGR.
India’s Bilateral Investment Treaty (BIT) Framework
- India shall make changes in its BIT framework not bringing it back to the favor of investors, which was the scenario before the year 2016. A balance will boost credibility along with deep integration into the global value chains and rapid economic growth.
- Instability of Policies Uncertainty emerged following the abrupt termination of 77 BITs in 2016. The new framework shall ensure consistency and predictability through transparent stakeholder consultations.
- Uncertainty emerged following the abrupt termination of 77 BITs in 2016.
- The 2015 model BIT of India did not deliver, since it came into existence with only five agreements (Belarus, Kyrgyzstan, Brazil, UAE, Uzbekistan). Foreign Direct Investment (FDI) inflows have only marginally increased from $60.2 billion (2016 17) to $70.9 billion (2023-24) because of investors' citing legal unpredictability and restrictive dispute resolution mechanisms.The current BIT framework adopted to avert the legal challenges as seen in the Cairn Energy and Vodafone cases turned out to be too restrictive for global investors.
Rupee Down again
- In the NDF market, there was strong demand for the dollars without deliverability due to maturities of $34 billion against the rupee.
- The aforementioned RBI intervention was carried out in the morning between 87.30 Rs. and 87.35 Rs. in order to manage the rupee volatility and to gainfully exit the market for the time being on this subject.
- The offshore Chinese yuan was down 0.2% on the back of deflationary worries emanating from China, thus pouring further negative weight on the Asian currencies.
- The dollar index, meanwhile, declined near a 4-month low (103.7) in response to soft US employment data and uncertainties arising from geopolitical vulnerabilities to the global markets.
Government Seeks ₹6.79 Trillion in Additional Expenditure
- Unified Pension Scheme (UPS): ₹7,000 crore under the overall limit of ₹13,449 crore allocated for pensions.
- Fertiliser Subsidy: ₹12,000 crore for the Department of Fertilisers.
- The nominal GDP estimate has been revised upwards by 2.1% and has created some fiscal room for the economy, which has helped in restraining the fiscal deficit to GDP ratio currently at 4.8% for FY25.
- Such additional spending, though, will push up the fiscal deficit number beyond the revised estimate of ₹15.7 trillion, although analysts expect the deficit to remain at around 4.7% of GDP.
AI in Inflation Forecasting
- Studies like Faria-e-Castro & Leibovici (2024) at the Fed show that LLMs: Provide lower mean-squared errors in inflation forecasts. Outperform traditional Survey of Professional Forecasters methods.
- Rise of Generative AI (GAI): 40% of US adults (by Aug 2024) use AI, with 28% using it at work (Bick et al., 2024). Half of US households now use AI tools (Aldasoro et al., 2024).
- 40% of US adults (by Aug 2024) use AI, with 28% using it at work (Bick et al., 2024).
- Historical Shift in Central Bank Policy Pre-Global Financial Crisis: Struggled to control inflation (fear of wage hikes, fiscal expansion). Post-Pandemic (2022-2025): Struggling to push inflation down amid volatile global trends.
India Plans New Export Promotion Schemes to Counter US Tariffs
- New support measures are being finalised by the government for exporters against proposed US tariffs and reciprocal duties. The schemes will be finalised within a month's period under the Rs 2,250 crore Export Promotion Mission announced in the Budget.
- Support for Small Exporters: Special focus on MSMEs.
- Collateral Free Loans: Access to finance has become easier for exporters.
- Compliance Assistance: Exporters shall be assisted in compliance with non tariff regulations of developed countries.
GDP Revisions in India
- Example: 2020-21 (COVID year): Final GDP grew 1.9 percentage points higher than initial estimates. 2016-17 (Demonetization year): GDP revised up from 7.1% to 8.3%. 2018-19 (Election year): Revised down from 7.2% to 6.5%.
- 2016-17 (Demonetization year): GDP revised up from 7.1% to 8.3%.
- 2018-19 (Election year): Revised down from 7.2% to 6.5%.
- 2023-24 First Revised Estimate (FRE) pegged GDP growth at 9.2%, up from 7.3% in the FAE (a 1.9 percentage point increase). Manufacturing sector growth doubled, alongside higher government and private consumption expenditures.
India's Retail Inflation Eases
- Retail Inflation Falls The number came down to a 3.61% in February, which is a 7 month low, primarily attributed to a fall in food prices.
- The number came down to a 3.61% in February, which is a 7 month low, primarily attributed to a fall in food prices.
- Food Inflation Cools Slumping from 6% in January to 3.75%, with price drops seen in vegetables ( 1.07%), pulses ( 0.35%), and eggs ( 3.01%).
- Slumping from 6% in January to 3.75%, with price drops seen in vegetables ( 1.07%), pulses ( 0.35%), and eggs ( 3.01%).
India’s GDP Growth & Economic Trends
- GDP Growth (Q3 2024-25): 6.2%, up from 5.6% in Q2, but lower than 6.5% in Q1.
- Government has spent ₹7.57 lakh crore (till Jan 2025).
- 2023-24 GDP Growth Revised to 9.2% (from 8.2%) Manufacturing growth revised up by 2.4 pp → Indicates underestimated industrial activity. Financial & real estate sector revised up by 1.9 pp → Stronger-than-expected services rebound.
- 2024-25 GDP Growth at 6.5% (sharp 2.7 pp fall vs. 2023-24) Key cause: Gross capital formation (investment) growth fell from 10.5% to 5.8%, highlighting slower investment momentum.
Moody's Outlook on Indian Banks
- Key Banking Numbers (RBI) for Balance Date February 21, 2025 Credit to Deposit Ratio: 79% (last year 78%). Growth in Bank Credit: 11.0% YoY. Growth in Deposit: 10.3% YoY.
- Stark Decline in NPLs Systemwide NPL ratio collapsed from 7.3% (in March 2024) to 2.6% (in September 2024). Mostly because of recoveries and write offs of legacy bad loans.
- Systemwide NPL ratio collapsed from 7.3% (in March 2024) to 2.6% (in September 2024).
- Growth in Bank Credit: 11.0% YoY.
India’s Digital Economy
- Strong Digital Infrastructure 99% of the population is covered by wireless internet, ensuring connectivity potential. Digital public infrastructure (e.g., UPI, Aadhaar, ONDC) has enabled rapid economic digitization.
- 99% of the population is covered by wireless internet, ensuring connectivity potential.
- Digital Access Gap Only 58% of Indians have internet access, leaving over 40% of the population digitally excluded. In contrast, the median score for other countries is 93% internet access, meaning India has one of the largest digital access gaps globally.
- Only 58% of Indians have internet access, leaving over 40% of the population digitally excluded.
| Metric | India’s Score (%) | Median Score (32 Countries) | Gap |
|---|---|---|---|
| Internet Access | 58% | 93% | -35% |
| Smartphone Usage | 49% | 82% | -33% |
| E-commerce Adoption | 28% | 52% | -24% |
| Wireless Coverage | 99% | 100% | -1% |
The Global Challenge of Tax Evasion
- Real Estate Investments With the introduction of multilateral financial information exchange in 2017, tax evaders shifted wealth from offshore bank accounts to real estate to avoid financial scrutiny.
- With the introduction of multilateral financial information exchange in 2017, tax evaders shifted wealth from offshore bank accounts to real estate to avoid financial scrutiny.
- The 2021 Global Minimum Tax Agreement 140+ countries agreed to a minimum corporate tax rate of 15%. This was expected to increase global tax revenue by 10%, but actual collections fell far below expectations due to loopholes.
- The Inclusive Framework (2017) Introduced multilateral exchange of financial information among banks. Expanded to over 100 countries by 2023, reducing global bank secrecy and cutting offshore tax evasion by one-third.
| Challenge | Impact |
|---|---|
| Loopholes & Tax Competition | Some nations offer incentives to attract corporations, continuing a "race to the bottom." |
| Shell Companies | Billionaires use offshore shell firms to reduce tax payments below 0.5% of their wealth. |
| US Corporations & Tax Havens | Around 40% of profit shifting to tax havens is done by US-based MNCs, costing global tax systems nearly 10% of corporate tax revenues. |
| Lack of US Participation in CRS | The Common Reporting Standard (CRS) for financial transparency lacks US involvement, limiting its global effectiveness. |
Food Inflation in India
- Food inflation dropped to 3.75%, the lowest since May 2023.
- The decline follows a peak of 10.87% in October 2023, which had complicated RBI’s monetary policy.
- Horticultural crops production estimated at 362.09 million tonnes, a 2.07% increase from 2023-24.
- Food inflation averaged 8.4% in 2024, significantly impacting household consumption.
India’s Economic and Financial Trends
- Food inflation, a major component of household expenses, declined to 3.75%, the lowest in nearly two years, down from 10.87% in October 2024.
- The drop in inflation is a positive sign for policymakers, as it supports the government’s 6.5% GDP growth target for FY 2025.
- New Systematic Investment Plans (SIPs) dropped to 44.6 lakh, the lowest in FY 2025.
- February’s retail inflation fell to 3.61%, a seven-month low, signaling easing price pressures.
Gold Surges Past $3,000 Amid Market Turmoil
- Year-to-Date Performance: Gold has risen nearly 14% in 2025.
- Futures Surge: U.S. gold futures climbed 0.4% to $3,002.30.
- Gold Price Milestone: Spot gold hit an all-time high of $3,004.86 before settling at $2,991 per ounce.
- Trump’s Tariff War: Protectionist policies and tariffs have triggered economic uncertainty, pushing investors toward safe-haven assets.
Block Assessment Scheme for Income Tax Search Cases
- Single Consolidated Return Taxpayers will now file one return covering six years plus the part-year of investigation. Replaces the need for separate filings for each year under scrutiny. Aligns with the block assessment scheme introduced on September 1, 2024.
- Aligns with the block assessment scheme introduced on September 1, 2024.
- Taxpayers will now file one return covering six years plus the part-year of investigation.
- Aims to reduce duplication, legal disputes, and reassessments of already disclosed income.
RBI Rate Cut Prospects & Economic Implications
- Consumer Price Index (CPI) inflation fell to 3.61% in February, down from 4.26% in January, slipping below the RBI’s 4% target for the first time in seven months.
- Interest Rate Derivatives Pricing in Cuts One-year OIS (Overnight Index Swap): Trading at 6.12%. Two-year OIS: Trading at 5.92%. The OIS market generally anticipates rate movements ahead of actual policy decisions, indicating market confidence in further cuts.
- One-year OIS (Overnight Index Swap): Trading at 6.12%.
- Liquidity Infusion by RBI RBI has injected ₹1.5 lakh crore via Open Market Operations (OMO) and $20 billion through dollar-rupee swaps. This liquidity easing measure signals the central bank’s willingness to support lower borrowing costs.
The Gold Rally
- However, fundamental drivers (central bank purchases, macro risks) are strong enough to mitigate a speculative downturn.
- Investors are diversifying away from dollar exposure due to concerns over tariffs, trade policies, and economic uncertainty.
- Retail demand is weakening, especially in Asia, due to: High gold prices, making jewellery less affordable. A stronger dollar, which increases local currency costs of gold imports. Off-season slump, further discouraging inventory buildup by jewellers.
- Off-season slump, further discouraging inventory buildup by jewellers.
India’s WPI Inflation Rises
- Overall WPI Inflation India’s Wholesale Price Index (WPI)-based inflation rose to 2.38% in February from 2.31% in January.
- India’s Wholesale Price Index (WPI)-based inflation rose to 2.38% in February from 2.31% in January.
- Inflation in manufactured products (which carry a 64.2% weight in the index) rose to 2.86% in February from 2.51% in January.
- The Bloomberg Commodity Price Index rose by 4.1% in January and 9.2% in February, reversing a six-month deflationary trend.
India’s Trade Balance Dynamics
- If this surplus is neutralized by potential US protectionist measures (such as retaliatory tariffs), India’s total trade deficit could worsen by 10.7% to 22.14%.
- China accounts for approximately 30–43% of India’s total trade deficit over the past five years.
- If India manages to reduce the deficit with China by even 50%, it could more than offset any shortfall from US trade friction.
- Growing Reliance on the US for Trade Surplus India’s trade surplus with the US has steadily risen from $17.27 billion (2019-20) to $35.32 billion (2023-24). This surplus acts as a cushion against India’s large overall trade deficit. If this surplus is neutralized by potential US protectionist measures (such as retaliatory tariffs), India’s total trade deficit could worsen by 10.7% to 22.14%.
Growth in Net Direct Tax Collections
- Overall Growth Net direct tax collections rose by 13.13% YoY to ₹21.3 trillion as of March 16, FY25. Driven largely by strong advance tax collections and improved compliance.
- Net direct tax collections rose by 13.13% YoY to ₹21.3 trillion as of March 16, FY25.
- Advance Tax Collections Surge Advance tax collections increased by 14.6% to ₹10.4 trillion, showing robust business and personal income growth. The fourth installment deadline (March 15) further accelerated collections.
- Advance tax collections increased by 14.6% to ₹10.4 trillion, showing robust business and personal income growth.
Rupee Strengthens for the Third Day
- Key Drivers The rupee appreciated for the third consecutive session, reflecting improved sentiment toward the domestic currency. The dollar index fell by 0.2% to 103.5, close to a five-month low, weakening the greenback globally.
- The dollar index fell by 0.2% to 103.5, close to a five-month low, weakening the greenback globally.
- Local Market Dynamics Exporter and foreign bank dollar sales supported the rupee, indicating strong supply of dollars in the market. The rupee touched an intraday high of 86.76, the strongest in three weeks, before settling slightly lower at 86.80 per dollar (previous close: 87).
- Exporter and foreign bank dollar sales supported the rupee, indicating strong supply of dollars in the market.
OECD India’s Economic Growth Forecast
- FY26: Revised downward to 6.4% (from 6.9% projected in December 2024).
- United States Growth expected to slow to 2.2% in 2025 and 1.6% in 2026.
- Growth expected to slow to 2.2% in 2025 and 1.6% in 2026.
- China Growth forecast at 4.8% in 2025 and 4.4% in 2026.
SBI Report on U.S. Tariff Impact
- Expected decline in India’s exports to the U.S.: 3–3.5% post-tariff implementation.
- Possible contributing factors: A downturn in U.S. GDP growth Slowdown in U.S. exports and consumption
- India’s strategy includes: Export diversification Greater value addition Exploring alternative markets and sectors Redrawing supply chain routes from Europe to the U.S. via the Middle East
- Export diversification
India’s Decline in Goods Trade
- An unusually high base effect prevailing during February 2023 (which happened to be a leap year with greater trade numbers) has also contributed to this steep fall in percentages.
- Oil Imports Near to a decline of one third following India reducing supplies in response to latest U.S. sanctions on Russian oil producers and tankers in January 2024.
- Near to a decline of one third following India reducing supplies in response to latest U.S. sanctions on Russian oil producers and tankers in January 2024.
- Exports had shrunk by 10.9% to cross $36.91 billion.
India-New Zealand FTA
- Negotiations started 14 years back and after 10 rounds have remained stalled with no formal discussions since February 2015.
- Resumption of negotiations after 10 years was announced during the visit of PM Luxon to India from March 16 to 20, 2025.
- India and New Zealand plan to sign a full fledged and comprehensive Free Trade Agreement (FTA) within the next 60 days. The proposed FTA is expected to increase bilateral trade 10 fold over the next 10 years.
- According to the GTRI think tank, India will hardly buy New Zealand dairy ($0.57 million), thus showing limited existing trade in this sensitive sector.
Why a Safeguard Duty?
- However, it already has raised metal stocks on the National Stock Exchange (NSE) The Nifty Metal Index increased by 1.67%, closing at 9,185.20. Hindustan Zinc stocks were up by 9.48% in intraday trading.
- The Nifty Metal Index increased by 1.67%, closing at 9,185.20.
- A surge was triggered by trade diversion after the U.S. implemented a 25% tariff on steel and aluminum (effective March 12) on the latter.
- Hindustan Zinc stocks were up by 9.48% in intraday trading.
| Product Category | Action Taken |
|---|---|
| Non-alloy & alloy steel flat products | Preliminary findings (March 2025) recommend a 12% safeguard duty for 200 days. |
| Low-ash metallurgical coke | Quantitative restrictions imposed from January 1 – June 30, 2025. |
| Ferromolybdenum | Two-year safeguard duty announced in May 2023. Imports from South Korea faced a 5% duty (Oct 2023 – Oct 2024), followed by a 3.75% duty for the next year. |
Improved System for Tracking Microenterprises
- It were also some issues in the execution of 7th economic census (2019-20) where most of the assignments were done to Common Service Centres (CSC) assigned by IT ministry and with very limited participation for the state.
- The Chinese economic census of 2023 points out that, even at the top of large industrial economies, millions exist in microenterprises.
- Economic census of India is scheduled to monitor microenterprises along with other firms once in every five years.
- Since inception in mid 1970s, following chronic challenges bad data quality, coordination problems between NSO and state DES, staff and supervision issues have plagued the census.
Role of Manufacturing in India’s Economic Growth (2013-2024)
- The national goal of making manufacturing contribute 25% of GDP looks increasingly elusive.
- Share in Gross Value Added (GVA) has dropped from 16.5% to 14.3%.
- Share in gross capital formation has fallen from 17.3% to 15.7%.
- Ratio of value added to gross output (a measure of productivity) declined from 21.6% to 20.6%.
Rupee’s Surge to 10-Week High
- The sharp surge in cash market volumes (+53%) shows robust retail and institutional participation, signaling broader market optimism.
- Investor Sentiment: Increasing FII participation reflects confidence in India’s market fundamentals, monetary stability, and political clarity heading into 2025.
- Increasing FII participation reflects confidence in India’s market fundamentals, monetary stability, and political clarity heading into 2025.
- Global Factors The Fed’s decision to hold rates steady and signal potential future rate cuts weakens the dollar globally, providing additional support to emerging market currencies like the rupee.
Indian Bond Market and Currency Surge
- March is set to become the strongest month for foreign debt inflows since August 2024, with ₹8,497 crore invested up to mid-March.
- The yield on the benchmark 10-year government bond has dropped to 6.62%, the lowest level in three years.
- Forecasts suggest yields could soften further to around 6.60% by the end of the fiscal year.
- Foreign investors have made substantial investments under the Fully Accessible Route (FAR): ₹8,560 crore in net inflows this week. ₹644 crore invested on Friday alone.
E-commerce Price Index
- E-commerce Market Growth: Projected to surge from ₹12.2 trillion in 2024 to ₹24.1 trillion by 2028 (source: GlobalData).
- Projected to surge from ₹12.2 trillion in 2024 to ₹24.1 trillion by 2028 (source: GlobalData).
- The National Statistics Office (NSO) plans to launch: A revised CPI series in February 2026. New series for GDP and Index of Industrial Production (IIP).
- Digital Penetration: 895 million internet connections as of June 2023. Smartphone base expected to cross 1.1 billion by 2025.
Impact of Donald Trump's Policies
- Jerome Powell’s Comments: The Fed Chairman highlighted high uncertainty, largely due to tariffs, which could delay achieving the 2% inflation target.
- Unemployment: Likely to increase in 2025.
- Monetary Policy: The Fed remains on track for rate cuts totaling 50 basis points in 2025, but the timeline could shift due to trade uncertainties.
- Reciprocal tariffs set to be imposed on April 2 could significantly disrupt global trade.
India’s Private Sector Output Growth Slows in March: HSBC Flash PMI
- The slowdown came amid a quicker expansion in manufacturing and a softer increase in services activity, according to the HSBC Flash Purchasing Managers’ Index (PMI).
- The PMI index, compiled by S&P Global, fell to 58.6 in March from 58.8 in February.
- This index measures monthly changes in combined output of manufacturing and service sectors.
- The index has stayed above the neutral 50 mark for the 44th consecutive month, indicating continued growth.
Parliamentary Panel Urges MoSPI to Salvage Interim Data from 7th Economic Census
- The committee noted the long gap of over 12 years between the 6th Economic Census (2013) and the proposed 8th Census, creating a large data void.
- Fieldwork for the 7th Economic Census began in 2019 and took two years to complete due to the Covid-19 pandemic.
- For the upcoming 8th Economic Census, the ministry plans: Full ownership by states/UTs in engaging enumerators and deploying supervisors. Extended fieldwork timeline from 3 months in the 7th Census to 9 months, allowing sufficient time for data collection.
- The total outlay for the 7th Economic Census was ₹ 913 crore, of which ₹ 691.04 crore has been utilised.
India to Expand Extended Producer Responsibility (EPR) for a Circular Economy
- The government, with the support of NITI Aayog, has identified 10-11 sectors for potential implementation.
- EPR is a policy approach that makes producers accountable for the entire lifecycle of their products.
- Ved Prakash Mishra, Joint Secretary, Ministry of Environment, Forest & Climate Change (MoEF&CC), announced the move at a FICCI event.
RBI’s $10-Billion Dollar-Rupee Swap Auction Receives Over 2x Bids and Higher Premium
- However, this premium was lower than the 673 paisa recorded during the first swap auction held on February 28, 2024.
- The RBI conducted the auction to address the persistent liquidity deficit in the banking system that began in mid-December 2024.
- In this buy-sell swap structure: The RBI buys dollars and injects rupee liquidity. The second leg, scheduled for March 2028, involves the RBI selling back $10 billion at the prevailing exchange rate plus the agreed premium of 592 paisa.
- According to RBI data, the daily average system liquidity deficit in March was ₹1.6 lakh crore.
| Aspect | Details |
|---|---|
| Auction Size | $10 billion |
| Total Bids Received | $22.3 billion (2x oversubscribed) |
| Average Premium | 592 paisa (vs. expected 580-590 paisa) |
| Previous Auction Premium (Feb '24) | 673 paisa |
| System Liquidity Deficit (March) | ₹1.6 lakh crore daily average |
| Second leg settlement | March 2028 |
S&P Global Cuts India’s FY26 GDP Growth Forecast to 6.5%
- RBI rate cuts: The Reserve Bank of India is projected to cut interest rates by 75–100 basis points in the current cycle, as inflation moderates closer to the 4% target.
- Factors supporting India’s growth: Cooling food inflation Tax benefits announced in the FY26 Union Budget Lower borrowing costs enhancing discretionary spending
- S&P incorporated additional 10% U.S. tariffs on Chinese exports, raising the effective tariff rate to 35%.
- Tax benefits announced in the FY26 Union Budget
| Agency | Previous Forecast (FY26) | Latest Forecast (FY26) |
|---|---|---|
| S&P Global | 6.7% | 6.5% |
| IMF | — | 6.5% |
| World Bank | — | 6.6% |
| Nomura Asia | — | 6.4% |
| ADB | — | 6.7% |
| Fitch | — | 6.5% |
| OECD | — | 6.2% |
Rupee Volatility and Trade Negotiations with the US
- Currency fluctuations driven by the US Dollar Index, which rose 5% (Nov 2024 - Jan 2025) in anticipation of Trump’s policies but has since corrected.
- March 2025: One of the best-performing Asian currencies, up 2%.
- FY25 (Ending March 31, 2025): Down 3% against the US dollar.
- India’s current account deficit (CAD) for FY25 is projected at a modest 1% of GDP.
Trade Uncertainty, Geopolitical Risks Pose Challenges to India’s Growth
- However, strong private investment is expected to drive India’s GDP growth to 6.5% in FY25 and sustain growth momentum in FY26 (6.3%-6.8%).
- FY25 Fixed Investment Growth Estimate: 6.1% (down from 8.8% in FY24).
- The FY25 GDP target of 6.5% remains achievable if private sector confidence and investment momentum persist.
- PMI indices (Purchasing Managers' Index) remain expansionary.
Ecommerce Integration Boosts MSME Growth & Financial Access: ICRIER Survey
- Limited fixed assets: ₹3.18 lakh average fixed assets per MSME in 2022-23. ₹2.15 lakh average for manufacturing enterprises.
- ₹3.18 lakh average fixed assets per MSME in 2022-23.
- Unsecured loans account for only 25% of total MSME credit from banks (as of March 2024).
- 51% of ecommerce-integrated MSMEs found their digital presence useful for securing external finance from banks and NBFCs.
MSMEs in India
- Share in GDP (Gross Value Added): 2020-21: 27.3% 2022-23: 30.1%
- 2020-21: 27.3%
- 2022-23: 30.1%
- Export Growth: 2020-21: ₹4 trillion 2024-25: ₹12.39 trillion
NACIN and IMU Sign MoU to Strengthen Marine Enforcement Training
- Located at NACIN’s new campus in Palasamudram, Andhra Pradesh, inaugurated in January 2024.
- Equipped with: Full Mission Ship Maneuvering Simulators & ECDIS Simulators. Training in ship navigation, emergency response, and smuggling interdiction. Firefighting drills, search & rescue operations, and firearms training.
- Full Mission Ship Maneuvering Simulators & ECDIS Simulators.
- Enhancing CBIC Officers' Capabilities: Specialized training for marine preventive work.
PAC’s 19th Report on GST Implementation
- The GST (Compensation to States) Act, 2017, promised States 14% annual revenue growth for five years (2017–22), using FY16 as the base year.
- Revenue Decline: The report highlights a 2% drop in indirect tax revenue between FY18 and FY20, before the COVID-19 pandemic.
- ₹32,577.73 crore in inconsistencies were found in a sample of 10,667 cases.
- States demand a larger GST revenue share (70%-80%), up from the current 50%.
India’s Fiscal Deficit Narrows for April-February FY25
- Lower deficit despite increased spending: The government managed to reduce the fiscal deficit even as total expenditure grew to ₹47.16 trillion from ₹44.90 trillion last year. This suggests better revenue mobilization and efficient fund allocation.
- On track for fiscal consolidation: The government’s target of reducing the fiscal deficit to 4.8% of GDP in FY25 and 4.4% in FY26 appears achievable, provided revenue trends continue and spending remains disciplined.
- The sharp increase from ₹3.76 trillion last year highlights diversification of revenue sources, including dividends from PSUs, spectrum sales, and RBI surplus transfers.
- The 8% YoY increase in capital spending suggests continued investment in infrastructure, manufacturing, and defense.
India’s Core Sector Growth Slows to 5-Month Low in February
- Core sector growth declined to 2.9% in February 2025, down from 5.1% in January and 7.1% a year ago.
- Impact on Industrial Production: Core sector industries contribute 40.27% to the Index of Industrial Production (IIP). Slower growth here suggests IIP may also decelerate in the coming months.
- March Core Sector Growth Projections: India Ratings (Ind-Ra): ~4.0% Bank of Baroda: ~4.5%
- Bank of Baroda: ~4.5%
Agriculture · 31
India’s Agricultural Exports Amid U.S. China Trade War
- From the other end, China cut back on imports from the U.S., down 14% in 2024 following a 20% drop in 2023.
- As of March 10, China imposed duties on imports from the U.S., including: Chicken, wheat, corn, cotton, sorghum, meat, soybeans, and dairy products. The new tariffs followed the announcement of increased U.S. import duties on Chinese goods to 20%.
- The new tariffs followed the announcement of increased U.S. import duties on Chinese goods to 20%.
- Structure of Challenges Minimum integration into global value chains. Indian high import duty further restricts export trade competitiveness. Technology lag behind that of other countries. Indian logistics cost: 8 9% vs. 5 6% in developed countries.
Benefits of the MSP
- Only 15% of paddy farmers and 9.6% of wheat farmers avail of MSP enabled procurement.
- 31.3% of total paddy farmers and 23.5% of total wheat farmers sell in the market a big portion of their surplus through MSP.
- In contrast, only 10.5% of small paddy farmers and 4.5% of small wheat farmers are in the fold of MSP procurement.
- Farmers selling at MSP enjoy Yield in paddy higher by 13.5% Yield in wheat higher by 5%
India’s Gene Bank
- First Gene Bank in India (Established 1996) Under the auspices of ICAR NBPGR, New Delhi, which has 12 Regional Stations. Maintains 0.47 million accessions of cereals, millets, legumes, oilseeds, and vegetables.
- Provided in the Budget 2025-26 by the Ministry of Finance.
- Capacity: 1 million lines of germplasm to strengthen agricultural biodiversity.
- Under the auspices of ICAR NBPGR, New Delhi, which has 12 Regional Stations.
Govt Extends Subsidised Loan Scheme to Cooperative Sugar Mills
- Cooperative sugar mills will get a 50% interest subvention on project loans or 6%—whichever is lower.
- Most cooperative mills secure loans through National Cooperative Development Corporation (NCDC), which charges ~8.5% interest.
- Effective interest rate after subvention: ~4.25%.
- For a ₹200 crore loan, this is a highly attractive rate, said Prakash Naiknavare, MD, National Federation of Cooperative Sugar Factories.
Makhana: India’s Superfood Revolution
- Nutritional profile: 14.5% fibre and 9.7% protein per 100g. Gluten-free, low-calorie, and suitable for vegan & low-carb diets.
- 14.5% fibre and 9.7% protein per 100g.
- Bihar produces 90% of the world’s makhana.
- The industry generates: ₹100.3 billion in revenue annually. 500,000+ employment opportunities (farmers, processors, traders).
Women-Led Farming Cooperatives in the Eastern Himalayan Region (EHR)
- Multi-State Cooperative Societies Act (2002) & Ministry of Cooperation (2021) have encouraged women’s participation.
- Women contribute over 70% of agricultural labor in the region.
- Assam’s Mahila Kisan Sashaktikaran Pariyojna (MKSP) (2016-17) empowered 12,500 Self-Help Groups (SHGs).
- Meghalaya’s Pla Tangka Cooperative Society (PTCS) (2025) aims to strengthen financial access for SHGs.
Rural Co-operative Credit (RCC)
- Primary Agricultural Credit Societies (PACS): 1,06,955 societies across 6.5 lakh villages (March 2023).
- Investment: Approximately ₹1,000 crore will be invested collectively.
- RCC share in total agriculture credit: 13% in FY22 → 11% in FY23 → 9.5% in FY24.
- 13% in FY22 → 11% in FY23 → 9.5% in FY24.
State Governments’ Farmer Incentives
- A study by C.S.C. Sekhar at Delhi University estimated that a combination of MSP procurement and DPP would cost the government ₹ 2.65 lakh crore to ₹ 3.4 lakh crore annually (based on 2019-20 prices).
- The study suggests an annual per-hectare payment of ₹ 19,875–₹ 25,980, ensuring direct farmer income support.
- Current PM-KISAN disbursement (₹ 6,000 per year) is much lower than this estimate.
- If the Centre covers ₹ 10,000–₹ 12,500 per farm, the cost would be ₹ 1.44–₹ 1.89 lakh crore per year—cheaper than MSP-based procurement.
| State | Additional Support for Farmers |
|---|---|
| Madhya Pradesh | ₹ 4,000 per hectare for paddy growers (₹ 480 crore burden); ₹ 125 per quintal bonus for wheat (₹ 2,600 per quintal total price). |
| Rajasthan | PM-KISAN top-up to ₹ 9,000 per annum; ₹ 150 per quintal wheat bonus. |
| Chhattisgarh | Krishak Unnati Yojana (₹ 10,000 crore) includes ₹ 19,257 per acre subsidy and paddy purchase bonus. |
| Odisha | CM-KISAN scheme (₹ 2,020 crore allocation); ₹ 10,000 per annum (₹ 4,000 under CM-KISAN + ₹ 6,000 under PM-KISAN); ₹ 12,500 livelihood support for landless farmers. Paddy procurement at ₹ 3,100 per quintal (vs. ₹ 2,300 MSP). |
AAHAR 2025
- Entrepreneurs and manufacturing firms from 17 states and multiple Union Territories
- The Agricultural and Processed Food Products Export Development Authority (APEDA) took center stage at the 39th edition of AAHAR 2025, held from March 4–8, 2025, at Bharat Mandapam, New Delhi. The event, organized by the India Trade Promotion Organization (ITPO), underscored India's growing influence in the global agriculture and food processing industry.
- APEDA facilitated the participation of 95 exhibitors, including:
- APEDA’s participation at AAHAR 2025 marked a significant milestone in India's food export strategy, demonstrating its agricultural prowess and commitment to sustainable food production. The event further cemented India's role as a global leader in processed and organic food exports, opening doors for enhanced trade partnerships and investment opportunities.
Turning Waste into Wealth
- The researchers developed a graphitic carbon-based catalyst that enables an electrochemical process to convert urine into percarbamide with nearly 100% purity.
- Sustainable Fertilizer Production: Percarbamide combines the nitrogen benefits of urea with the oxidative power of hydrogen peroxide, making it ideal for slow-release fertilizers.
MSP: Balancing Farmer Support & Market Efficiency
- Limited Outreach Only 15% of paddy farmers and 9.6% of wheat farmers benefit from MSP procurement. Mostly large farmers benefit, while small & marginal farmers (producing 53.6% of paddy and 45% of wheat) face low participation.
- Only 15% of paddy farmers and 9.6% of wheat farmers benefit from MSP procurement.
- Mostly large farmers benefit, while small & marginal farmers (producing 53.6% of paddy and 45% of wheat) face low participation.
- MSP ensures food security and protects farmers from price fluctuations.
Pradhan Mantri Matsya Kisan Samridhi Sah-Yojana (PM-MKSSY) Launched Under PMMSY
- Implemented for four years (FY 2023-24 to FY 2026-27).
- Launched on 11th September 2024 under PM-MKSSY.
- Total outlay: ₹6,000 crore (₹3,000 crore public finance + ₹3,000 crore private investment).
- 40% of premium paid with a ceiling of ₹25,000 per hectare or ₹1 lakh per farmer (for 4 hectares WSA).
Parliamentary Panel’s Recommendations for Agriculture Sector
- Small and marginal farmers (owning less than 2 hectares) form 86% of India’s agricultural workforce.
- Organic farming is gaining policy focus, but farmers face: Higher production costs. Longer transition periods (3 years to get organic certification). Market volatility due to inconsistent demand.
- Longer transition periods (3 years to get organic certification).
- MSP for organic crops should not overshadow broader MSP reforms: The panel rightly pointed out that organic MSP should not dilute the larger demand for MSP based on the Swaminathan formula (C2 + 50%).
Challenges of India’s Farmers Producer Organisations (FPOs)
- The government’s scheme to create 10,000 FPOs, launched in 2020 with a ₹6,865 crore allocation, has met its target.
- Including previously formed FPOs, the total count exceeds 44,400, with three million farmers involved, 40% of whom are women.
- Improved Bargaining Power: Farmers gain better deals for inputs and marketing through bulk procurement and sales.
- Financial Constraints FPOs struggle to secure credit as financial institutions perceive them as high-risk due to poor asset bases. Limited ability to raise equity due to the small financial capacity of members (mostly small or landless farmers).
Parliamentary Panel’s Recommendations on Crop Insurance & Residue Management
- Coverage for farmers with land holdings of up to 2 hectares (similar to PMJAY health insurance model).
- Financial Incentives for Farmers ₹100 per quintal of paddy to be provided as compensation for collection and disposal of crop residue. Payment via Direct Benefit Transfer (DBT), ensuring transparency and efficiency. Additional to Minimum Support Price (MSP).
- ₹100 per quintal of paddy to be provided as compensation for collection and disposal of crop residue.
- Coverage Expansion Include damages caused by stray animals in crop loss coverage under PMFBY. Rationale: Farmers face frequent crop destruction from stray animals, leading to financial losses.
India’s Warmest February and the Threat to Wheat Production
- February 2025 recorded as India’s warmest February in 124 years.
- March 2025 is also forecasted to experience above-normal temperatures and more frequent heat waves.
- Government wheat procurement target for 2025-2026 rabi marketing season: 30 million tonnes.
- 2024-2025 procurement was 26.6 million tonnes, below the target of 34.15 million tonnes.
Government Initiatives to Promote Organic Farming
- Since 2015–16, 59.74 lakh hectares have been covered under organic farming.
- State-wise details available in official annexure till 2023–2024.
- PGS-India Certification Under Ministry of Agriculture & Farmers Welfare, Involves farmer participatory assessment and verification.
- Under Ministry of Agriculture & Farmers Welfare,
| Scheme | Total Assistance (3 years) | Direct Benefit Transfer (DBT) | Other Support Areas | Max. Eligible Area |
|---|---|---|---|---|
| PKVY | ₹31,500/ha | ₹15,000/ha for organic inputs | - ₹4,500/ha for marketing, branding, packaging, value addition - ₹3,000/ha for certification & residue analysis - ₹9,000/ha for training & capacity building | 2 hectares |
| MOVCDNER | ₹46,500/ha | ₹15,000/ha (within ₹32,500/ha input support) | - Support for creating FPOs - Training, certification, and capacity building assistance of ₹10,000/ha over 3 years | 2 hectares |
Per Drop More Crop (PDMC)
- Launched: 2015–16
- Scheme evolution: 2015–16 to 2021–22: Implemented under Pradhan Mantri Krishi Sinchayee Yojana (PMKSY). Since 2022–23: Implemented under Pradhan Mantri Rashtriya Krishi Vikas Yojana (PMRKVY).
- 2015–16 to 2021–22: Implemented under Pradhan Mantri Krishi Sinchayee Yojana (PMKSY).
- Since 2022–23: Implemented under Pradhan Mantri Rashtriya Krishi Vikas Yojana (PMRKVY).
| Type of Irrigation | Area Covered (lakh hectares) |
|---|---|
| Drip Irrigation | 46.37 |
| Sprinkler Irrigation | 50.60 |
| Total | 96.97 lakh hectares |
National Mission on Edible Oils – Oilseeds (NMEO-OS)
- Creation of 600 Value Chain Clusters across India.
- Coverage of more than 10 lakh hectares annually through these clusters.
- Establishment of Seed Hubs: 34 Oilseeds Seed Hub Centres at ICAR institutes and State Agricultural Universities (SAUs). 150 Pulses Seed Hub Centres for distribution and availability of quality seeds to farmers.
- 34 Oilseeds Seed Hub Centres at ICAR institutes and State Agricultural Universities (SAUs).
Farmers’ Distress Index (FDI)
- A pilot study titled “Agrarian Distress and PM Fasal Bima Yojana: An Analysis of Rainfed Agriculture” was conducted for Telangana and Andhra Pradesh during 2020–21 and 2021–22.
- Systemic nationwide assessment of Farmers’ Distress Index (FDI) is not yet available.
- Developed as a multidimensional tool to: Forewarn stakeholders of impending farm distress. Provide policy support for addressing distress severity. Identify distressed areas and enable timely preventive actions.
- Forewarn stakeholders of impending farm distress.
Women in Agribusiness
- Women constitute 64.4 per cent of India's agricultural workforce but only 6-10 per cent are employed in top agri and agri-related companies, according to a new report released
- Women in Agriculture Workforce Women form 64.4% of India’s agricultural workforce. Only 6-10% are employed in top agri and agri-related companies.
- Women form 64.4% of India’s agricultural workforce.
- Only 6-10% are employed in top agri and agri-related companies.
Current status of GM crops in India
- Right now, Bt cotton is the only genetically modified crop allowed to be grown in the country. GM mustard got conditional approval in 2022, but it hasn’t been rolled out yet because of legal challenges.
Supreme Court developments
- The Supreme Court will begin hearing the GM mustard case from April 15, 2025.
Government and policy efforts
- According to a DBT report, India’s bio-economy is worth about $165.7 billion.
- The government’s BioE3 policy aims to use biotechnology in agriculture, medicine, and industry.
- Bio-agriculture makes up a small part of this — around $13.5 billion.
- The main drivers in this area are GM crops like Bt cotton and new precision agriculture techniques.
Parliamentary Panel Urges Increased Fertilizer Budget and Expansion of Nano Fertilizer Production
- The Parliamentary Standing Committee on Chemicals and Fertilizers, chaired by Trinamool Congress MP Kirti Azad, has made several significant recommendations in its recent report on the Demands for Grants for 2025-26:
- It expressed concern over the 7.38% budget cut made by the Ministry of Finance, reducing the department’s projected outlay from ₹1,84,704.63 crore to ₹1,71,082.44 crore.
- Underutilisation of Funds in 2024-25: 20% under indigenous phosphorus and potassium (PK) fertilizers. 12% under imported PK fertilizers. 14.76% under indigenous urea. 59.57% under Market Development Assistance (MDA). The committee called for better planning and full utilisation of allocated funds.
- Field trials showed notable crop yield improvements when using nano urea, with peas showing up to 14.82% improvement and sugarcane the lowest at 4%.
PDRL Launches Ag++ Flight Controller for Agri-Drones
- Future Plans: PDRL plans to file five more patents in the next two quarters, reinforcing its commitment to technological advancement.
- PDRL plans to file five more patents in the next two quarters, reinforcing its commitment to technological advancement.
- These developments are expected to significantly benefit farmers and agribusinesses across India.
- Ag++ is integrated with AeroGCS GREEN, PDRL’s software platform that currently supports: Over 5,000 agriculture drones More than 800,000 drone flights
Lulu Group Launches Global Agricultural Production Initiative in Pollachi
- Objective: To directly support local farmers and produce high-quality vegetables and fruits aligned with international standards.
- Lulu Group has launched a global agricultural production initiative in Pollachi to promote sustainable farming and empower local farmers.
- Land and Cultivation: Seed planting began on 160 acres at Ganapathi Palayam, with cultivation starting on 50 acres in the initial phase. Objective: To directly support local farmers and produce high-quality vegetables and fruits aligned with international standards.
- Seed planting began on 160 acres at Ganapathi Palayam, with cultivation starting on 50 acres in the initial phase.
Impact of Rainfall Variability on Indian Agriculture
- In the current financial year: Kharif food grain production: up by 7.9% Rabi food grain production: up by 6%
- Kharif food grain production: up by 7.9%
- Rabi food grain production: up by 6%
- Extreme weather events are becoming frequent: 2024 saw 322 extreme weather days, affecting 4.07 million hectares of crop area. Heatwaves and floods exceeded 250 days last year.
Digital Crop Survey (DCS) and Agri Stack
- Agri Stack, developed by the Ministry of Agriculture and Farmers Welfare, complies with: The Digital Personal Data Protection Act, 2023 Other relevant IT laws in India
- The Digital Personal Data Protection Act, 2023
- The State Farmer Registry under the Digital Agriculture Mission includes: All landholding farmers, including women farmers. Tenant and lessee farmers, onboarded as per state-specific policies.
- Full control for farmers on how and with whom their data is shared.
Government’s Push for Pulse Procurement & Self-Sufficiency
- Procurement Plan: 100% of State production of tur (arhar), urad (black gram), and masoor (red lentil) to be procured under the Price Support Scheme (PSS) for 2024-25. The commitment extends till 2028-29 to ensure self-sufficiency in pulses.
- 100% of State production of tur (arhar), urad (black gram), and masoor (red lentil) to be procured under the Price Support Scheme (PSS) for 2024-25.
- As of March 25, 2024: 2.46 lakh metric tonnes of tur (arhar) procured. 1,71,569 farmers benefitted. Prices of tur in Uttar Pradesh are above MSP, indicating strong market demand.
- PM-Asha Yojana extended till 2025-26 to ensure continued MSP-based procurement of pulses and oilseeds.
Nutrient-Based Subsidy (NBS) for Kharif 2025-26
- DAP subsidy raised from ₹25,411 per tonne to ₹27,800 per tonne for Kharif 2025.
- ₹37,216 crore allocated for the first half of FY26 (H1FY26).
- 41% increase in per kg subsidy on phosphorus (P) compared to Rabi FY25.
- Total fertilizer subsidy for FY25 revised to ₹1.91 trillion, up 14% from the budget estimate of ₹1.68 trillion.
| Nutrient | Kharif FY25 | Rabi FY25 | Kharif FY26 | % Change YoY (Kharif FY25 vs. FY26) | % Change (Rabi FY25 vs. Kharif FY26) |
|---|---|---|---|---|---|
| Nitrogen (N) | 47.02 | 43.02 | 43.02 | -8.51% | 0.00% |
| Phosphorus (P) | 28.72 | 30.8 | 43.6 | 51.81% | 41.56% |
| Potassium (K) | 2.38 | 2.38 | 2.38 | 0.00% | 0.00% |
| Sulphur (S) | 1.89 | 1.76 | 2.61 | 38.10% | 48.30% |
Awards · 1
Sahitya Akademi Awards 2024
- Each awardee received a plaque, a shawl, and ₹1 lakh.
- The Sahitya Akademi Awards 2024 were conferred on 23 distinguished writers at a ceremony during the ongoing “Sahityotsav: Festival of Letters”. The annual awards, recognizing excellence in Indian literature across various genres, were announced in December 2023.
Agriculturte · 1
India’s Palm Oil Push: Economic and Strategic Benefits
- India aims to expand oil palm cultivation to 10 lakh hectares by 2025-26 under the National Mission on Edible Oils – Oil Palm (NMEO-OP).
- A 3-year study in Maharashtra’s South Konkan region (IJCMAS) revealed: Banana intercropping: ₹55,833/ha Pineapple: ₹27,500/ha Elephant foot yam: ₹61,950/ha
- Banana intercropping: ₹55,833/ha
- Pineapple: ₹27,500/ha
Science & Tech · 2
Quantum Computing, Majorana Particles, and the Neutrino Mystery
- Findings (Feb 27, 2024, Physical Review Letters): No evidence of 0vßß was observed. A Mo-100 nucleus would take at least 10²⁴ years to decay via 0vßß. Estimated neutrino mass: less than 0.22-0.65 billionths of a proton.
- Microsoft announced the Majorana 1 quantum chip, aiming to solve industrial-scale problems in years, not decades.
- A Mo-100 nucleus would take at least 10²⁴ years to decay via 0vßß.
- These elusive particles are the second-most abundant in the universe, produced in: The Big Bang Radioactive decay Supernovae and cosmic ray interactions Nuclear fusion in stars (e.g., the Sun)
Bedmap3
- Bedmap3 provides a more detailed and accurate view of Antarctica’s subglacial landscape, revealing increased ice vulnerability and enhancing our understanding of climate change effects on sea-level rise.
- Bedmap3 is the most comprehensive dataset of Antarctica’s subglacial landscape, extending the previous Bedmap2.
- It incorporates 84 new aero-geophysical surveys from 15 data sources, adding 52 million more data points and 1.9 million line-km of measurements.
- Significant improvements in understanding major mountain ranges, deep interiors of East Antarctica, West Antarctic coastlines, and the Antarctic Peninsula.
Swipe for all 5 courses →
You are writing NABARD Grade A in 2026 NABARD Grade A 2026 Mentorship & Test Series
The whole thing — ARD, ESI, descriptive, mocks, mentors.
544 lessons 18 free to try
₹3,500
₹6,000 42% off
Enrol now
Try 18 lessons free
You are targeting RBI Grade B RBI Grade B Mentorship 2026
Phase 1 and Phase 2 together, with descriptive marked by hand.
576 lessons 41 free to try
₹2,999
₹6,000 50% off
Enrol now
Try 41 lessons free
You have studied — you need practice NABARD Test Series Phase I 2026
Phase I test series only. No lectures, just papers and analysis.
48 lessons 2 free to try
₹1,499
₹2,500 40% off
Enrol now
Try 2 lessons free
Your descriptive paper is the weak one NABARD English Descriptive 2026
Essay and précis, written and rewritten until it scores.
18 lessons
₹1,499
₹3,000 50% off
Enrol now
You are starting early for 2027 NABARD Foundation & Advanced Programme 2027
Foundation first, advanced later. A year, planned.
18 lessons 2 free to try
₹3,999
₹6,999 43% off
Enrol now
Try 2 lessons free
Clarity 4 Sure · c4scourses.in · +91 87086 52887 · compiled 25 September 2026