August 2025 — exam-ready facts
Every day of the month in one file. Enter your details once — the download opens right away.
We already have your details, so no form: tap to open.
Download the August 2025 revision sheet PDFFree live session
NABARD Grade A 2026: what the 2025 cut-offs changed, and the 90-day plan
The 2025 cycle was the toughest on record at every stage. This session reads those numbers properly and turns them into a week-by-week plan for Phase 1.
Today · 7:30 PM IST · 75 minutes · free
August 2025 at a glance
24 daily compilations, 387 items across 6 topics — Facts To Remember weighed the most. Read the charts first: they tell you where this month's questions will come from.
24 daily compilations | 387 items covered | 6 topics | 12 data tables |
Items by topic | Items per day Darker = a heavier day. Two-day posts are split across their days. |
7.75% Launched: July 1, 2020 (replacing the 7.75% Savings (Taxable) Bonds, 2018). RBI Floating Rate Savings Bond (FRSB) · 17 & 18 August 2025 | ₹19,744 crore National Green Hydrogen Mission (2023) with an outlay of ₹19,744 crore. India’s Green Hydrogen Potential: FICCI–EY Joint Report · 22 August 2025 |
3% Economic Burden: 2–3% of India’s GDP lost annually (Global Nutrition Report, 2021). The State of Food Security and Nutrition in the World 2025 Report · 19 August 2025 | ₹11 lakh Insurance market to grow from ₹11 lakh crore (2024) to ₹25 lakh crore (2030). Insurance Brokers Association of India (IBAI) Report on Insurance in India · 1 August 2025 |
₹2,000 crore The Union Cabinet has approved a new Central Sector Scheme titled “Grant-in-Aid to NCDC”, with a total outlay of ₹2,0… Cabinet Approves “Grant-in-Aid to National Cooperative Development Corporation (NCDC)” Scheme · 1 August 2025 | ₹1,000 crore A transaction exceeding ₹1,000 crore or 10% of annual consolidated turnover, whichever is lower, is currently classif… SEBI Proposes Turnover-Based Framework for Related Party Transactions (RPTs) · 5 August 2025 |
₹10 On August 19, 2025, Tata AIA Life Insurance Co Ltd launched the Momentum 50 Index Fund, with its New Fund Offer (NFO)… Tata AIA Launches Momentum 50 Index Fund · 19 August 2025 | ₹10,000 crore Initial Allocation (FY 2025–26): ₹10,000 crore Urban Challenge Fund (UCF) · 20 August 2025 |
₹2 lakh ₹2 lakh accidental insurance cover under Pradhan Mantri Suraksha Bima Yojana (PMSBY). Pradhan Mantri Jan-Dhan Yojana (PMJDY) · 24 & 25 August 2025 | ₹12,000 ₹12,000 annually (FY 2025–26) per selected student. NHAI Launches ‘Project Aarohan’ · 28 August 2025 |
₹7,332 crore The Union Cabinet, chaired by Prime Minister Narendra Modi, approved the extension and revamp of the Prime Minister S… Centre Extends PM SVANidhi Scheme · 28 August 2025 | ₹122 crore NICB was placed under RBI moratorium in February 2025 following governance failures and a ₹122 crore fraud by senior … RBI Approves Merger of New India Co-operative Bank with Saraswat Co-operative Bank · 3 & 4 August 2025 |
 Scheme to knowNational Agricultural Insurance Scheme (NAIS): 1999 Crop Insurance Scheme, Coverage, Premium, MNAIS and the Shift to PMFBYThe National Agricultural Insurance Scheme (NAIS), also called Rashtriya Krishi Bima Yojana, was India's main crop…
 Free sheet · Static GKCountries & Their Leaders 2026Who leads which country in 2026, with all 17 changes marked. Get the article and the PDF free on WhatsApp.Get it free on WhatsApp →
National Affairs · 88
India Justice Report 2025
- Established: Statutory body under the Legal Services Authorities Act, 1987
- Legal Aid Defence Counsel (LADC) Scheme (2022): Institutional legal defence for accused persons in 610 districts.
- Offers legal aid to SCs, STs, women, children, disabled persons, poor individuals, and prisoners under Section 12.
- Institutional legal defence for accused persons in 610 districts.
| Issue | Details |
|---|---|
| Budget Constraints | Legal aid accounts for <1% of the justice budget; funds fell to ₹169 crore (2022–23) from ₹207 crore (2017–18). |
| Fund Underutilisation | Utilisation rate dropped from 75% to 59%, hampering service delivery. |
| Decline in PLV Workforce | 38% drop in Para-Legal Volunteers between 2019–24; poor honorarium payments in many States. |
| Rural Inaccessibility | Just 1 legal aid clinic per 163 villages; per capita legal aid spending as low as ₹2. |
| Service Quality Gap | Widespread perception that legal aid quality is inferior to private counsel. |
| Centralised Fund Control | State Legal Services Authorities need central clearance for hiring and logistics, delaying implementation. |
Indian Navy Inducts Indigenous Stealth Frigate Himgiri under Project-17A
- First Commissioned Ship: INS Nilgiri (January 2024).
- Distribution: 4 frigates by MDL, Mumbai. 3 frigates by GRSE, Kolkata.
- 3 frigates by GRSE, Kolkata.
- Total Project Cost: ₹45,000 crore.
Mangrove Restoration Initiatives Across States
- Gujarat – MISHTI Scheme Front-runner: Over 19,000 ha restored in two years, surpassing national targets.
- Tamil Nadu – Green Tamil Nadu Mission: Mangrove cover doubled from 4,500 ha to 9,000 ha (2021–24). Canal desiltation and Avicennia seed planting in Muthupettai Estuary (115 ha).
- Maharashtra – Thane Creek Project: ₹10.3 crore budget to plant 3.75 lakh saplings and remove 150 tonnes of plastic in 3 years. Women-led workforce ensures sustainability and employment.
- ₹10.3 crore budget to plant 3.75 lakh saplings and remove 150 tonnes of plastic in 3 years.
Kavach 4.0
- Aims to commission Kavach 4.0 on major national routes within 6 years.
- Development and Approval Developed under Atmanirbhar Bharat vision. Approved by RDSO in July 2024. First operationalized in South Central Railway (2018). Kavach 4.0 approved in May 2025 for trains up to 160 km/h.
- First operationalized in South Central Railway (2018).
- Requires high-end hardware like RFID tags (every 1 km), telecom towers, and OFC connectivity.
Apna Ghar Initiative
- The Ministry of Petroleum and Natural Gas has launched a national-level initiative titled ‘Apna Ghar’ in 2025, designed to provide dignified resting facilities for truck drivers across highways in India.
- What It Is: A resting infrastructure scheme for long-haul truck drivers to promote health, hygiene, and well-being.
- A resting infrastructure scheme for long-haul truck drivers to promote health, hygiene, and well-being.
- Launch Year: 2025
ISRO Identifies Cause of PSLV-C61/EOS-09 Mission Failure
- The Indian Space Research Organisation (ISRO) has concluded its investigation into the PSLV-C61/EOS-09 mission failure that occurred on May 18, 2025. ISRO Chairman V. Narayanan confirmed that the Failure Analysis Committee has pinpointed the cause.
- Mission Objective: To place EOS-09, an Earth Observation Satellite, into a sun-synchronous polar orbit.
- Launch Vehicle: PSLV-C61, launched from Satish Dhawan Space Centre, Sriharikota.
- Launch Outcome: Lift-off and performance were normal until the second stage; an anomaly in the third stage led to mission failure.
ISRO to Launch U.S.-Developed BlueBird Satellite Aboard LVM3
- Significance Marks another key India–U.S. space collaboration, following the successful launch of the NISAR satellite on July 30, 2025. Highlights India's role as a trusted launch partner for global heavy payloads.
- Marks another key India–U.S. space collaboration, following the successful launch of the NISAR satellite on July 30, 2025.
- Launch Details Satellite: BlueBird (Block 2) Developer: AST SpaceMobile (USA) Launch Vehicle: LVM3 (formerly GSLV Mk III) Launch Site: Satish Dhawan Space Centre, Sriharikota
- Satellite: BlueBird (Block 2)
Govt Expands PM SVANidhi Scheme
- Expanded Coverage: The revamped scheme will cover 50 lakh more beneficiaries, in addition to the already existing street vendors.
- The revamped scheme will cover 50 lakh more beneficiaries, in addition to the already existing street vendors.
- Enhanced Loan Amounts: First loan: Increased from ₹10,000 to ₹15,000 Second loan: Increased from ₹20,000 to ₹25,000 Third loan: Unchanged at ₹50,000 All loans continue to carry an interest subsidy of 7%.
- First loan: Increased from ₹10,000 to ₹15,000
LVM3 Rocket with Semi-Cryogenic Engine
- Rocket Upgrade: The LVM3 (formerly GSLV Mk III), India’s most powerful rocket, will be upgraded with a semi-cryogenic engine stage, replacing the current L110 liquid propellant stage.
- The LVM3 (formerly GSLV Mk III), India’s most powerful rocket, will be upgraded with a semi-cryogenic engine stage, replacing the current L110 liquid propellant stage.
- Propellant Details: The new stage will use refined kerosene (RP-1) and liquid oxygen (LOX), a shift from the traditional hypergolic propellants.
- The new stage will use refined kerosene (RP-1) and liquid oxygen (LOX), a shift from the traditional hypergolic propellants.
National Child Survey to Develop Child Index Under Mission Vatsalya
- To create a secure, centralized, and tech-enabled system for monitoring and managing child protection efforts across India, improving coordination among various stakeholders and ensuring real-time data-driven decision-making.
- Addresses a major statistical gap in understanding vulnerable children’s conditions.
- Mission Vatsalya is the core focus of the survey.
- The ultimate goal is to develop a Child Index to guide welfare policies.
India to Launch Climate Finance Taxonomy
- This taxonomy is aligned with India’s obligations under the Paris Agreement and was first announced in the Union Budget 2024 by Finance Minister Nirmala Sitharaman.
- Alignment with National Targets: Fully integrated with India’s net-zero by 2070 goal and the Viksit Bharat 2047 development vision
- India is set to launch its first comprehensive Climate Finance Taxonomy in August 2025, providing clear definitions for investments that qualify as climate-aligned. The move aims to mobilize both domestic and international capital towards clean energy, adaptation, and achieving India’s net-zero targets.
- Offers investors and financial institutions clarity and confidence about what qualifies as green finance
Matri Van Initiative
- Alignment with National Campaigns Integrated with Ek Ped Maa Ke Naam, Mission LiFE, and Van Mahotsav 2025.
- Integrated with Ek Ped Maa Ke Naam, Mission LiFE, and Van Mahotsav 2025.
- A 750-acre theme-based urban forest project being developed in the Aravalli Hills, Gurugram (Haryana), under the Union Ministry of Environment.
- Promotion of community-led plantation, biodiversity conservation, and creation of urban green lungs.
India Electric Mobility Index (IEMI) 2024
- NITI Aayog has launched the India Electric Mobility Index (IEMI) 2024, India’s first national-level benchmarking tool to assess the performance of States and UTs in transitioning to electric mobility.
- To align sub-national actions with India’s net-zero target by 2070.
- IEMI evaluates performance on 16 indicators under 3 major pillars:
- A composite index developed by NITI Aayog to score all States/UTs on a 0–100 scale based on their progress in EV adoption, infrastructure development, and innovation ecosystems.
PAN 2.0 Project
- The Income Tax Department has awarded LTIMindtree Ltd the contract for upgrading India’s PAN and TAN management infrastructure under the PAN 2.0 Project, a significant leap in digitizing public tax services. The project was approved by the Cabinet Committee on Economic Affairs (CCEA) in November 2024 and aligns with the Digital India mission.
- Permanent Account Number (PAN) – PAN (Permanent Account Number) is a 10-character alphanumeric identifier issued by the Income Tax Department of India to individuals, companies, and other entities. It is essential for tracking financial transactions and ensuring tax compliance under the Income Tax Act, 1961.
- Tax Deduction and Collection Account Number (TAN) – TAN (Tax Deduction and Collection Account Number) is a 10-digit alphanumeric number issued by the Income Tax Department of India to entities responsible for deducting or collecting tax at source (TDS/TCS) under the Income Tax Act, 1961.
- Seamless interoperability with other government systems, positioning PAN as a universal digital identifier
Global Artificial Intelligence (AI) City Index 2025
- Bengaluru has been ranked 26th globally in the Global AI City Index 2025, making it the top-ranked city in India for AI research, innovation, and data centre development.
- About Global AI City Index 2025
- Objective: To benchmark global cities on their AI ecosystem strength including R&D, investments, infrastructure, and real-world applications.
- Bengaluru: Ranked 26th globally, India’s #1 AI city Strong AI R&D network, vibrant startup ecosystem, and expanding data centre capacity
Cloudburst
- Climate Change: Warmer air holds more water vapor. For every 1°C temperature rise, the atmosphere retains 7% more moisture, increasing the likelihood of intense short-duration rainfall events.
- A cloudburst is an extremely intense rainfall event over a small area within a short duration. As per the India Meteorological Department (IMD), it is defined as rainfall exceeding 100 mm per hour across an area of 20–30 sq km. However, a 2023 study by IIT Jammu and the National Institute of Hydrology (NIH) redefined this as rainfall of 100–250 mm/hour concentrated in just 1 sq km, making it one of the most hyper-local and destructive meteorological phenomena.
- Fragile Ecosystems: High-altitude settlements (1,000–2,000m) are ecologically sensitive and structurally unprepared for such events.
- High Cost of Modern Tech: AI-based early warning systems and high-resolution radars remain underfunded.
Moldova Becomes 107th Member of International Solar Alliance (ISA)
- Founded: Joint initiative of India and France at COP-21 (2015).
- Headquarters: Gurugram, India.
- Objective: Promote affordable, reliable, and sustainable solar energy worldwide, especially in:
Ayurveda Aahara Preparations
- Regulatory Framework: Governed by the Food Safety and Standards (Ayurveda Aahara) Regulations, 2022.
- Ayurveda Aahara refers to food products prepared in accordance with Ayurvedic principles emphasizing balance, seasonal alignment, natural ingredients, and therapeutic herbs.
- Objective: To integrate Ayurvedic dietary wisdom with contemporary nutritional standards, promoting preventive health and sustainable lifestyles.
BrahMos Supersonic Cruise Missile
- Speed: Supersonic (Mach 2.8–3.0) throughout its trajectory.
- Range: ~290 km (with extended versions under development).
- What is Supersonic? (Mach 1 to Mach 5)
- Named after the Brahmaputra (India) and Moskva (Russia) rivers.
Carriage of Goods by Sea Bill, 2025
- Repeal of 1925 Act: Eliminates outdated provisions rooted in colonial law.
- Modernisation of Maritime Law: Replaces the 1925 Act with a contemporary legal framework.
- Originated from the Hague Rules (1924) and revised by the Visby Protocol (1968) and SDR Protocol (1979).
- Parliamentary Oversight: Ensures executive decisions on international conventions are subject to legislative review.
Strategic Interventions for Green Hydrogen Transition (SIGHT) Scheme
- India has achieved a record-low Green Ammonia price of ₹55.75/kg in the first SECI auction under Mode-2A of the SIGHT Scheme, marking a milestone in India’s clean energy transition.
- ₹17,490 crore out of ₹19,744 crore (total NGHM budget) allocated to SIGHT.
- Create domestic demand across sectors like fertilizer, shipping, steel, and refining.
- Covers production incentives, infrastructure, and offtake support.
| Mode | Description |
|---|---|
| Mode 1 | Incentive awarded to lowest incentive seeker (reverse auction model). |
| Mode 2A | Fixed incentive for Green Ammonia procurement via demand aggregation. |
| Mode 2B | Fixed incentive for Green Hydrogen procurement via demand aggregation. |
Merchant Shipping Bill, 2024
- Repeals the outdated Merchant Shipping Act, 1958, reducing complexity—from 561 sections to 16 parts and 325 clauses.
- Grants statutory powers for pollution control, inspection, wreck removal, and effective emergency response—critical for India's 95% trade reliance on shipping.
- Introduces statutory obligations aligned with the Maritime Labour Convention (MLC, 2006).
- Adopts provisions from Nairobi Wreck Removal (2007), Salvage Convention (1989), and Bunker Oil Convention.
Biochar
- In India, with abundant agricultural waste, the technical potential could reach 100–150 Mt CO₂ per year by 2050.
- Biochar can store carbon for hundreds to thousands of years.
- According to the IPCC, biochar has the potential to sequester up to 2.6 gigatonnes of CO₂ annually globally.
- India generates over 500 million tonnes of crop residues annually.
India Releases Joint Doctrines for Cyberspace and Amphibious Operations
- Hybrid Warfare Preparedness: Counters combined cyber, sea, and land threats.
- Features: Tri-service integration. Rapid mobilisation from sea to shore. Flexible mission profiles (combat to HADR). Strategic reach over islands and coasts. Maritime–land operational linkage.
- Flexible mission profiles (combat to HADR).
Kartavya Bhavan-03 under Central Vista Redevelopment
- Purpose: Consolidates offices of over 50 Union ministries (spread across Delhi) into centralised, modern buildings.
- Objective: Improve administrative efficiency. Reduce rental and maintenance costs. Integrate sustainable infrastructure and digital work systems.
Election Commission of India (ECI)
- Initially a single-member body, but became a multi-member body after the Election Commissioner Amendment Act, 1989.
- Appointed by the President of India under the CEC and Other ECs (Appointment, Conditions of Service and Term of Office) Act, 2023.
- Article 326 – Elections based on adult suffrage (18 years and above).
- Article 329 – Bar on judicial interference in electoral matters.
Pradhan Mantri Ujjwala Yojana (PMUY)
- Government approved continuation of ₹300 per LPG cylinder subsidy for PMUY beneficiaries in FY 2025–26.
- ₹300 Subsidy per 14.2 kg Cylinder – Proportional for 5 kg cylinders, max 9 refills/year.
- Launch: May 2016, Ballia, Uttar Pradesh.
- Identified via SECC 2011 data.
PM E-Drive Subsidy Scheme
- Launched on 1 October 2024, replacing the Electric Mobility Promotion Scheme (EMPS-2024).
- Launch & Administration: Launched on 1 October 2024, replacing the Electric Mobility Promotion Scheme (EMPS-2024). Administered by the Ministry of Heavy Industries.
- Budget Allocation: Total outlay: ₹10,900 crore. Demand incentives for EVs: ₹3,679 crore. E-buses, charging infrastructure, and testing facilities: ₹7,171 crore.
- Total outlay: ₹10,900 crore.
Khelo India ASMITA Football League 2025-26
- Launch: Initiated in 2025–26 with the inaugural football league held in Jalgaon.
- Initiated in 2025–26 with the inaugural football league held in Jalgaon.
- Administering Ministry and Partners: Ministry of Youth Affairs and Sports, supported by the Sports Authority of India (SAI), All India Football Federation (AIFF), and Western India Football Association (WIFA).
- Ministry of Youth Affairs and Sports, supported by the Sports Authority of India (SAI), All India Football Federation (AIFF), and Western India Football Association (WIFA).
India to Launch 6,500 kg U.S. Communication Satellite After NISAR Mission
- Supports data speeds up to 12 Mbps, enabling clear voice calls, fast data, and video communication for users.
- Following the successful launch of the NISAR satellite on July 30, 2025, the Indian Space Research Organisation (ISRO) is preparing to launch a 6,500 kg U.S.-built communication satellite, Block-2 BlueBird, in the coming months. This mission underscores India's growing capabilities in handling large-scale international payloads.
- International Collaboration: Strengthens Indo-U.S. cooperation in space exploration and technology. Builds on the success of the previous NISAR mission, showcasing strong bilateral partnership.
- Builds on the success of the previous NISAR mission, showcasing strong bilateral partnership.
Revised Income Tax Bill, 2025
- Corporate & MSME Relief ₹80 million deduction for inter-corporate dividends restored. MSME definition aligned with the MSME Act for uniformity across laws.
- ₹80 million deduction for inter-corporate dividends restored.
- Finance Minister Nirmala Sitharaman tabled the Revised Income Tax Bill, 2025 in the Lok Sabha, incorporating most of the 566 recommendations from the Parliamentary Select Committee. The Bill aims to replace the six-decade-old Income Tax Act, 1961.
- Single ‘Tax Year’ Concept Replaces “Previous Year” and “Assessment Year” with a single term Tax Year to simplify understanding and compliance.
Jal Jeevan Mission
- The Jal Jeevan Mission (JJM) has achieved a significant milestone with rural tap water coverage reaching 81% in 2025, up from 17% in 2019, benefiting over 15.68 crore households.
- Launch: August 2019 by the Government of India.
- Objective: Provide Functional Household Tap Connections (FHTCs) to every rural household.
- Key Features: Safe, adequate, and regular potable water supply. Use of Aadhaar-linked monitoring, geo-tagged assets, IoT-based sensors, and third-party inspections for transparency.
India Semiconductor Mission (ISM)
- Launched: 2021
- Technologies: Glass interposers, silicon bridges, 3D Heterogeneous Integration (3DHI) modules.
- The Union Cabinet, chaired by PM Narendra Modi, has approved four new semiconductor manufacturing projects under the India Semiconductor Mission (ISM). These will involve a cumulative investment of ₹4,600 crore, generate 2,034 skilled jobs, and boost India's electronics manufacturing ecosystem.
- Focus: India’s first commercial Silicon Carbide (SiC) compound semiconductor fab.
Mines and Minerals (Development and Regulation) Amendment Bill 2025
- Funding boost: Contribution from mining leaseholders increased from 2% → 3% of royalty payable.
- Deep-seated minerals (below 200m): Up to 10% extension.
- Composite licences: Up to 30% extension.
- Earlier: Only up to 50% of minerals from captive mines could be sold.
Indian Ports Bill, 2025
- Lok Sabha passed the Indian Ports Bill, 2025, replacing the Indian Ports Act, 1908. Aims to modernise port rules, improve trade efficiency, and promote green and safe port practices.
- Support public-private partnerships (PPP) and foreign investments.
State Health Regulatory Excellence Index Launched (SHRESTH)
- Manufacturing States: 27 indicators under 5 themes – Human Resources, Infrastructure, Licensing, Surveillance, Responsiveness.
- Distribution States/UTs: 23 indicators under the same themes.
- Objectives Benchmark state drug regulatory systems. Target improvements in human resources, infrastructure, and digitisation. Enhance public trust in medicines made and distributed in India.
- Evaluation Criteria Manufacturing States: 27 indicators under 5 themes – Human Resources, Infrastructure, Licensing, Surveillance, Responsiveness. Distribution States/UTs: 23 indicators under the same themes. Monthly: States submit data to CDSCO → scored → feedback loop.
Export Promotion Mission
- The Government of India is set to launch a ₹2,250 crore Export Promotion Mission aimed at safeguarding Indian industries from global trade shocks, including recent US tariff hikes on Indian goods.
- Announced in the Union Budget 2025 on 1st February 2025
- Developed in response to high tariffs affecting sectors such as textiles, chemicals, leather, and footwear
- Enhance the competitiveness of MSMEs and e-commerce exporters
India’s First Private EO Satellite Constellation under PPP Model
- What It Is: A landmark space project deploying 12 advanced EO satellites built and operated by the private sector in collaboration with the government
- Consortium Members: Piersight Space, Satsure Analytics India, Dhruva Space
- Constellation Size: 12 state-of-the-art EO satellites
- PPP Model: First of its kind under IN-SPACe’s private sector promotion framework
National Sports Governance Bill & National Anti-Doping (Amendment) Bill
- Other Bodies: National Sports Federations (NSF) and Regional Sports Federations (RSF)
- National Sports Board (NSB): Can recognize any sports organization as a National Sports Body Chairperson and members appointed by the Central Government
- Chairperson and members appointed by the Central Government
- Oversight of Elections: Central government to set up a panel of electoral officers to supervise elections of national sports bodies
Mission Sudarshan Chakra
- On India’s 79th Independence Day (15th August 2025), the Prime Minister announced the launch of Mission Sudarshan Chakra, a landmark defence initiative to safeguard India’s strategic, civilian, and religious sites from potential enemy attacks.
- Long-Term Plan: Gradual expansion and upgradation of the system till 2035.
- Inspired by the mythological Sudarshan Chakra of Lord Krishna, blending cultural ethos with modern defence technology.
- What it is? A national security mission to build an advanced, multi-layered shield protecting vital installations across India. Inspired by the mythological Sudarshan Chakra of Lord Krishna, blending cultural ethos with modern defence technology. Nodal Ministry: Ministry of Defence.
National Deep Water Exploration Mission
- Large-Scale Bidding: Opening over 1 million sq km of erstwhile ‘No-Go’ areas for exploration.
- On the occasion of the 79th Independence Day, the Prime Minister of India announced the launch of the National Deep Water Exploration Mission to accelerate the discovery of offshore oil and gas reserves. The initiative will focus on areas such as the Andaman Sea and deep waters off the Andhra coast, with the goal of achieving energy self-reliance.
- Public-Private Collaboration: Encouraging both domestic and global players to invest.
- What it is: A flagship energy security initiative to explore untapped oil and gas reserves beneath India’s seabed. Designed to operate in mission mode for accelerated offshore exploration.
Next-Generation GST Reform
- What It Is? A complete restructuring of the GST framework. Replaces the current multi-slab system with a simplified two-slab regime (5% & 18%), plus a special 40% rate for select goods.
- Replaces the current multi-slab system with a simplified two-slab regime (5% & 18%), plus a special 40% rate for select goods.
- Two Core Rates: 5% → Merit goods & essential items. 18% → Standard goods & services.
- 5% → Merit goods & essential items.
Discovery of New Palm Species: Phoenix roxburghii
- Features: Height: 12–16 metres Tall solitary trunk Larger leaves and leaflets Musty-scented staminate flowers Large obovoid orange-yellow fruits
- Height: 12–16 metres
- Musty-scented staminate flowers
Sakura Science Programme 2025
- Launched: 2014 by Japan.
- India’s Participation: Joined in 2016; continues to be an active participant.
- A group of 34 Indian students has been flagged off to Japan to participate in the Sakura Science Programme 2025, a flagship youth exchange initiative aimed at promoting scientific curiosity and cross-cultural learning.
- Direct exposure to universities, research centres, and scientific institutions.
The State of Food Security and Nutrition in the World 2025 Report
- Economic Burden: 2–3% of India’s GDP lost annually (Global Nutrition Report, 2021).
- The UN Food and Agriculture Organization (FAO) released its State of Food Security and Nutrition in the World 2025 Report, showing global undernourishment at 8.2% (673 million people). India has been a decisive contributor to this decline.
- India’s Progress: Prevalence of undernourishment reduced from 13% (2020–22) to 12% (2022–24), meaning 30 million fewer hungry people.
- Global Picture: Undernourishment down from 9.4% in 2020 to 8.2% in 2025.
Impeachment Motion Against Chief Election Commissioner (CEC)
- The CEC is appointed under Article 324 of the Indian Constitution.
- Initiation: Motion can be introduced in either House of Parliament, supported by at least 50 MPs.
- Voting in Parliament: Motion must be passed by a two-thirds majority of members present and voting in both Houses.
- Presidential Action: Once approved by Parliament, the President orders removal (no discretion).
India to Land Astronaut on the Moon by 2040
- 2027 – Gaganyaan Mission: India’s first human spaceflight with astronauts in low Earth orbit.
- India’s proposed crewed lunar mission by 2040 is a long-term national vision.
- 2026 – Vyommitra Mission: Uncrewed mission with humanoid robot Vyommitra to test systems.
- Human Landing: An Indian astronaut to step on the Moon by 2040.
Ethanol-Blended Petrol (E20)
- Indian scenario differs: Most pre-2020 vehicles not designed for flex-fuel.
- Brazil uses E27 petrol after decades of phased policy (since 1975).
- India had set a target in 2021 to achieve 20% ethanol blending in petrol (E20) by 2025. Vehicles modified for E20 compatibility started rolling out from April 2025. While aimed at reducing carbon emissions and oil import dependency, the move has raised concerns among vehicle owners about mileage, corrosion, and higher maintenance costs.
- From food grains & lignocellulosic material after conversion into fermentable sugars.
Governor’s Assent to Bills
- Governor has no discretion under Article 200; must act on aid & advice of Council of Ministers.
- Article 200: Governor’s powers on assent – assent, withhold, or reserve for President.
- Article 201: President’s veto on reserved bills.
- Article 142: SC’s plenary power to ensure complete justice.
| Scenario | Maximum Time Allowed |
|---|---|
| Withhold assent or reserve for President (with CoM’s advice) | 1 Month |
| Withhold assent without CoM’s advice (returning bill) | 3 Months |
| Bill re-passed by Assembly (2nd time) | 1 Month |
Saltwater Crocodile
- Wildlife Protection Act, 1972 (India): Schedule I
- The largest of 23 extant crocodilian species (includes true crocodiles, alligators, caimans).
- Also called Estuarine Crocodile, commonly found in brackish waters of estuaries.
“One Nation, One Election” Bill
- Indirect President’s Rule Risk: The clause may extend powers beyond Article 356, enabling the Union Government to indirectly assume control of States.
- Clause 5 of Article 82A: Grants the Election Commission (EC) “unfettered discretion” to postpone Assembly elections, which may be struck down under Article 14 (equality before law) for arbitrariness.
- Insertion of a new Article 82A.
- Amendments to Articles 83 and 172 relating to Lok Sabha and State Assembly terms.
Govt Drafts Bill to Ban Online Real-Money Gaming in India
- The Union Government has finalised a draft legislation to ban all forms of online real-money gaming (RMG) in India. The Promotion and Regulation of Online Gaming Bill, 2025 is scheduled to be introduced in the Lok Sabha.
- Online RMG refers to games where players stake real money with the potential to win monetary rewards.
- Aimed at addressing rising gaming addiction among youth, which has led to mental health issues and financial distress.
- Seeks to safeguard consumers from exploitation while providing clarity on permissible gaming formats.
Cloudburst Disasters in India
- Cloudbursts are intense rainfall events defined as precipitation exceeding 100 mm per hour over ~30 sq. km.
- In 2025, cloudbursts, flash floods, and landslides have wreaked havoc across Northeast India, Uttarakhand, Himachal Pradesh, and most recently, Jammu and Kashmir. Over 60 lives were lost in J&K in less than a week, underscoring gaps in India’s climate preparedness and early-warning systems.
- Gaps in Climate Information: Cloudbursts occur in small tracts often without rainfall gauges. IMD lacks dense weather-monitoring networks needed for hyper-local forecasts.
- Cloudbursts occur in small tracts often without rainfall gauges.
Promotion and Regulation of Online Gaming Bill, 2025
- Investigation Powers: Search, seizure, and arrest without warrant under Bharatiya Nagarik Suraksha Sanhita, 2023.
- IT Act, 2000 & Rules (2021, amended 2023): Mandatory registration of permissible games, blocking illegal platforms.
- IGST Act, 2017: Offshore platforms required to register & pay taxes.
- Consumer Protection Act, 2019: Prohibits misleading ads.
India Successfully Test-Fires Agni-5 Ballistic Missile
- India successfully test-fired its intermediate-range ballistic missile Agni-5 from the Integrated Test Range (ITR), Chandipur, Odisha on August 20, 2025.
- Range: Can strike targets up to 5,000 km, covering entire Asia and parts of Europe.
130ᵗʰ Constitution Amendment Bill
- Legal Gap Addressed: Amends Section 45 of the Government of Union Territories Act, 1963, which currently lacks provisions for removal on such grounds.
- Automatic Removal: PM, CMs, and Ministers to lose office on the 31st day of arrest for offences carrying a minimum punishment of 5 years.
- Union Home Minister Amit Shah introduced the Constitution (130ᵗʰ Amendment) Bill, 2025, in the Lok Sabha, proposing the removal of the Prime Minister, Chief Ministers, and Ministers if arrested for serious criminal charges for 30 consecutive days. The move sparked massive protests from the Opposition.
- Aims to raise ethical standards in politics by preventing individuals from holding office while facing serious criminal charges.
Silicon Valley of Solar
- Launched: 30 November 2015, Paris, France
- Founded: 2015 by India and France at the Paris COP21.
- Centres of Excellence: Located in 17 countries (names undisclosed). Focus on testing, lab training, and start-up incubation in universities modeled on IITs. Number may increase to 50 in future.
- Located in 17 countries (names undisclosed).
India’s Green Hydrogen Potential: FICCI–EY Joint Report
- National Green Hydrogen Mission (2023) with an outlay of ₹19,744 crore.
- A joint report by FICCI and EY emphasizes that India could capture 10% of the global green hydrogen market by overcoming cost and infrastructure barriers, aligning with its net-zero ambitions.
- Pilot Projects: ₹208 crore allocated; 37 hydrogen-powered vehicles deployed; 9 refuelling stations to be operational in 18–24 months.
- Target: 5 MMT annual production by 2030, requiring 125 GW renewable capacity.
India’s Need for a National Space Law
- Key Principles of Outer Space Treaty (OST), 1967
- State Responsibility: Nations are liable for activities of both state and private operators.
- Legal Clarity: Provides a stable, transparent framework for private players; reduces red tape.
- Private Sector Growth & FDI: Clear rules on IP rights, insurance, and foreign investment will boost startups and attract global investors.
18th International Earth Science Olympiad (IESO) 2025
- Individual Winners: Rayansh Gupta: 1 Gold, 1 Silver, and Special GYM Reporter Award. Bains Charuvrat: 2 Silver, 1 Bronze. Apam Nidhi Pandey: 1 Silver. Pryanshi Ghanghas: 1 Bronze.
- Host (2025): Jining, China.
- Total Medals: 7 medals + 1 Special Award.
- Rayansh Gupta: 1 Gold, 1 Silver, and Special GYM Reporter Award.
India’s Draft Climate Finance Taxonomy
- Aim: Mobilize climate finance from public and private sources. Prevent greenwashing by distinguishing genuine green projects. Provide clarity and confidence for investors.
- The Ministry of Finance released India’s draft Climate Finance Taxonomy for public consultation in May 2025.
- What is it? A classification framework defining climate-aligned sectors, technologies, and practices. A “living document”, evolving with India’s priorities and global climate goals. Prepared by the Ministry of Finance, Department of Economic Affairs.
- Prepared by the Ministry of Finance, Department of Economic Affairs.
Adi Karmayogi Abhiyan
- Vision 2030: Co-create development plans for 1 lakh tribal villages, detailing action strategies and investments.
- Scheme Saturation: Ensure 100% coverage of government schemes in tribal areas.
- Leadership Network: Build a cadre of 20 lakh change leaders across 550 districts in 30 States/UTs.
- Adi Sewa Kendra: Community-government collaboration centers in tribal villages for issue resolution, youth mentoring, and scheme implementation.
NITI Aayog’s Roadmap for Homestays
- Economic Potential: Projects an 11% CAGR in India’s homestay market (₹4,722 crore in 2024), positioning homestays as a solution to India’s hotel room shortage (2 lakh rooms gap).
- Ease of Operations: Calls for a single-window digital platform for homestay registration, renewal, and compliance, with a strict 30-day approval timeline.
- Digital & Market Integration: Encourages greater collaboration with online travel aggregators to improve visibility, credibility, and revenue for hosts.
- Tourism-Led Livelihoods: Homestays offer culturally immersive experiences, fostering rural incomes and empowering micro-entrepreneurs.
Kerala Becomes India’s First Fully Digitally Literate State
- In August 2025, Kerala Chief Minister declared the state as India’s first fully digitally literate state, marking the successful completion of Phase I of the Digi Kerala Project.
- Digital Literacy: Ability of individuals and communities to understand and use digital technologies for meaningful actions in daily life.
- Digitally Literate Household: At least one member aged 5+ can operate a computer and use the internet.
- Democratic Participation: Empowers citizens to actively engage in governance, RTI, and policy feedback.
Integrated Air Defence Weapon System (IADWS)
- Aims to build an indigenous Iron Dome-like air defence system by 2035.
- Launched on the 79th Independence Day.
- Mission Sudarshan Chakra:
- Focused on protecting critical civil and defence infrastructure with rapid, precise counterstrike capabilities.
ISRO Successfully Conducts First Integrated Air Drop Test (IADT-1)
- The Indian Space Research Organisation (ISRO) has successfully completed the Integrated Air Drop Test (IADT-01) to validate the parachute-based recovery system of the Gaganyaan crew module, a crucial milestone in India’s first human spaceflight programme.
- Conducted using a dummy crew capsule (~5 tonnes) dropped from an Indian Air Force Chinook helicopter.
Global Warming Curtailing Workers’ Productivity: WHO-WMO Report
- Economic Impact: Productivity drops 2–3% for every degree above 20°C, making this not just a health issue but also an economic challenge.
- Rising Heat Levels: 2024 was the hottest year on record; daytime temperatures of 40°C–50°C are becoming more frequent.
- A joint report by the World Health Organization (WHO) and the World Meteorological Organization (WMO) warns that rising global temperatures are increasingly harming workers’ health and reducing productivity worldwide.
- Health Impact: Workers face higher risks of heatstroke, dehydration, kidney dysfunction, and other heat-related illnesses.
Sundarbans Tiger Reserve (STR) Becomes India’s 2nd-Largest Tiger Reserve
- Declared a Tiger Reserve in 1973 under the first phase of Project Tiger.
- Designated a Biosphere Reserve in 1989.
- Recognized by UNESCO in 2001.
- Globally important for the mangrove–tiger ecosystem, combining rich biodiversity with unique mangrove habitats.
Lunar Module Launch Vehicle (LMLV)
- Aimed at enabling crewed lunar missions by 2040 and supporting deep space exploration.
- The Indian Space Research Organisation (ISRO) has announced the development of its heaviest rocket ever the Lunar Module Launch Vehicle (LMLV), which is expected to be ready by 2035.
- Carry large payloads to the Moon (~27 tonnes).
- Supports India’s long-term deep space exploration vision (Moon, Mars, beyond).
Women’s Employment Rate in India
- The Labour Ministry reported that women’s employment rate in India nearly doubled from 22% in 2017-18 to 40.3% in 2023-24, while female unemployment fell from 5.6% to 3.2%.
- Refers to Women’s Workforce Participation Rate (WPR) as per Periodic Labour Force Survey (PLFS).
Indian Navy Commissions INS Udaygiri & INS Himgiri
- Key Features: Weapons: LRSAM, 8 BrahMos supersonic cruise missiles, Barak-8, torpedoes, rocket launchers, 127 mm main gun, AK-630 guns. Systems: Modern radars, Humsa-NG sonar, Shakti Electronic Warfare suite.
- Weapons: LRSAM, 8 BrahMos supersonic cruise missiles, Barak-8, torpedoes, rocket launchers, 127 mm main gun, AK-630 guns.
- Type: First Project 17A Nilgiri-class frigate built at GRSE, Kolkata.
- Key Features: Weapons: LRSAM, BrahMos, Barak-8, torpedoes, rocket launchers, 127 mm gun, AK-630 guns. Design: Integrated stealth with reduced radar cross-section.
Space-Based Solar Power (SBSP)
- Scale of Operations: A single satellite might span 1 km across; ground receivers would be 10 times larger. Hundreds of launches required, compared to 40 for the International Space Station.
- A single satellite might span 1 km across; ground receivers would be 10 times larger.
- The International Energy Agency’s ‘Renewables 2024’ report highlights that solar power will drive 80% of global renewable energy growth by 2030. However, ground-based solar faces limitations such as intermittency, weather dependency, and high land requirements. A recent study by King’s College London suggests that space-based solar power (SBSP) could potentially supply 80% of Europe’s renewable energy needs by 2050.
- Timeline: Cost-effectiveness may only be feasible post-2050, pending major technological breakthroughs.
Early Childhood Care and Education (ECCE) Reforms
- 5+1 weekly plan under Aadharshila (National ECCE Curriculum): 30 minutes free play daily. Structured activities for language, creativity, motor skills, and social-emotional learning. Outdoor play and value-based interactions post-lunch.
- Focuses on early brain development, caregiving practices, and stimulation-based learning during the critical first 1,000 days of life.
- Developed by the National Council of Educational Research and Training (NCERT) under the National Education Policy (NEP) 2020.
- Developed by the National Council of Educational Research and Training (NCERT) under the National Education Policy (NEP) 2020.
National Cooperative Policy, 2025
- Aims to make cooperatives key drivers of social equity, rural empowerment, and economic sustainability.
- Ensure participation of 50 crore members across India.
- Triple the cooperative sector’s share in GDP by 2034.
- Build a self-reliant, employment-rich cooperative ecosystem by 2047.
Adi Karmayogi Initiative
- Village Vision 2030: Each of the 1 lakh target villages will prepare a “Village Vision” document to set development goals. These will be displayed as public murals to act as aspirational blueprints.
- Infrastructure Support: Establishment of 1 lakh Adi Seva Kendras as single-window service centres for welfare scheme access to ensure 100% saturation.
- Establishment of 1 lakh Adi Seva Kendras as single-window service centres for welfare scheme access to ensure 100% saturation.
- The Ministry of Tribal Affairs has launched the Adi Karmayogi initiative to build a cadre of 20 lakh “change leaders” in tribal villages under the Dharti Aba Janjatiya Gram Utkarsh Abhiyaan for last-mile delivery of welfare schemes.
SAMARTH Panchayat Portal
- 42% of Gram Panchayats collect less than ₹1 lakh annually.
- Facilitates generation of tax and non-tax demands, maintenance of tax registers, online tracking of revenue, and asset management.
- Current Challenges in Panchayat Financing: 42% of Gram Panchayats collect less than ₹1 lakh annually. 11 states/UTs still lack OSR rules (including Uttar Pradesh, Bihar, Jharkhand, Arunachal Pradesh, Nagaland, Sikkim, Manipur, and UTs like Ladakh, Lakshadweep). No centralized database currently exists for granular Panchayat revenue data.
- 11 states/UTs still lack OSR rules (including Uttar Pradesh, Bihar, Jharkhand, Arunachal Pradesh, Nagaland, Sikkim, Manipur, and UTs like Ladakh, Lakshadweep).
National Designated Authority (NDA) for Carbon Emissions Trading
- Composition: 21-member committee. Headed by Secretary, Environment Ministry. Includes officials from External Affairs, Steel, Renewable Energy Ministries, and NITI Aayog.
- The Ministry of Environment, Forest and Climate Change has set up a National Designated Authority (NDA) as mandated under Article 6 of the Paris Agreement (2015) to facilitate a carbon emissions trading mechanism.
- Approval at COP29: Article 6 operational rules were finalised at the 29th Climate COP in Baku, Azerbaijan (Nov 2024).
- 21-member committee.
NHAI Launches ‘Project Aarohan’
- Scholarship Support: ₹12,000 annually (FY 2025–26) per selected student. ₹50,000 each for 50 meritorious students pursuing postgraduate or higher studies.
- ₹12,000 annually (FY 2025–26) per selected student.
- Fund Allocation: ₹1 crore (July 2025 – March 2026).
- ₹50,000 each for 50 meritorious students pursuing postgraduate or higher studies.
Two Indian Startups Launch Satellites on SpaceX’s Falcon 9 Rocket
- First commercial resupply mission to ISS: October 8, 2012.
- First commercial crewed mission to orbit: 2020.
- First launch: June 4, 2010.
- Mission: The satellites were launched as part of SpaceX’s Transporter-12 mission from Cape Canaveral, Florida.
Centre Extends PM SVANidhi Scheme
- Launched on June 1, 2020 by the Ministry of Housing and Urban Affairs (MoHUA).
- The Union Cabinet, chaired by Prime Minister Narendra Modi, approved the extension and revamp of the Prime Minister Street Vendors AtmaNirbhar Nidhi (PM SVANidhi) scheme till March 31, 2030, with an outlay of ₹7,332 crore.
- Enhanced Loan Limits: 1st tranche increased from ₹10,000 to ₹15,000 2nd tranche increased from ₹20,000 to ₹25,000 3rd tranche remains ₹50,000
- 1st tranche increased from ₹10,000 to ₹15,000
India to Begin Testing Indigenous ‘Iron Dome’ Under Project Kusha
- Objective: Complete development by 2028 and induct the system by 2030.
- India will commence testing of new interceptor missiles in 2026 as part of Project Kusha, a key element of Mission Sudarshan Chakra (MSC) announced by Prime Minister Narendra Modi. The mission aims to provide a multi-layered air and missile defence shield for critical military and civilian assets by 2035.
- Interceptor Missiles Timeline: M1 Missile (150 km range) – Testing to begin in 2026. M2 Missile (250 km range) – Testing planned for 2027. M3 Missile (350 km range) – Testing scheduled for 2028.
- M1 Missile (150 km range) – Testing to begin in 2026.
BioE3 (Biotechnology for Economy, Environment, and Employment) Policy
- Expand India’s bioeconomy to $300 billion by 2030 (from $165.7 billion in 2024 and $10 billion in 2014).
- The Union Minister of Science and Technology, Dr. Jitendra Singh, launched the BioE3 Challenge for Youth and India’s first National Biofoundry Network, marking one year of the BioE3 (Biotechnology for Economy, Environment, and Employment) Policy.
- Creating large-scale employment opportunities in biotech-driven sectors.
- Strengthen global partnerships in biotechnology.
India Introduces First-Ever Guidelines for Animal Blood Transfusion and Blood Banks
- First-of-its-kind Guidelines: India has, for the first time, formalized a framework for safe animal blood transfusions and the creation of blood banks.
- Scope: The framework covers both companion animals (like dogs and cats) and large animals (such as cattle and equines).
Comprehensive Modular Survey (CMS) 2025
- The Comprehensive Modular Survey (CMS) 2025 on education revealed that 33% of school students in India take private coaching, indicating growing reliance on “shadow schooling”.
- National Average: 27% of students take private coaching.
- Urban vs Rural: Urban: 30.7% students. Rural: 25.5% students.
- Urban: 30.7% students.
Comprehensive Modular Survey: Education (CMS:E) 2025 by NSO
- Rural Areas Higher secondary: Only 58.9% of students enrolled in government schools (down from 68% in 2017-18). Primary: 66.5% (down from 73.7%). Middle: 69.3% (down from 76.1%). Secondary: 65% (down from 68%).
- Higher secondary: Only 58.9% of students enrolled in government schools (down from 68% in 2017-18).
- Urban Areas Higher secondary: 36.4% of students enrolled in government schools (down from 38.9% in 2017-18). Primary: 27.2% (down from 30.9%). Middle: 29.8% (down from 38%). Secondary: 35.8% (down from 38.9%).
- Higher secondary: 36.4% of students enrolled in government schools (down from 38.9% in 2017-18).
The National Annual Report and Index on Women’s Safety (NARI 2025)
- 40% of urban women feel “unsafe” or “not so safe” in their own cities.
- 60% reported feeling safe, largely during the day in schools and colleges (86%).
- The National Annual Report and Index on Women’s Safety (NARI 2025) has revealed that a significant proportion of women in urban India feel unsafe, highlighting gaps between lived experiences and official crime data.
- About NARI 2025 Report:
Samudrayaan Project
- What it is: India’s first manned deep-sea mission, approved in 2021.
- Aim: Explore the ocean up to 6,000 metres depth for resources, biodiversity, and climate studies.
- Two Indian aquanauts recently dived over 5,000 metres in the Atlantic Ocean aboard the French submersible Nautile. The mission was part of training for India’s upcoming Samudrayaan Project under the Deep Ocean Mission (DOM).
- Budget: ₹4,077 crore for five years.
DBT Biocare Programme
- Launched in 2011 by the Department of Biotechnology (DBT), Ministry of Science & Technology.
- Aim: To support unemployed women scientists in their early careers.
- Full Form: Biotechnology Career Advancement and Re-orientation Programme (BioCARe)
1. Launched on ________ by the Ministry of Housing and Urban Affairs (MoHUA).
2. ________: India’s first human spaceflight with astronauts in low Earth orbit.
3. National Green Hydrogen Mission (2023) with an ________.
4. Launched in ________ by the Department of Biotechnology (DBT), Ministry of Science & Technology.
5. Aims to commission Kavach 4.0 on major national routes within ________.
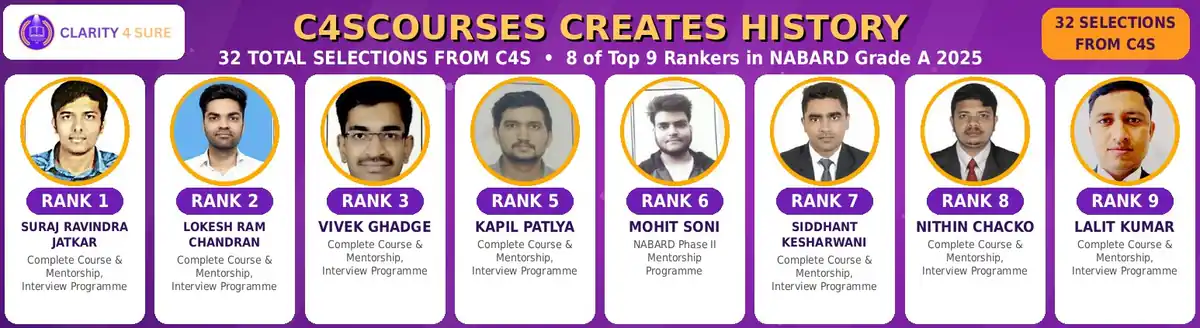
8 of the top 10 ranks in NABARD Grade A 2025 came from one classroom
Ranks 1, 2, 3, 5, 6, 7, 8 and 9 on the final list, and 32 selections in all, prepared with C4S Courses (Clarity 4 Sure). The same descriptive training and the same current affairs notes you are reading now.
- 1Suraj Ravindra JatkarRank 1
- 2Lokesh Ram ChandranRank 2
- 3Vivek GhadgeRank 3
- 5Kapil PatlyaRank 5
- 6Mohit SoniRank 6
- 7Siddhant KesharwaniRank 7
- 8Nithin ChackoRank 8
- 9Lalit KumarRank 9
Banking/Finance · 134
ICICI Bank to Begin Charging Payment Aggregators for UPI Transactions
- From August 1, 2025, ICICI Bank will start levying charges on payment aggregators (PAs) for processing Unified Payments Interface (UPI) transactions, becoming the latest major private bank to tap into this cost recovery mechanism.
- Peer-to-merchant (P2M) UPI volumes are rising sharply.
- ICICI joins Yes Bank and Axis Bank, which already levy similar charges on PAs.
- PAs act as intermediaries between the customer’s bank (debit side) and merchant’s bank (credit side).
Bank Credit Growth Slows Sharply in June 2025 – RBI Data
- According to the Reserve Bank of India (RBI), non-food bank credit growth slowed to 10.2% year-on-year (Y-o-Y) as of the fortnight ended June 27, 2025, down from 13.8% during the same period in 2024. The slowdown was driven by weaker demand across agriculture, services, retail, NBFCs, and industrial sectors.
- After a strong performance last year, banks are reporting a reduced pace of disbursement—likely due to high base effects and tightening liquidity in rural areas.
- One of the strongest performers in recent years, the services sector has also experienced a notable dip in credit offtake.
- The trade sector too has cooled off, with wholesalers and retailers showing lesser appetite for fresh credit amid subdued consumer demand.
Standing Committee on Finance Flags Gaps in PMIS and IBC
- Budget Allocation: ₹2,000 crore allocated in BE FY25; revised to ₹380 crore in RE FY25. Current funds sufficient for the pilot phase, but require dynamic reassessment for scaling.
- ₹2,000 crore allocated in BE FY25; revised to ₹380 crore in RE FY25.
- Ministry of Corporate Affairs agreed to initiate reforms and expand tribunals to improve case disposal speed.
- No support for living expenses hinders participation by candidates from remote or economically weak backgrounds.
Insurance Brokers Association of India (IBAI) Report on Insurance in India
- The Insurance Brokers Association of India (IBAI) released a comprehensive report titled "Leading the Path to Insurance for All: Broker of the Future", in collaboration with McKinsey & Company, to mark its 24th Foundation Day in Mumbai (August 2025).
- Insurance market to grow from ₹11 lakh crore (2024) to ₹25 lakh crore (2030).
- Retail Gross Written Premiums (GWP) expected to double to ₹21 lakh crore by 2030.
- Status: Statutory trade body under Section 25 of the Companies Act, 1956.
IRDAI Issues Master Circular to Raise Minimum Insurance Coverage Requirements
- Founded: 1999
- FY26: Insurers must collectively cover lives, dwellings, and vehicles in 25,000 designated Gram Panchayats. Each insurer must ensure 15% coverage in their allocated panchayats.
- FY27: Target increased to 50,000 Gram Panchayats. Insurers must achieve 25% coverage in earlier allocated areas and 10% in newly assigned panchayats.
- Insurers must ensure that 10% of the total insured lives are from the social sector in FY26, rising to 12% in FY27.
| Market Share | FY26 Increase | FY27 Increase |
|---|---|---|
| ≤ 2% | 12.5% | 13.75% |
| 2%–5% | 10% | 11% |
| 5%–10% | 7.5% | 8.25% |
| > 10% | 5% | 5.5% |
SEBI Proposes Changes in IPO Allocation Norms for Large Issues
- For IPOs above ₹5,000 crore, SEBI proposes: Retail investor quota to be reduced from 35% to 25%. Institutional quota (Qualified Institutional Buyers - QIBs) to be increased from 50% to 60%. A graded approach will be applied based on IPO size.
- Retail investor quota to be reduced from 35% to 25%.
- Institutional quota (Qualified Institutional Buyers - QIBs) to be increased from 50% to 60%.
- SEBI proposes to increase the number of permissible anchor investor allottees for allocations exceeding ₹250 crore. This will make participation easier for large FPIs managing multiple funds.
SEBI Plans Major Reforms for Mega IPOs
- Retail Quota to be Reduced: For IPOs above ₹5,000 crore, the retail investor reservation (applications below ₹2 lakh) may be reduced from 35% to 25%. This is in response to low retail participation in jumbo IPOs like Hyundai Motor India (₹27,859 crore issue).
- For IPOs above ₹5,000 crore, the retail investor reservation (applications below ₹2 lakh) may be reduced from 35% to 25%.
- This is in response to low retail participation in jumbo IPOs like Hyundai Motor India (₹27,859 crore issue).
- Increased Institutional Quota: The allocation for Qualified Institutional Buyers (QIBs) is proposed to be raised from 50% to 60%. Aims to enhance stability and pricing efficiency in large public issues.
RBI’s MuleHunter Platform to Tackle Bank Frauds Gains Traction
- Detects 90% true positives, significantly better than traditional systems with 80% false positives.
- MuleHunter Deployment: Already implemented by 5 banks: Canara Bank, PNB, BoI, BoB, and AU Small Finance Bank. Federal Bank to adopt it shortly. At least 15 more banks expected to onboard in the next 1–2 months.
- Already implemented by 5 banks: Canara Bank, PNB, BoI, BoB, and AU Small Finance Bank.
- At least 15 more banks expected to onboard in the next 1–2 months.
UPI’s ‘Free Payments’ Model Under Strain as ICICI Bank Imposes Charges on Payment Aggregators
- ICICI Bank has begun charging payment aggregators (PAs) for processing UPI transactions, raising concerns over the long-term viability of the zero-cost digital payments ecosystem.
- Banks handle backend infrastructure and transaction processing under UPI without charging users.
- Government insists UPI is a public good and must remain free for users and small merchants.
- Wider Industry Shift: Other banks like Axis Bank and Yes Bank reportedly also levy UPI processing charges on PAs. Indicates a broader pushback by banks against uncompensated costs of scale.
NPCI Introduces Revised UPI Rules
- Users can check their bank balance up to 50 times per day on each UPI app.
- Founded: 2008
- Autopayments (recurring debits) will be processed only during non-peak hours: Before 10:00 am Between 1:00 pm – 5:00 pm After 9:30 pm
- Users can check the status only 3 times, with a 90-second gap between checks.
MCX Relaunches Cardamom Futures Trading Contracts
- Tick Size (Minimum Price Movement): ₹1 per kg
- Relaunch Date: Trading resumes from Tuesday, July 29, 2025.
- Trading resumes from Tuesday, July 29, 2025.
- Reason for Previous Suspension: SEBI had discontinued cardamom futures in 2021 via regulatory circular.
Finance Ministry Notifies 0.1% Concessional Government Guarantee Fee for NaBFID
- Established in 2021 through an Act of Parliament.
- The Ministry of Finance has set a 0.1% concessional guarantee fee for the National Bank for Financing Infrastructure and Development (NaBFID) to enable access to low-cost foreign capital for infrastructure development.
- The 0.1% concessional fee applies to government guarantees for borrowings from: Multilateral development banks Sovereign wealth funds Other notified foreign financial institutions The fee is payable at the time of guarantee issuance and annually every April 1 thereafter.
- The fee is payable at the time of guarantee issuance and annually every April 1 thereafter.
Choice International Gets SEBI Approval to Launch Mutual Fund Business via Choice AMC
- Investor Accessibility: Passive products offer low-cost, diversified investment options ideal for retail participation.
- Initial Strategy: The AMC will adopt a phased rollout, beginning with passive investment products, such as: Index Funds Exchange Traded Funds (ETFs)
Quant Mutual Fund Becomes First AMC in India to Launch Specialized Investment Fund (SIF)
- Minimum Investment Threshold: ₹10 lakh per investor.
- If threshold falls below ₹10 lakh due to any transaction, all SIF units of the investor will be frozen for debit.
- Launch Timeline: The fund is expected to be launched in August 2025.
- First-of-its-Kind Approval: Quant MF will launch the QSIF Equity Long-Short Fund, India's first fund under the newly created SIF category.
RBI Approves Merger of New India Co-operative Bank with Saraswat Co-operative Bank
- NICB was placed under RBI moratorium in February 2025 following governance failures and a ₹122 crore fraud by senior officials, which resulted in frozen withdrawals and deposit restrictions
- The merger is effective from August 4, 2025, and all NICB branches will operate as Saraswat Bank branches from that day onward.
- Reason for the Merger NICB was placed under RBI moratorium in February 2025 following governance failures and a ₹122 crore fraud by senior officials, which resulted in frozen withdrawals and deposit restrictions Saraswat Bank voluntarily proposed to absorb NICB to safeguard investors’ interests and stabilize the bank’s operations.
- Saraswat Bank voluntarily proposed to absorb NICB to safeguard investors’ interests and stabilize the bank’s operations.
India Post Payments Bank Rolls Out Aadhaar-Based Face Authentication for Digital Banking
- Established: September 1, 2018
- Ownership: 100% Government of India
- Headquarters: New Delhi
- Network: ~1.65 lakh post offices (including ~1.4 lakh in rural areas) ~3 lakh postal employees acting as banking service agents
Phygital Banking in India
- Customer Experience: Offers 24/7 digital service with human support for complex needs.
- Airtel Payments Bank & India Post Payments Bank: Leverage mobile tech with doorstep services.
- Customer Relationship Managers (CRMs)
- Wider Reach: Merges branch and mobile access, aiding rural and senior users.
SEBI Proposes Turnover-Based Framework for Related Party Transactions (RPTs)
- Material RPT: A transaction exceeding ₹1,000 crore or 10% of annual consolidated turnover, whichever is lower, is currently classified as "material" and requires shareholder and audit committee approval.
- A transaction exceeding ₹1,000 crore or 10% of annual consolidated turnover, whichever is lower, is currently classified as "material" and requires shareholder and audit committee approval.
- Payment of managerial remuneration to directors.
- To safeguard the interests of minority shareholders.
| Company Turnover | Proposed RPT Materiality Threshold |
|---|---|
| Up to ₹20,000 crore | 10% of annual turnover |
| ₹20,001–₹40,000 crore | ₹2,000 crore + 5% of amount exceeding ₹20,000 crore |
| Above ₹40,000 crore | ₹3,000 crore + 2.5% of amount exceeding ₹40,000 crore OR ₹5,000 crore (whichever is lower) |
Irdai Imposes Penalty on Policybazaar for Regulatory Violations
- Biased Promotions IRDAI Web Aggregators Regulations, 2017: Prohibits ranking products as “top” without objective criteria.
- IRDAI Web Aggregators Regulations, 2017: Prohibits ranking products as “top” without objective criteria.
- Governance Conflicts IRDAI Guidelines, 2017: Prior approval required for Key Management Personnel (KMPs) holding directorships in other insurance entities.
- IRDAI Guidelines, 2017: Prior approval required for Key Management Personnel (KMPs) holding directorships in other insurance entities.
Bank of Baroda Unveils bob FxOne
- Bank of Baroda has launched “bob FxOne”, a digital foreign exchange platform, for its corporate and MSME customers.
- Real‑time forex and derivative trading: Live rates, instant deal confirmations, downloadable tickets, and a personalized dashboard with alerts
- One-Click Trade (1CT) and Request‑For‑Quote (RFQ) options enable streamlined execution of bookings across cash, tom, spot, forward, bills, and options
- Currency Conversion: Instantly convert one currency to another.
RBI Removes Prior Approval Requirement for Special Rupee Vostro Accounts (SRVAs)
- Introduced as part of the RBI’s 2022 framework for international trade settlement in INR.
- SRVAs are INR-denominated accounts held by overseas banks with Indian AD banks.
PFRDA Launches Modernized Website Under ‘PFRDA CONNECT’ Initiative
- Launched by: Shri S. Ramann, Chairperson, PFRDA
- Objective: Enhance transparency, accessibility, and efficiency in pension sector governance through digital transformation.
IDFC FIRST Bank and IndiGo Launch Dual Credit Card with Shared Limit
- IDFC FIRST Bank and IndiGo Airlines have jointly launched the IndiGo IDFC FIRST Dual Credit Card, featuring two cards (Mastercard and RuPay) under one shared credit limit.
- India’s first dual-network credit card combining Mastercard and RuPay
Promoting Financial Literacy and Borrower Protection in Rural India: Initiatives by NABARD and RBI
- Launched in 2017, CFLs use community-led and participatory methods for financial literacy.
- Loans to households with annual income ≤ ₹3 lakh are now classified as microfinance loans.
- Earlier restriction of 50% loan usage for income-generating purposes has been lifted.
- Monthly loan repayments are capped at 50% of household income.
RBI Holds Repo Rate at 5.5%
- Real Estate Weakness Housing sales fell 20% YoY in Q2 2025; buyer sentiment remains weak amid uncertainty.
- Housing sales fell 20% YoY in Q2 2025; buyer sentiment remains weak amid uncertainty.
- Low Inflation Inflation dropped to 2.1% in June 2025, but RBI avoided further cuts to prevent demand overheating.
- Inflation dropped to 2.1% in June 2025, but RBI avoided further cuts to prevent demand overheating.
RBI Panel Recommends Retaining WACR as Operating Target for Monetary Policy
- Why Shorter Tenors? Operations of up to 7 days offer greater flexibility to manage day-to-day liquidity pressures efficiently.
- Long-term VRR/VRRR: Used for durable liquidity adjustments with longer tenors (e.g., 1 month, 3 months).
- Used for durable liquidity adjustments with longer tenors (e.g., 1 month, 3 months).
- VRR/VRRR (Variable Rate Repo/Reverse Repo): Auctions where the interest rate is determined by market bids; used to inject (repo) or absorb (reverse repo) liquidity.
RBI Introduces SIP Facility for Treasury Bills via Retail Direct Platform
- Retail Direct Portal: Launched in November 2021. Allows retail participation in: Primary auctions of G-Secs, T-bills Secondary market trading of government securities. Investors can open a Retail Direct Gilt (RDG) account directly with the RBI.
- Launched in November 2021.
- Offers liquidity, capital safety, and returns better than bank savings accounts.
- The Reserve Bank of India (RBI) has launched a Systematic Investment Plan (SIP) facility for Treasury Bills (T-bills) under its Retail Direct scheme, marking a major expansion in direct access to government securities for retail investors.
RBI Revises Co-Lending Framework to Enhance Transparency and Risk Sharing
- All regulated entities (REs) must retain at least 10% of each loan on their own books.
- Originating lender may offer a first-loss guarantee up to 5% of the outstanding loan amount.
- Strengthen the co-lending partnership framework between banks and non-bank lenders.
- All loan disbursements and repayments must flow through an escrow account maintained with a bank.
RBI Unveils Three Consumer-Focused Schemes to Boost Financial Inclusion
- Significance: Supports 10-year milestone of Pradhan Mantri Jan Dhan Yojana (PMJDY) and promotes last-mile connectivity in banking.
- Platform: RBI’s Retail Direct portal, launched in 2021.
- Objective: To simplify KYC compliance for financially underserved sections.
- Objective: To relieve families of procedural burdens after the death of a bank account holder.
Axis Bank Launches ‘Lock FD’ Feature
- Axis Bank has launched a ‘Lock FD’ feature for safeguarding customers’ Fixed Deposits (FDs) from rising digital frauds by allowing them to restrict FD closures through digital means.
Tata AIA Launches 'Shubh Shakti'
- On August 6, 2025, Tata AIA Life Insurance launched “Shubh Shakti”, a term insurance plan exclusively designed for women. The initiative targets rising female workforce participation and the persistent gender gap in financial planning and insurance coverage in India.
Gro Digital Platforms and IDFC FIRST Bank Partner to Launch FASTag Services for Fleet Operators
- Gro Digital Platforms, a logistics services platform jointly promoted by Ashok Leyland and Hinduja Leyland Finance, has signed a Memorandum of Understanding (MoU) with IDFC FIRST Bank to launch FASTag services for fleet operators across India.
AU Small Finance Bank Gets RBI Nod to Become Universal Bank
- On 8 August 2025, the Reserve Bank of India (RBI) granted in-principle approval to AU Small Finance Bank (AU SFB) to transition into a universal bank. AU becomes the first SFB to receive such approval and the first universal bank approval in over 11 years. It currently commands about 40% market share among SFBs.
| Criterion | Requirement |
|---|---|
| Scheduled Status | Must have been in the RBI’s Scheduled Banks list for at least 5 years |
| Stock Listing | Shares must be listed on a recognised stock exchange |
| Net Worth | Minimum net worth of ₹1,000 crore |
| Financial Health – Profitability | Net profits in each of the last 2 Financial Years (FYs) |
| Financial Health – Asset Quality | G-NPA ≤ 3% and N-NPA ≤ 1% over the last 2 FYs |
| Promoter Requirements | No addition or change in promoters during the transition period |
| Portfolio Preference | Preference given to SFBs with diversified loan portfolios |
IDFC FIRST Bank Launches RemitFIRST2India Digital Remittance Platform
- Branch Network: 1,016 branches; digital-first approach with highly rated mobile app.
- Availability: For IDFC FIRST Bank NRI customers – direct transfer via Mobile Banking App without extra registration. For non-customers – quick, paperless onboarding via a dedicated web portal.
- For IDFC FIRST Bank NRI customers – direct transfer via Mobile Banking App without extra registration.
- Partnership: SingX (licensed by Monetary Authority of Singapore) for regulatory compliance and operational efficiency.
IFC Commits $150M to H-DREAM Fund for Green Affordable Housing
- Investment Details: IFC will act as an anchor investor with a USD 150 million commitment to H-CARE 3.
- Fund Objective: Promote affordable, green-certified housing projects in India, supporting low- and middle-income homebuyers.
- Economic Impact: Supports real estate developers with long-term funding for environmentally responsible affordable housing.
- Partnership: This is IFC’s third investment with HDFC Capital’s H-CARE platform, reinforcing a long-standing collaboration.
FSSAI and Bank of Baroda Collaborate to Enhance Digital Payments
- Partnership Objective: To integrate digital payment solutions for food business operators (FBOs) across India.
- Target Audience: Street vendors, small eateries, and micro food enterprises.
- Expected Benefits: Enhanced financial inclusion, transparency in transactions, and faster payment processing for small vendors.
- Implementation Plan: Nationwide roll-out through FSSAI’s regional offices and Bank of Baroda’s branch network.
DSP Mutual Fund Launches India's First Flexi-Cap Index Fund
- DSP Mutual Fund has introduced the DSP Nifty500 Flexicap Quality 30 Index Fund, marking it as India’s first-ever flexi-cap index fund. The fund is designed to offer a low-cost, rules-based investment strategy that adapts dynamically to market conditions.
- SEBI Regulation: Categorised under “Flexi Cap Fund” with the mandate to invest at least 65% in equities across all caps.
- Quality-Only Stock Selection: The fund tracks the Nifty500 Flexicap Quality 30 Index, comprising 30 fundamentally strong companies 10 each from large-cap, mid-cap, and small-cap segments, all equally weighted within each category.
- Index-Based: Tracks a specific benchmark index (e.g., Nifty 500, Nifty Flexi Cap Index) passively, ensuring low costs compared to actively managed flexi-cap funds.
Kotak Mahindra Bank Launches ‘Solitaire’ Programme
- Founded: 2003
- Merger: ING Vysya Bank merged with Kotak Mahindra Bank in 2015.
- Salaried individuals: Minimum relationship value of ₹75 lakh.
- Self-employed individuals: Minimum relationship value of ₹1 crore.
ICICI Bank Hikes Minimum Balance Requirement for New Savings Accounts
- Revised MAB Limits: Urban branches: ₹50,000 (previously ₹10,000) Semi-urban branches: ₹25,000 Rural branches: ₹10,000 (unchanged)
- Urban branches: ₹50,000 (previously ₹10,000)
- Semi-urban branches: ₹25,000
- Rural branches: ₹10,000 (unchanged)
LIC Enters Bond Forward Rate Agreements (FRA) Market
- Impact: Expected to increase demand for long-term government securities (30 years+), but may narrow forward spreads, affecting profitability of smaller market players.
- FRAs are primarily used by institutions like banks and insurers to hedge against fluctuations in interest rates.
| Aspect | Forward Rate Agreements (FRAs) | Bond Forwards |
|---|---|---|
| Nature of Contract | Agreement to lock in an interest rate on a notional amount for a future period. | Agreement to buy/sell a specific bond at a predetermined price on a future date. |
| Settlement | Settled in cash based on the difference between agreed rate and market rate. | Physical delivery of the bond at contract maturity (no cash settlement). |
| Underlying Asset | Interest rates (no actual bond or loan is exchanged). | Specific government bond or security. |
| Risk Mitigation | Hedge interest rate fluctuations without bond ownership. | Hedge interest rate risk with actual bond delivery, reducing procurement risk. |
| Market Usage | Commonly used by banks, insurers to hedge interest rate risk on liabilities or assets. | Used by insurers and investors to lock in bond prices and ensure delivery. |
| Settlement Risk | Requires sourcing bonds at settlement for hedging if needed, adding market risk. | Eliminates settlement risk as bond delivery is contractually guaranteed. |
| Regulatory Status in India | Allowed and widely used for interest rate risk management. | Recently permitted by RBI and IRDAI, expanding hedging tools. |
RBI Proposes Standardised Forms and 15-Day Settlement for Deceased Customers Claims
- If No Nominee: Banks will fix a threshold limit, with a minimum of ₹15 lakh, for simplified claim settlements. Claims up to threshold require bond of indemnity/surety and disclaimer/no objection letters from other legal heirs (if applicable).
- Banks will fix a threshold limit, with a minimum of ₹15 lakh, for simplified claim settlements.
- Objective To reduce inconvenience and undue hardship to claimants/legal heirs, and improve the efficiency and transparency of claim settlements post customer’s demise.
- The Reserve Bank of India (RBI) has issued a draft circular titled Reserve Bank of India (Settlement of Claims in respect of Deceased Customers of Banks) Directions, 2025 to standardise and simplify the process for settling claims on bank accounts and safe deposit lockers of deceased customers.
NSE & BSE Introduced new Standard Operating Procedure (SOP)
- The National Stock Exchange of India (NSE) and Bombay Stock Exchange (BSE) have introduced a new Standard Operating Procedure (SOP), effective from August 1, 2025, to expedite regulatory approvals for mergers and demergers involving listed companies. The Securities and Exchange Board of India (SEBI) has mandated this framework to bring predictability and speed to an otherwise lengthy process.
- Faster Processing: Applications with complete documents processed within 7 working days, down from 3-5 months earlier.
- Strict Timelines: Draft schemes to be filed within 15 days of board approval; only two opportunities to respond to exchange queries.
- Sequential Approvals: Exchanges issue NOC/observation letters to SEBI; post-SEBI approval, companies approach NCLT for final sanction.
SEBI Proposes Separate Category of Alternative Investment Fund (AIF) Schemes
- Category I: Funds investing in socially or economically desirable sectors (e.g., venture capital, SME funds, infrastructure).
- Category II: Funds employing diverse or complex strategies without leverage (e.g., private equity funds, debt funds).
- Category III: Funds employing diverse or complex trading strategies with leverage (e.g., hedge funds).
RBI Imposes Rs 75 Lakh Penalty on ICICI Bank for Regulatory Violations
- The Reserve Bank of India (RBI) levied a monetary penalty of Rs 75 lakh on ICICI Bank Limited for non-compliance with specific regulatory guidelines.
- Valuation of Properties: The bank failed to ensure property valuations were conducted by independent valuers for certain mortgage loans, violating RBI’s norms on empanelment of valuers.
- The bank failed to ensure property valuations were conducted by independent valuers for certain mortgage loans, violating RBI’s norms on empanelment of valuers.
- Opening and Maintenance of Current Accounts: ICICI Bank opened or maintained current accounts without adhering to RBI’s prescribed discipline and regulatory requirements.
Minimum Alternate Tax & Alternate Minimum Tax
- Applicability: Only for non-corporate taxpayers, including LLPs, partnerships, and individuals, who claim specified deductions under sections such as 10AA or Chapter VI-A.
- Objective: Ensures these taxpayers also contribute a minimum level of tax despite deductions.
- Current Rate: Around 15% of book profits plus surcharge & cess.
- Current Rate: Around 18.5% plus surcharge & cess.
SEBI Proposes FPI Reforms to Boost Investment and Ease Compliance
- Investment Limit: Resident Indian non-individual FMEs or their associates can contribute up to 10% of a retail scheme’s corpus.
- Resident Indian non-individual FMEs or their associates can contribute up to 10% of a retail scheme’s corpus.
- Longer Validity: KYC and registration review extended from 3–5 years to 10 years.
- Cap Removal: No 50% contribution cap for NRIs/OCIs/RIs in SWAGAT-FI entities.
Large Value Funds (LVFs)
- Minimum Investment Ticket Size: ₹70 crore per investor.
- Lower Entry Threshold Minimum investment cut from ₹70 crore → ₹25 crore per investor. Rationale: ₹70 crore was too high for many domestic institutions; ₹25 crore keeps sophistication but broadens access.
- Minimum investment cut from ₹70 crore → ₹25 crore per investor.
- Rationale: ₹70 crore was too high for many domestic institutions; ₹25 crore keeps sophistication but broadens access.
RBI Grants In-Principle Approval to Paytm Payments Services as Online Payment Aggregator
- Requires RBI authorisation under the Payment and Settlement Systems Act, 2007.
- Minimum net worth: ₹15 crore at the time of application. Must increase to ₹25 crore by the end of the third financial year.
- ₹15 crore at the time of application.
- Must increase to ₹25 crore by the end of the third financial year.
IBC Amendment Bill
- Introduced – 2016
- Nodal Ministry – Ministry of Corporate Affairs
- Cross-Border Insolvency – Creates rules for dealing with cases involving foreign creditors or overseas assets.
- Personal Guarantor Assets – Lets lenders take over personal guarantors’ assets during insolvency proceedings.
NPCI to Discontinue UPI ‘Pull’ Transactions from October 31, 2025
- Ownership: Owned by a consortium of major banks; promoted by Indian Banks’ Association (IBA) under the guidance of RBI and Payment and Settlement Systems Act, 2007.
- Established: 2008.
- Launched: April 2016 by NPCI.
- Type: Not-for-profit company under the Companies Act, 2013.
Parliament Passes New Income Tax Bill
- Parliament passed the new Income Tax Bill, replacing the six-decade-old Income Tax Act, 1961, aiming to simplify India’s direct tax law. The Rajya Sabha returned the legislation to the Lok Sabha with a voice vote, completing the parliamentary procedure.
- Related Taxation Laws (Amendment) Bill, 2025: Passed alongside the main bill. Key provisions: Tax exemption to public investment funds of Saudi Arabia and its subsidiaries. Tax exemption for partial withdrawal under Unified Pension Scheme. Revised definition of ‘income’ in block assessments during search/seizure cases.
- Simplified Tax Framework: Introduces the concept of a “tax year” replacing the financial year and assessment year to reduce confusion. Makes the law easier to read, understand, and implement.
- Makes the law easier to read, understand, and implement.
| Basis | Direct Tax | Indirect Tax |
|---|---|---|
| Who Pays | Paid directly by taxpayer to government | Paid indirectly via sellers/service providers |
| Burden Shift | Cannot be shifted | Can be shifted to another person |
| Examples | Income Tax, Corporate Tax | GST, Customs Duty |
| Nature | Progressive | Regressive |
| Collection | Direct from taxpayer | Collected by intermediaries and remitted to government |
RBI Allows ‘Vostro’ Accounts to Invest Surplus in Government Securities
- New Investment Permission Foreign investors can now invest entire surplus balances in central government securities. Aims to promote international trade settlement in INR.
- Foreign investors can now invest entire surplus balances in central government securities.
- Aims to promote international trade settlement in INR.
- What is a Vostro Account? An account held by a domestic bank on behalf of a foreign bank. Used for holding rupee-denominated balances arising from trade transactions between India and other countries.
Retail Inflation (Consumer Price Index – CPI)
- In July 2025, retail inflation in India dropped to 1.55% – the lowest in 8 years. This is well below the RBI’s target range of 2% to 6% and has now stayed under 4% for six months in a row. The main reason is the fall in food prices.
- Base Year: Currently 2012 (in India).
- Base Year: Currently 2012 (in India).
- Reverse Repo Rate: Makes banks keep more money with RBI, reducing market cash.
RBI Report on Framework for Responsible and Ethical Enablement of Artificial Intelligence (FREE-AI)
- Constituted as per RBI’s December 6, 2024 policy statement.
- Improved Customer Experience – Chatbots, voice assistants, personalized services.
- Fraud Prevention – Real-time anomaly detection and cybersecurity enhancement.
- Regulatory Gaps – No universal AI governance standards yet.
RBI’s Revised Co-Lending Guidelines to Boost NBFC Growth – Crisil
- Minimum Retention Requirement – REs must retain at least 10% of loans on their books, down from the 20% requirement for NBFCs earlier.
- Direct Lending Guarantee (DLG) – Originating REs can now provide DLG of up to 5% of loans across all lending forms, earlier limited to digital lending.
- Uniform Asset Classification – All co-lending partners must follow consistent classification for a given loan exposure, ensuring transparency and standard risk assessment.
Overseas Direct Investments (ODIs)
- The move comes amid a dramatic 96% fall in net foreign direct investment (FDI) in 2024-25, partly due to increased outward investment and repatriation by foreign investors.
- Since mid-2022, regulations allow companies more freedom to write off unviable overseas investments, prompting banks to adopt a cautious approach.
RBL Bank Partners with CAMSPay to Launch Digital Payment Gateway for Enterprises
- Partnership Role: RBL Bank will act as the merchant acquiring settlement service partner, while CAMSPay provides payment technology innovation.
- A Digital Payment Gateway is an online service that acts as a bridge between a merchant’s website/app and the bank/payment network to process electronic transactions securely.
SBI Launches Special Personal Loan Scheme for Agniveers
- State Bank of India (SBI) has introduced a special personal loan scheme for Agniveers serving under the Government’s Agnipath recruitment programme, launched on the occasion of India’s 79th Independence Day.
- Loan Amount – Up to ₹4 lakh for Agniveers with an SBI salary account.
- To provide financial support and convenience to Agniveers during and after their service, easing their transition to civilian life.
- Repayment Tenure – Matches the term of the Agnipath scheme for flexibility.
Payment Aggregator (PA) vs. Third-Party Payment Aggregator (TPA)
- Regulation: Must obtain RBI authorisation under the Payment and Settlement Systems Act, 2007 (PSS Act). Example: Razorpay, PayU, Cashfree, BillDesk.
- Must obtain RBI authorisation under the Payment and Settlement Systems Act, 2007 (PSS Act).
- An entity that facilitates e-commerce sites and merchants to accept payment instruments (credit cards, debit cards, UPI, wallets, etc.) from customers.
- Role: Collects funds from customers. Pools the money into an escrow/nodal account. Settles it to the respective merchants after a set time.
| Feature | Payment Aggregator (PA) | Third-Party PA (TPA) |
|---|---|---|
| Handles Funds? | Yes, collects & settles merchant payments | No, only provides tech platform |
| RBI Authorisation | Mandatory under PSS Act | Not required (but subject to IT/outsourcing norms) |
| Nodal/Escrow Account | Must maintain | Not applicable |
| Examples | Razorpay, PayU, BillDesk | Juspay (tech layer), Pine Labs (when acting only as API) |
Participating (Par) Products in Insurance
- Unlike non-par products (which offer fixed guaranteed returns but expose insurers to risk in low-rate environments) or ULIPs (where the policyholder bears full market risk), par products balance security with growth potential.
- Profit Sharing Policyholders share in the insurer’s distributable surplus, usually declared annually. Bonuses are not guaranteed and depend on the insurer’s financial performance.
- Policyholders share in the insurer’s distributable surplus, usually declared annually.
- Types of Bonuses Reversionary Bonus: Declared annually, added to the sum assured. Cash Bonus: Paid out immediately. Terminal Bonus: Paid at maturity or death.
Peer-to-Peer (P2P) Collect in Payments
- Peer-to-Peer (P2P) payments are digital money transfers between two individuals without involving cash or physical instruments.
- Transactions happen using mobile apps, UPI IDs, QR codes, phone numbers, or bank accounts.
- The National Payments Corporation of India (NPCI) has announced that it will discontinue the peer-to-peer (P2P) collect request feature on UPI starting October 1, 2025. The decision comes amid rising cases of fraud and misuse linked to this feature.
- Problem: Fraudsters increasingly misused this feature by tricking unsuspecting users into approving bogus payment requests.
Credit-to-Deposit Ratio Remains Below 80%: CareEdge Ratings
- According to CareEdge Ratings, the credit-to-deposit (CD) ratio in Indian banks remains below 80% as credit offtake continues to lag deposit growth.
- The Credit-to-Deposit (CD) Ratio shows the proportion of a bank’s deposits that have been lent out as credit.
- Measures how efficiently a bank is using its deposits.
RBI to Introduce Continuous Cheque Clearing System
- Cheques will be scanned, presented, and processed throughout business hours (10 AM – 4 PM).
- Funds to be released to customers immediately, max within 1 hour after settlement.
- Cheques are cleared in batches with a T+1 day cycle (up to 2 working days).
- Clearing time: reduced to a few hours within the same day.
SBI Life Launches “Smart Shield Plus” Term Insurance
- Increasing Cover: Sum assured increases annually by 5%, up to a maximum of 200%.
- Plan Options (3 Choices): Level Cover: Fixed sum assured throughout. Increasing Cover: Sum assured increases annually by 5%, up to a maximum of 200%. Level Cover with Future Proofing: Option to increase cover at key life stages (marriage, childbirth, etc.) without medical underwriting.
- Flexibility & Coverage: Whole-life protection (coverage up to age 100) and limited-term options. Multiple premium payment term options. Flexible payouts: lump sum, installments, or a combination.
- Whole-life protection (coverage up to age 100) and limited-term options.
Punjab & Sind Bank Launches ‘PSB Naari Shakti’ Savings Account
- Founded: 24 June 1908
- Headquarters: New Delhi, India
- Financial Benefits: Complimentary Platinum RuPay debit card for seamless digital transactions Exclusive savings account privileges tailored for women customers
- Exclusive savings account privileges tailored for women customers
S&P Global Upgrades India’s Sovereign Credit Rating to ‘BBB’
- Headquarters: New York City, USA
- S&P Global Ratings has upgraded India’s long-term unsolicited sovereign credit rating to ‘BBB’ from ‘BBB-’ after a gap of 18 years. The decision reflects India’s strong economic resilience, sustained fiscal consolidation, and a stable policy framework.
- Aim: To enhance corporate transparency and investor confidence by offering credible opinions on creditworthiness.
- Functions: Assigns public and private credit ratings Provides analytical reports across corporate, government, infrastructure, and insurance sectors Helps investors assess the ability of borrowers to meet financial commitments
NSIC Signs MoUs with Private Banks to Boost MSME Credit Facilitation
- Prime Minister’s Employment Generation Programme (PMEGP) Subsidy scheme for setting up new micro-enterprises. Subsidy: 15–35% of project cost depending on category and region. Implemented by KVIC (Khadi and Village Industries Commission).
- MUDRA Yojana (Pradhan Mantri MUDRA Yojana – PMMY) Loans up to ₹10 lakh under three categories: Shishu: up to ₹50,000 Kishore: ₹50,000 – ₹5 lakh Tarun: ₹5 – ₹10 lakh
- Self-Reliant India (SRI) Fund ₹50,000 crore equity infusion scheme to help MSMEs grow and expand.
- ₹50,000 crore equity infusion scheme to help MSMEs grow and expand.
RBI Floating Rate Savings Bond (FRSB)
- Launched: July 1, 2020 (replacing the 7.75% Savings (Taxable) Bonds, 2018).
- Current interest rate (as of July 1, 2025): 8.05% (7.70% NSC rate + 0.35%).
- The interest rate is linked to the prevailing National Savings Certificate (NSC) rate + 0.35%.
- 7 years fixed maturity.
B2B Fintechs Eye Retail Market Through TPAP
- B2B fintechs are technology-driven financial service providers that serve businesses (MSMEs, corporates, startups, banks, NBFCs, etc.) rather than individual consumers.
- Unlike B2C fintechs (like PhonePe or Paytm), B2B fintechs operate behind the scenes to power business transactions.
- Third-Party UPI Application Providers (TPAPs) are apps that offer Unified Payments Interface (UPI) services to users, but are not banks themselves.
- They provide the front-end app/platform while actual payment processing is done through sponsor banks (called Payment Service Providers – PSP banks) connected to NPCI’s UPI system.
SEBI Proposes Changes in Minimum Public Shareholding and Public Offer Norms
- Thresholds of post-issue market capitalisation revised to: ₹4,000 crore – ₹50,000 crore ₹50,000 crore – ₹1 lakh crore ₹1 lakh crore – ₹5 lakh crore Above ₹5 lakh crore
- ₹4,000 crore – ₹50,000 crore
- ₹50,000 crore – ₹1 lakh crore
- ₹1 lakh crore – ₹5 lakh crore
Sebi Proposes Stricter Norms for Sectoral & Thematic Indices in Derivatives
- Stock Weightage Cap: No single stock can have more than 20% weight in the index. Combined weight of the top 3 stocks capped at 45%. Remaining stocks must follow a descending order of weightage.
- No single stock can have more than 20% weight in the index.
- Combined weight of the top 3 stocks capped at 45%.
- Minimum Constituents: Each sectoral/thematic index must have at least 14 stocks.
Special Mention Accounts (SMA) and Non-Performing Asset (NPA)
- Objective: To provide relief to cash-strapped MSMEs affected by steep US tariffs, supply chain disruptions, and liquidity stress.
- Comparison: Agriculture sector already enjoys longer repayment moratoriums (180–360 days). MSMEs, with cyclic/seasonal cash flows, seek similar flexibility.
- SMA Relaxation: The government may also relax the timeline for Special Mention Accounts (SMA), which are early indicators of loan stress.
- Objective: Early warning system for banks and financial institutions to take corrective action.
Tata AIA Launches Momentum 50 Index Fund
- On August 19, 2025, Tata AIA Life Insurance Co Ltd launched the Momentum 50 Index Fund, with its New Fund Offer (NFO) priced at ₹10 per unit. The NFO will remain open until August 25, 2025.
- The Momentum 50 Index Fund tracks the BSE 500 Momentum 50 Customised Index, consisting of 50 high-momentum stocks from the BSE 500 universe.
- Portfolio: Invests in 50 high-momentum stocks selected from the BSE 500 universe, based on their recent strong performance.
- Unique Feature: Combines equity investment potential with life insurance protection for policyholders.
IRDAI Directs Insurers to Undertake QIS for Risk-Based Capital Framework
- The Insurance Regulatory and Development Authority of India (IRDAI) has directed insurance companies to conduct a Quantitative Impact Study (QIS 2) as part of the transition to a Risk-Based Capital (RBC) regulatory framework for the Indian insurance industry.
- Principle of RBC: Insurers will hold capital proportionate to the risks they undertake, including investment, underwriting, operational, and market risks.
- Objective: Strengthen financial stability, enhance policyholder protection, and support globalisation of India’s insurance industry.
- Moves Indian insurers closer to international solvency norms.
RBI Study: Foreign Liabilities of Indian Mutual Funds Rise 19.9% in FY25
- Governed under Foreign Exchange Management Act (FEMA), 1999.
- Foreign Liabilities: Increased 19.9% YoY, reaching ₹2.6 lakh crore in FY25, up from ₹2.1 lakh crore in FY24.
- Top Investors: UAE: Largest contributor, accounting for 1/5th of total MF investments. U.S. & U.K.: Together contributed ~20% . Australia & Canada: Fastest growth, with investments rising over 40% in FY25.
- U.S. & U.K.: Together contributed ~20% .
Urban Challenge Fund (UCF)
- Initial Allocation (FY 2025–26): ₹10,000 crore
- At least 50% of funding must come from market sources like: Municipal bonds Bank loans Public–Private Partnerships (PPPs)
- The Urban Challenge Fund (UCF) is a ₹1 lakh crore financing mechanism announced in the Union Budget 2025–26 to support transformative and bankable urban development projects in India.
- Corpus: ₹1 lakh crore
Nifty Bank Index
- Weight of any single stock in non-benchmark indices capped at 20%.
- Combined weight of top three constituents capped at 45%.
- Indices must have at least 14 stocks (Nifty Bank currently has 12).
- Introduced by NSE: 2003
SEBI Reconsiders Intraday Limits for Equity Derivatives
- The Securities and Exchange Board of India (SEBI) is reviewing stricter position limits on index derivatives in the Indian markets. This comes in the backdrop of concerns over manipulative trading strategies impacting retail investors.
- Aimed at reducing market volatility, manipulation risks, and protecting retail participation.
- Safeguard retail investors from high-risk derivative bets.
- Stricter intraday position limits for index derivatives.
InvITs and REITs AUM Cross $94 Billion in FY25
- Like InvITs, REITs must distribute at least 90% of net distributable cash flows.
- Regulated by SEBI (Infrastructure Investment Trusts) Regulations, 2014.
- Regulated by SEBI (Real Estate Investment Trusts) Regulations, 2014.
- According to a report by Knight Frank India, the combined Assets Under Management (AUM) of Infrastructure Investment Trusts (InvITs) and Real Estate Investment Trusts (REITs) in India have shown remarkable growth over the last five years.
Registered Investment Advisers (RIAs) and Research Analysts
- The RIA model struggled to expand due to high entry barriers and stringent compliance introduced in 2020.
- Governed by SEBI (Investment Advisers) Regulations, 2013.
- SEBI introduced fee-based advisory regulations in 2013.
- Reforms since January 2025 have gradually eased these norms.
HDFC ERGO and PhonePe Launch Affordable Health Insurance for the “Missing Middle”
- Premiums start at ₹12 per day for ₹3 lakh coverage.
- Target audience: Individuals aged 18–30 years, many new to insurance.
- Enhances health insurance penetration among younger, underserved demographics.
TaxBuddy Launches AI-Powered Tax Filing System
- Instant Support: The system offers immediate query resolution, assisting users as they file.
- Empowerment: The initiative is about more than speed it’s designed to provide taxpayers with clarity and confidence during the process.
Punjab National Bank Becomes First PSU Bank to Migrate to ‘.bank.in’ Domain
- Regulatory Framework: Move made in line with the RBI circular (April 22, 2025) on migration to the ‘.bank.in’ domain.
- Punjab National Bank (PNB) has successfully migrated its corporate website to www.pnb.bank.in, becoming the first Public Sector Bank in India to adopt the ‘.bank.in’ domain, as per RBI’s recent guidelines.
- Objective: Strengthen cyber security. Prevent frauds and phishing attacks. Enhance public trust in digital banking.
- New Domain: PNB’s corporate website is now www.pnb.bank.in, replacing the old www.pnb.co.in.
RBI MPC August 2025
- Inflation Risks: Inflation is likely to go above the RBI’s 4% target, possibly near 4.9% in early 2026. RBI wants to avoid cutting rates too soon, which could reduce room to act if inflation rises further.
- Inflation is likely to go above the RBI’s 4% target, possibly near 4.9% in early 2026.
- The Reserve Bank of India (RBI) released the minutes of the latest Monetary Policy Committee (MPC) meeting, underscoring concerns over the adverse impact of global trade tensions, tariffs, and geopolitical uncertainties on India’s growth outlook.
- Rural Economy: High-frequency indicators show buoyant rural economic activity and consumption.
Centre Proposes GST Exemption on Life and Health Insurance Policies for Individuals
- GoM Approval: The 13-member Group of Ministers (GoM) on health and insurance, headed by Bihar Deputy CM Samrat Choudhary, has endorsed the proposal.
- Objective: Reduce financial burden on consumers. Promote financial inclusion, strengthen healthcare, and support schemes like Ayushman Bharat.
- Life Insurance Policies GST Rate: 18% on the insurance premium. Premium Components: GST is charged on the premium paid by the policyholder, excluding any investment component in ULIPs. Example: If annual premium = ₹1,00,000 → GST = ₹18,000.
- GST Rate: 18% on the insurance premium.
India Exim Bank signs $40 million credit line deal with Africa’s ECOWAS Bank
- Founded in 1982 under the Export-Import Bank of India Act.
- Ownership: Owned by 15 ECOWAS member states (West Africa).
- Full Form: ECOWAS Bank for Investment and Development.
- The Export-Import Bank of India (India Exim Bank) and the ECOWAS Bank for Investment and Development (EBID) signed a $40 million commercial credit line agreement to boost India-Africa economic ties.
SEBI’s Proposal to Regulate Grey Market & Pre-Listing Trading
- Definition: An unregulated market where shares of companies awaiting IPOs are traded privately between buyers and sellers.
RBI Discussion Paper on Flexible Inflation Targeting (FIT) Framework
- First review: 2021
- Current target: 4% CPI inflation with a tolerance band of ±2% (2%-6%).
- Target Inflation: Current target: 4% headline CPI with a tolerance band of ±2%. Headline CPI includes food and energy prices, while core inflation excludes them.
- Current target: 4% headline CPI with a tolerance band of ±2%.
Dynamic Asset Allocation Active Fund of Funds (FoF)
- Objective: Provide investors with a convenient one-fund solution by leveraging multiple actively managed equity and debt strategies.
- Fund of Funds (FoF) Structure: The FoF invests in a portfolio of other mutual funds instead of buying individual stocks, bonds, or commodities. Offers diversification across multiple fund managers and asset classes.
- Offers diversification across multiple fund managers and asset classes.
- Aims to capture upside in favorable markets and protect capital in downturns.
SEBI Looks to Promote Long-Tenure Derivatives
- Current Scenario: Retail investors prefer weekly options over longer-tenure (1, 2, and 3-month) contracts.
- SEBI’s Plan: Promote hedging and long-term investment strategies. Consult with stakeholders to review the maturity profile of derivatives. Potentially restrict or phase out weekly options contracts.
- Consult with stakeholders to review the maturity profile of derivatives.
- Extended Expiry Periods: Can expire monthly, quarterly, or even yearly, unlike weekly derivatives which expire in 7 days. Reduces the focus on short-term speculation and high-frequency trading.
AU Small Finance Bank Launches UPI Services for NRE/NRO Accounts
- Established: 2017 (converted from AU Financiers).
- Headquarters: Jaipur, Rajasthan.
- Eligible Users: NRIs holding NRE/NRO accounts with AU SFB.
- Supported Countries (12): Australia, Canada, France, Hong Kong, Malaysia, Oman, Qatar, Saudi Arabia, Singapore, UAE, UK, USA.
IndiGo & IDFC FIRST Bank Launch Dual-Network IndiGo IDFC FIRST Credit Card
- Accessibility & Inclusion: Offers a Fixed Deposit (FD)-backed variant, making it accessible even to customers with limited credit history.
RBI’s Discussion Paper on Flexible Inflation Targeting (FIT)
- Domestic Success CPI inflation mostly stayed within 2–6% since 2016. July 2025 CPI at 1.55% shows effective price stability.
- CPI inflation mostly stayed within 2–6% since 2016.
- July 2025 CPI at 1.55% shows effective price stability.
- In India: Adopted in 2016 under an amendment to the RBI Act, 1934.
SEBI Chief Cautions AMCs on Micro-Cap Investments, Urges Transparency
- What? Firms with a market value of ₹500–₹1,000 crore.
- What? Systematic Investment Plans starting from just ₹250/month.
- At the 30th anniversary of the Association of Mutual Funds in India (AMFI), SEBI Chairperson Tuhin Kanta Pandey highlighted key regulatory concerns for the mutual fund industry, focusing on risk management, investor protection, and transparency.
- Why? Encourages small savers to invest regularly and builds financial inclusion.
L&T Finance Partners with Google Pay to Offer Instant Personal Loans
- Objective: Strengthen LTF’s product diversification strategy and expand credit accessibility through a seamless digital channel.
- Functionality: Eligible Google Pay users can apply for and access LTF personal loans directly within the app.
Advisory Board for Banking & Financial Frauds (ABBFF)
- The Advisory Board for Banking and Financial Frauds (ABBFF) has been reconstituted for a two-year term, effective August 21, 2025. Functions as a ‘Safety Valve’ for bankers, providing advice before criminal investigations in major fraud cases.
- Cases Covered: Fraud cases involving ₹3 crore and above.
- Significance: Protects honest bankers from harassment, while ensuring accountability in genuine fraud cases.
- Purpose: Acts as an advisory body to determine whether bank/financial institution officials had any criminal intent or malafide involvement in frauds.
Capital Charge for Counterparty Credit Risk (CCR)
- Objective: Align with Basel Committee on Banking Supervision (BCBS) guidelines. Reflect market developments since the last revision in August 2008.
- Reflect market developments since the last revision in August 2008.
- Proposed Changes: Inclusion of equity derivatives, precious metals (except gold), and commodity derivatives under CCR. Specification of credit conversion factors (CCF) to ensure adequate capital provisioning for such exposures.
- Specification of credit conversion factors (CCF) to ensure adequate capital provisioning for such exposures.
RBI Empowers Federal Bank to Process Maharashtra Government Payments via GRAS
- Founded: 1931 (as Travancore Federal Bank), renamed Federal Bank in 1949
- Launched in 2010 by Maharashtra’s Finance Department, GRAS serves as a virtual treasury.
- Headquarters: Aluva, Kerala
- This streamlines payment workflows, reduces manual entry errors, and enhances transparency.
SEBI Proposes Closing Auction Session (CAS) for Derivative Stocks
- Timing: Typically occurs in the last few minutes of the trading session. Duration may vary by exchange (e.g., NSE CAS runs from 3:30 PM to 3:40 PM for most securities).
- Participants can place buy or sell orders during the CAS period.
- The exchange matches orders at a single equilibrium price where the maximum volume can be traded.
- Any unmatched orders are carried forward to the next trading day (subject to exchange rules).
SEBI Seeks States’ Help to Combat Cyber Fraud in Securities Market
- Modus Operandi: Fraudsters impersonate registered intermediaries or market experts. They create fake profiles, run WhatsApp/Telegram groups as “educational” platforms, and give investment advice.
- Fraudsters impersonate registered intermediaries or market experts.
- Action against unregistered investment advisors, research analysts, and “finfluencers”.
- Verified Social Media Advertising Intermediaries are now required to register on social platforms using verified email and mobile numbers, and platforms must verify their credentials before allowing advertising.
Pradhan Mantri Jan-Dhan Yojana (PMJDY)
- Launched on 28 August 2014, PMJDY is the Government of India’s flagship financial inclusion programme aimed at providing universal access to banking services.
- Life and Accident Insurance: ₹2 lakh accidental insurance cover under Pradhan Mantri Suraksha Bima Yojana (PMSBY). ₹30,000 life insurance cover for eligible beneficiaries at account opening.
- ₹2 lakh accidental insurance cover under Pradhan Mantri Suraksha Bima Yojana (PMSBY).
- Overdraft Facility: Up to ₹10,000 available per household after satisfactory account operation.
Crisil Removes Watch Negative Tag for IndusInd Bank’s Long-Term Ratings
- Revised Status: Crisil reaffirmed IndusInd Bank’s long-term rating at AA+, removing the Watch Negative tag but maintaining a Negative Outlook.
- Implications: Signals restored confidence in the bank’s capital position and governance reforms. Likely to reduce borrowing costs and enhance investor sentiment.
- Signals restored confidence in the bank’s capital position and governance reforms.
SEBI Approves Reclassification of LIC as Public Shareholder in IDBI Bank
- Stake Reduction: LIC must bring down its holding in IDBI Bank to 15% or below within two years.
- LIC must bring down its holding in IDBI Bank to 15% or below within two years.
- Voting Rights Limited: LIC’s voting rights will be capped at 10%, meaning it cannot dominate shareholder decisions.
- LIC’s voting rights will be capped at 10%, meaning it cannot dominate shareholder decisions.
South Indian Bank Launches ‘SIB Gold Xpress’
- Borrowers can get loans worth up to 90% of their pledged gold’s value.
- Loan amounts range from ₹25,000 to ₹25 lakh, with tenures of up to 3 years.
- Designed for MSMEs, small businesses, and individuals, particularly first-time or “new-to-credit” borrowers.
- Funds can be used for business expansion, working capital, or personal needs, offering fast, credit-helpful solutions.
IndusInd Bank Signs MoU with NSIC to Boost MSME Credit Delivery
- Founded: 1994
- Purpose: To accelerate credit delivery and extend financial support to 6.7+ crore Udyam-registered MSMEs across India.
- Headquarters: Mumbai, Maharashtra, India
- IndusInd Bank has signed a Memorandum of Understanding (MoU) with the National Small Industries Corporation (NSIC), a Government of India enterprise under the Ministry of MSME, to enhance financial access for micro, small, and medium enterprises (MSMEs).
SBI Launches Centre of Excellence for MSMEs at Gurugram Academy
- Purpose: Enhance the MSME ecosystem by engaging with promoters, startups, industry associations, academia, government, regulators, and banking professionals. Support India’s vision of becoming a developed nation.
- Enhance the MSME ecosystem by engaging with promoters, startups, industry associations, academia, government, regulators, and banking professionals.
Finance Ministry Allows One-Time Switch from Unified Pension Scheme (UPS) to National Pension System (NPS)
- What it is: A defined-contribution pension scheme introduced in 2004 for government employees (except armed forces) and later opened to all citizens.
- A defined-contribution pension scheme introduced in 2004 for government employees (except armed forces) and later opened to all citizens.
- What it is: Introduced April 1, 2025, as an option within NPS for Central government employees. Provides assured payouts post-retirement. Enrollment deadline: September 30, 2025.
- Introduced April 1, 2025, as an option within NPS for Central government employees.
RBI May Intervene if US Tariffs Impact Growth
- Corporate Financing Trends (SBI View): India Inc holding ₹13.5 trillion in cash reserves. Capex funded largely through internal accruals, reducing demand for bank loans. Banks seek RBI nod to finance M&A deals to boost credit offtake.
- Reserve Bank of India (RBI) Governor Sanjay Malhotra signaled readiness to take policy measures if the 50% U.S. tariff, set to take effect this week, negatively impacts India’s economic growth. He also outlined upcoming regulatory reforms for banks.
- US Tariff Impact & RBI Response: 50% U.S. tariff on select imports effective Wednesday. RBI assures ample liquidity to support growth and sector-specific support if required.
- 50% U.S. tariff on select imports effective Wednesday.
Fitch Retains India’s BBB- Sovereign Rating with Stable Outlook
- Impact of U.S. Tariffs: Could dampen business confidence. May reduce India’s competitiveness compared to other Asian nations. Direct GDP impact is modest as U.S. exports account for only ~2% of GDP.
- Direct GDP impact is modest as U.S. exports account for only ~2% of GDP.
- Concerns Highlighted by Fitch: Subdued Private Investment: Weak business sentiment may persist. Impact of U.S. Tariffs: Could dampen business confidence. May reduce India’s competitiveness compared to other Asian nations. Direct GDP impact is modest as U.S. exports account for only ~2% of GDP. Fiscal Challenges: High fiscal deficit and debt levels at the general government level. Lagging structural indicators like governance metrics and low GDP per capita.
- Subdued Private Investment: Weak business sentiment may persist.
Corporate Funding Moving Away from Banks – FICCI-IBA Report
- Corporate Advances Decline: Share of corporate loans in total bank credit has fallen from 58% to 36%.
- A joint report by FICCI and the Indian Banks’ Association (IBA), titled “Charting New Frontiers” and prepared by Boston Consulting Group (BCG), highlights a significant transformation in India’s bank lending pattern over the last 14 years, as well as the emerging opportunities and challenges for the sector.
- Banks must play a key role in funding new capex for sunrise sectors (green energy, digital infrastructure, manufacturing) and large infrastructure projects to achieve India’s growth aspirations.
- Working Capital Focus: Within bank lending, short-term working capital loans dominate over long-term capex loans.
SBI Requests RBI to Permit Acquisition Financing by Banks
- State Bank of India (SBI), the country’s largest lender by assets, has sought regulatory approval from the Reserve Bank of India (RBI) to allow banks to finance mergers and acquisitions (M&A) of companies.
- Banks in India are currently barred from lending directly for mergers and acquisitions (M&A).
- SBI Chairperson Challa Sreenivasulu Setty urged the RBI to consider permitting acquisition financing, at least for large, listed companies.
- Allowing banks to fund acquisitions could: Increase liquidity for big-ticket deals. Reduce dependency on NBFCs and foreign lenders. Strengthen domestic credit markets.
Bandhan Bank Launches Legacy Savings Account for Affluent Customers
- Founded: 23 August 2015
- On its 10th anniversary, Bandhan Bank has introduced the Legacy Savings Account, a premium banking product designed for high-net-worth and affluent customers, offering exclusive lifestyle and banking benefits.
- Headquarters: Kolkata, West Bengal, India
- Dedicated Relationship Manager for personalized service.
RBI Imposes Penalty on Ayodhya Finlease Limited for Regulatory Non-Compliance
- Legal Provision Invoked: Section 58G(1)(b) read with Section 58B(5)(aa) of the RBI Act, 1934.
- Section 58G(1)(b) read with Section 58B(5)(aa) of the RBI Act, 1934.
- The Reserve Bank of India (RBI) has imposed a monetary penalty of ₹1 lakh on Ayodhya Finlease Limited, an NBFC, for violating regulatory guidelines.
- Reason for Penalty: Failure to obtain prior written RBI approval for a change in shareholding exceeding 26% of paid-up equity capital.
Framework to Simplify Transfer of Unclaimed Shares and Dividends
- Current Rule: If a dividend remains unpaid/unclaimed for 30 days, it must be moved to an unpaid dividend account. This is mandated by Section 124 of the Companies Act, 2013. If unclaimed for seven consecutive years, both the amount and the associated shares are transferred to the Investor Education and Protection Fund (IEPF).
- If a dividend remains unpaid/unclaimed for 30 days, it must be moved to an unpaid dividend account. This is mandated by Section 124 of the Companies Act, 2013.
- The Ministry of Corporate Affairs (MCA) and the Securities and Exchange Board of India (SEBI) are jointly developing a framework to streamline the transfer and claim process for unclaimed shares and dividends.
- Objective: Harmonise shareholder identification requirements, simplify transmission of shares, and ensure uniformity across companies.
RBI’s FREE-AI Framework
- People First – Human judgment and citizen welfare must remain central in AI decisions.
- Understandable by Design – AI decisions must be interpretable and traceable.
- Capacity: Train leadership and professionals on ethical AI practices.
- Governance: Mandate policies like board-level oversight, AI inventory, and product approval pathways.
Malaysia Launches Ryt Bank: First AI-Powered Digital Bank
- Smart Banking Features: Savings: Offers up to 4% p.a. daily interest on deposits up to RM 20,000 with no lock-in period. Credit: Ryt PayLater provides instant, no-document credit (~RM1,499) with 0% interest if repaid within one month, plus cashback rewards.
- Savings: Offers up to 4% p.a. daily interest on deposits up to RM 20,000 with no lock-in period.
- Credit: Ryt PayLater provides instant, no-document credit (~RM1,499) with 0% interest if repaid within one month, plus cashback rewards.
- Multilingual Support: Supports Bahasa Malaysia and English from launch, with Mandarin to be added by September 2025.
PhonePe Launches Affordable Home Insurance Product in India
- On August 25, 2025, PhonePe announced the launch of its home insurance product line, aimed at providing a simple, affordable, and fully digital solution for homeowners to protect their properties.
- Low-Cost Premiums: Starting at ₹181 per year (including GST).
- Flexible Coverage: Ranges from ₹10 lakhs to ₹12.5 crores, covering both structure and contents (furniture, appliances, valuables, etc.).
- Risk Coverage: Protection against 20+ risks including fire, floods, earthquakes, riots, and theft.
India May Become World’s 2nd-Largest Economy by 2038: EY Report
- Global Challenges and Mitigation: US tariffs on Indian imports could impact growth, but adverse effects can be limited to 10 basis points with proper countermeasures. Resilience driven by domestic consumption rather than external trade reliance.
- US tariffs on Indian imports could impact growth, but adverse effects can be limited to 10 basis points with proper countermeasures.
- According to the August 2025 issue of EY Economy Watch, India’s economic trajectory remains robust despite global uncertainties. The report projects India to emerge as the second-largest economy by 2038, supported by strong domestic fundamentals.
- Growth Projections: $20.7 trillion GDP (PPP) by 2030 $34.2 trillion GDP (PPP) by 2038, making India the 2nd-largest economy globally.
Specialised Investment Funds (SIFs) Set to Debut in India as SEBI Issues First Approvals
- Launch Plans: Quant MF will launch qsif Equity Ex-Top 100 Long-Short Fund and qsif Equity Long-Short Fund in September 2025. At least one more AMC has received approval, and two others are close to securing it.
- About SIFs: Introduced by SEBI in April 2025. Allow complex investment strategies such as long-short equity and debt schemes. Minimum investment ticket size: ₹10 lakh. MFs require two clearances – a one-time licence and product-specific approvals.
- Scheme Strategy: qsif Equity Long-Short Fund → invests across market caps. qsif Equity Ex-Top 100 Long-Short Fund → focuses on midcaps & smallcaps. Derivatives long positions capped at 50%, unhedged short exposure up to 20%.
- Minimum investment ticket size: ₹10 lakh.
SEBI on Finfluencers
- New SEBI Circular (January 2025): Educators can only use stock data older than three months. Live prices, recent tips, or indirect recommendations are banned. Prohibited activities include stock-specific advice, return guarantees, demo trades, and coded investment suggestions.
- Educators can only use stock data older than three months.
- Legal Perspective: Experts highlight a fine line between education and advice; any suggestion influencing investment decisions can invite regulatory action. SEBI has powers to ban entities, seek refunds, and initiate criminal proceedings against violators.
- SEBI has powers to ban entities, seek refunds, and initiate criminal proceedings against violators.
Government Appoints Goldman Sachs as Advisor for PSB Stake Sale
- SEBI Norm Compliance – Listed entities must have 25% minimum public shareholding.
- The Government of India has appointed Goldman Sachs as the sole transaction advisor for stake dilution in four public sector banks (PSBs) — UCO Bank, Central Bank of India, Punjab & Sind Bank, and Indian Overseas Bank (IOB).
- Stake dilution means the government selling a portion of its equity in PSBs to other investors (retail, institutional, or foreign).
- Role of Goldman Sachs: Responsible for structuring the transaction, identifying potential investors, and overseeing execution.
Tata AIA Launches ‘Health SIP’ and ‘Health Buddy’ for Integrated Health and Wealth Solutions
- Critical illness protection with premium lock-in of up to 30 years.
- Offers preventive health check-ups, women’s health support, dental consultations, and access to 24+ medical specialties.
- Marketed as India’s first 24x7 health and wellness companion from a life insurer.
- Health SIP – Features: Combines health coverage with investment opportunities. Zero premium allocation charges with maturity boosters to enhance fund value. Tax-free withdrawals from the 6th policy year for health expenses. Critical illness protection with premium lock-in of up to 30 years. Variants: Health SIP Plus: Includes Accidental Total & Permanent Disability benefits. Health SIP Plus Pro: Adds Terminal Illness with Term Booster for extra protection.
SEBI Proposes Reforms to Block Deal Framework to Enhance Transparency
- Minimum Order Size: Proposed increase to ₹25 crore (from the existing ₹10 crore, in place since 2017).
- Proposed increase to ₹25 crore (from the existing ₹10 crore, in place since 2017).
- Pricing Mechanism: Non-F&O stocks: Proposed widening of price band to 3% from the previous day’s closing price. F&O stocks: Existing 1% price band to continue.
- Non-F&O stocks: Proposed widening of price band to 3% from the previous day’s closing price.
BharatPe Launches Unity Bank BharatPe Credit Card
- Partnership: BharatPe + Unity Small Finance Bank (Unity Bank).
- BharatPe, in partnership with Unity Small Finance Bank, has launched the Unity Bank BharatPe Credit Card on the NPCI RuPay network. The card aims to provide transparent, lifetime-free credit access with innovative features and flexibility for Indian consumers.
- Zero-Fee Card: No joining fee, annual fee, processing charges, or foreclosure penalties. Customers can prepay EMIs anytime without penalties.
- Customers can prepay EMIs anytime without penalties.
SEBI Approves Groww’s $1 Billion IPO
- Founded: 2016 (by ex-Flipkart employees Lalit Keshre, Harsh Jain, Neeraj Singh, and Ishan Bansal).
- Net Tangible Assets: At least ₹3 crore in each of the past 3 years.
- Profitability: At least ₹15 crore aggregate pre-tax profit in the last 3 years.
- Net Worth: Minimum ₹1 crore in each of the past 3 years.
UMANG (Unified Mobile Application for New-age Governance)
- Single Platform – Provides access to 1,000+ services from 200+ departments across the Centre, States, and Union Territories.
- Multilingual Support – Supports 13 Indian languages apart from English.
- 24x7 Availability – Services are available anytime, anywhere.
- Education & Employment: CBSE results, National Scholarships, e-Pathshala, e-Books.
RBI State of the Economy Report (August 2025)
- Trade Concerns US imposed steep 50% tariffs on Indian goods exports from August 27, 2025. RBI flagged uncertainties in trade relations as a downside risk for growth.
- US imposed steep 50% tariffs on Indian goods exports from August 27, 2025.
- CPI inflation fell to 1.6% in July 2025 (8-year low) vs. 2.1% in June 2025.
- RBI’s Monetary Policy Committee (MPC) cut repo rate by 100 basis points (Feb–June 2025).
RBI Mulls Restrictions on Shadow Lenders’ Subsidiaries
- The term shadow lenders usually refers to Non-Banking Financial Companies (NBFCs) and other non-bank credit institutions that provide loans outside the traditional banking system.
- Deputy Governor Swaminathan Janakiraman (March 2025) clarified that regulation aims to: Prevent blowups, Ensure financial stability, Avoid stifling innovation in NBFCs.
- The Reserve Bank of India (RBI) is considering directing non-banking financial companies (NBFCs), or shadow lenders, to scale down subsidiary operations that overlap with the parent’s business, aligning rules with those already proposed for banks.
- Shadow Lenders’ Subsidiaries: These are entities owned or promoted by shadow lenders (NBFCs/HFCs/Fintechs) that engage in related financial services, often beyond core lending.
Punjab National Bank Launches India’s First Startup-Centric Branch
- Punjab National Bank (PNB) inaugurated its first dedicated branch for startups at Bhikaji Cama Place, New Delhi, aligned with the Startup India initiative.
- Tailored Banking Services: The branch offers customised credit schemes, advisory support, and financial literacy programs designed for early-stage startups.
- The branch offers customised credit schemes, advisory support, and financial literacy programs designed for early-stage startups.
- Aims to bridge the financing gap faced by startups by offering a one-stop banking solution, enhancing accessibility and support.
RBI Grants In-Principle Approval for Aditya Birla Capital to Operate as Payment Aggregator
- Aditya Birla Capital’s subsidiary, Aditya Birla Capital Digital Ltd (ABCDL), has received in-principle authorization from the Reserve Bank of India (RBI) to operate as an online payment aggregator under the Payment and Settlement Systems Act, 2007.
- The Payment and Settlement Systems Act, 2007 is the key legislation in India that provides a legal framework for regulation and supervision of payment systems in the country. It empowers the Reserve Bank of India (RBI) to regulate and oversee payment and settlement systems to ensure safety, efficiency, and stability.
- To designate RBI as the authority for authorization and oversight of payment systems.
Utkarsh Small Finance Bank Partners with Hitachi Payment Services for Payment Processing and Debit Card Management
- Aims to streamline debit card lifecycle management for over 2.1 million cardholders.
- Scope of Partnership: Aims to streamline debit card lifecycle management for over 2.1 million cardholders. The system upgrade will make ATM, POS, and e-commerce transactions faster and more secure.
- Utkarsh Small Finance Bank (SFB) has partnered with Hitachi Payment Services to enhance its payment processing system and debit card management platform.
- Institutional Focus: Utkarsh SFB continues to provide financial services to underserved and unserved sections of society.
| Initiative | Year / Institution | Key Features | Target Group / Benefit |
|---|---|---|---|
| Pradhan Mantri Jan Dhan Yojana (PMJDY) | 2014 | Zero-balance accounts, RuPay debit card, accidental & life insurance cover | Unbanked households |
| Business Correspondent (BC) Model | RBI directive | Agents deliver doorstep banking services | Rural & remote populations |
| Aadhaar Enabled Payment System (AePS) | UIDAI + NPCI | Biometric-based digital banking transactions | Rural & semi-urban poor |
| Unified Payments Interface (UPI) | NPCI (2016) | Instant, low-cost, interoperable digital payments | General public, merchants, small businesses |
| India Stack | Govt + Fintech | APIs for paperless, cashless, presence-less financial transactions | Digital economy & underserved |
| Pradhan Mantri Mudra Yojana (PMMY) | 2015 | Collateral-free loans up to ₹10 lakh (Shishu, Kishore, Tarun categories) | Small businesses, entrepreneurs |
SEBI Plans Incentives for First-Time Women Mutual Fund Investors
- Established: 1988 (statutory status in 1992)
- B30 City Incentives: SEBI has already proposed to incentivise distributors for investments from first-time individual investors in B30 cities (beyond top 30 cities). This will expand mutual fund penetration in tier-2 and tier-3 cities.
- SEBI has already proposed to incentivise distributors for investments from first-time individual investors in B30 cities (beyond top 30 cities).
- Headquarters: Mumbai, Maharashtra
Index of Industrial Production (IIP)
- Sectoral Classification (3 Sectors): Manufacturing (77.63% weight) Mining (14.37% weight) Electricity (7.99% weight)
- Manufacturing (77.63% weight)
- Mining (14.37% weight)
- Electricity (7.99% weight)
Jio Payments Bank to Launch “Savings Pro” Deposit Account
- Launched: April 2018
- Promoters: Reliance Industries Limited (RIL) and State Bank of India (SBI)
- India’s first savings account that auto-invests idle cash into overnight mutual funds for better returns.
- Aims to combine the liquidity of savings deposits with the yield of short-term mutual funds.
Agriculture · 24
Reassessing India’s Agricultural Protectionism and the Need for Market Reforms
- Tariff protections, originally meant to shield farmers, have become counterproductive: Created concentric rings of protection across agriculture, manufacturing, and services. Result: Uncompetitive agriculture, low farm wages, and inefficient food systems.
- Leads to: Surpluses in some crops → necessitating exports. Deficits in others → requiring imports.
- Deficits in others → requiring imports.
- Result: Persistently low agricultural productivity and incomes.
Cabinet Approves “Grant-in-Aid to National Cooperative Development Corporation (NCDC)” Scheme
- The Union Cabinet has approved a new Central Sector Scheme titled “Grant-in-Aid to NCDC”, with a total outlay of ₹2,000 crore for four years (FY 2025–26 to FY 2028–29).
- Established: 1963
- Total Outlay: ₹2,000 crore (₹500 crore annually)
- Funding Purpose: Grant to be used by NCDC to mobilize ₹20,000 crore from open markets. Loans to be provided to cooperatives for: Setting up new projects Expansion, modernization, and tech upgradation Working capital support
AI in Indian Agriculture
- Water Efficiency: AI-based irrigation systems can cut water usage by 80% and boost yields by 20–30%.
- Digital Integration: Over 15 million farmers now use AI-enabled platforms that provide personalized insights based on crop, soil, and climate data.
- Post-Harvest Efficiency: AI helps reduce wastage and improves price discovery by directly linking farmers with buyers.
- Digital Literacy: Many farmers are unaware or lack skills to use AI-based tools.
Bio-Fortified Iron-Rich Potatoes to Enter Indian Markets Soon
- The first iron-rich variety has already been released in Peru and is now under evaluation for Indian agro-climatic conditions.
- Scaling Access to Farmers: CIP plans to expand seed access to Indian farmers to promote wider adoption of nutrient-rich tuber crops. Focus on integrating agronomic suitability with nutritional value in local crop development.
- CIP plans to expand seed access to Indian farmers to promote wider adoption of nutrient-rich tuber crops.
Agri-Influencers in India
- India is on track to reach over 900 million internet users by 2025, with the majority from rural areas, according to IAMAI-Kantar. This digital expansion has given rise to a new category of content creators—agri-influencers—who are reshaping perceptions of rural life and agriculture through authentic, grassroots digital content.
- Real-life farmers sharing their experiences on YouTube, Instagram, ShareChat, and similar platforms.
- Influencers are becoming rural role models and fostering community pride.
- Agri-influencers are trusted product endorsers, especially for seeds, tools, and agri-fintech products.
Shifts in India’s Pesticide Market
- Labour Shortage & Cost: Manual weeding takes 8–10 hours/acre. Average daily wage for agricultural labour rose to ₹447.6 in Dec 2024 (Labour Bureau), from ₹326.2 in 2019.
- Average daily wage for agricultural labour rose to ₹447.6 in Dec 2024 (Labour Bureau), from ₹326.2 in 2019.
- Insecticides Act, 1968: Governs all aspects of pesticide lifecycle.
- Kisan Drone Scheme (2022): Subsidizes drone-based precision pesticide application.
Ethanol Blending in India
- National Policy on Biofuels (2018): Allowed diverse feedstocks, including sugarcane juice, FCI surplus grains, rotten potatoes, etc.
- Price & Tax Incentives: Fixed ethanol prices by OMCs for supply certainty. GST reduction from 18% to 5%. Capital support and interest subvention for ethanol distilleries.
- GST reduction from 18% to 5%.
- Vehicle Compatibility Issues: Most existing vehicles in India are designed for E10. Lack of widespread flex-fuel vehicles or retrofit guidelines makes higher blends (E20+) unsuitable for the majority fleet, especially two-wheelers.
Farmers’ Library Inaugurated in Ludhiana
- FPOs are generally set up under: Companies Act, 2013 as Producer Companies Cooperative Societies Act Societies Registration Act, etc.
- Companies Act, 2013 as Producer Companies
- To act as a bridge between farmers and buyers, including processors, exporters, and retailers.
- Inaugurated by Dr J P S Gill, Vice-Chancellor of Guru Angad Dev Veterinary and Animal Sciences University (GADVASU).
TraceX Technologies Launches Agentic AI Tool
- Satellite-Based Risk Assessment Uses global satellite datasets (like Hansen and JRC) to check if land was deforested after the 2020 cut-off date under EUDR.
- Uses global satellite datasets (like Hansen and JRC) to check if land was deforested after the 2020 cut-off date under EUDR.
- With the European Union’s Deforestation Regulation (EUDR) set to come into effect from December 2025, TraceX Technologies, a Bengaluru-based agrifood and climate tech start-up, has launched an Agentic AI-powered tool to automate compliance processes for exporters.
- Automated Supplier Onboarding & KYC Captures supplier credentials, land ownership documents, and verifies plots using AI-based document and email parsing.
Punjab: First State to Upgrade Cooperative Banks to Finacle 10
- Era: Older version (legacy system), widely used in early 2000s–2010s.
- Upgrading to Finacle 10 enables them to: Provide real-time transactions and digital services. Integrate UPI, AEPS, and other payment systems. Meet RBI compliance more efficiently. Offer personalised financial products based on customer data.
- Punjab has become the first state in India to complete the upgrade of its cooperative banks’ Core Banking Solution (CBS) from Finacle 7 to Finacle 10, marking a major leap in digital transformation for the rural banking sector.
- Strengthens rural banking infrastructure to better serve farmers, self-help groups, and rural entrepreneurs.
AI and Satellite Intelligence Transforming Indian Agriculture
- Climate Volatility: Irregular monsoons affect ~70% of farmland.
- Yield Gains: AI-driven advisories have boosted yields by 15–20%.
- Input Efficiency: Fertiliser use reduced by up to 30% without affecting yield.
- Vision 2030 for Agriculture: Focus on sustainability and resilience.
Soil Health: The Cornerstone of Sustainable Food Security in India
- Dependence on Soil: Over 99.7% of global food relies on soil, yet degradation undermines productivity, water resources, ecosystems, and nutrition.
- India’s Soil Crisis: Intensive farming, fertilizer overuse, and monocropping have degraded ~30% of soils (147 million ha).
- Undernourishment: 735 million people face chronic hunger, linked to declining soil fertility.
- Nutrient Deficiency: Depleted soils lower crop nutrition, worsening rural malnutrition.
NABARD Marks National Handloom Day
- Assam has 12.83 lakh weavers, over 90% of whom are women.
- NABARD’s Contribution: Over 8,000 weavers benefited from skill training, enterprise promotion, marketing support, and formation of Weavers Producer Organisations (WPOs). GI registration support for handloom products.
- Over 8,000 weavers benefited from skill training, enterprise promotion, marketing support, and formation of Weavers Producer Organisations (WPOs).
- Significance of Assam’s Handloom Sector: Assam has 12.83 lakh weavers, over 90% of whom are women. Known for products like the Assamese phulam gamosa. Key initiatives include Swanirbhar Naari portal, Integrated Handloom Park at Kaziranga, and Silk Tourism projects in Sualkuchi.
NABARD, APGB Partner with Aqua Exchange for IoT-Enabled Shrimp Farming Loans
- Objective: Bring farmers into the formal credit system, reduce reliance on informal lenders, and enhance productivity and sustainability.
- Loan Disbursement: Loan sanction letters worth ₹1.25 crore were issued to five farmers, along with IoT devices.
- NABARD sanctioned ₹3.46 crore for a six-year tribal development project in Buttayagudem and Polavaram mandals, Eluru district.
- Pilot Project: Introduces IoT-enabled loans for shrimp farmers to monitor water quality, feed usage, and disease control in real time.
Discovery of Chalk9 Gene in Rice to Reduce Grain Chalkiness
- Varieties and Breeding: Chalk9-H (high chalkiness) was dominant before 1990. Chalk9-L (low chalkiness) increased significantly after 1990 due to breeding programs. Now, breeders can directly introduce Chalk9-L to improve grain quality.
- Breakthrough Discovery: Researchers sequenced genomes of 175 rice varieties. Found a DNA segment on chromosome 9 strongly linked with chalkiness. This segment regulates the Chalk9 gene in the rice endosperm.
- Researchers sequenced genomes of 175 rice varieties.
- Now, breeders can directly introduce Chalk9-L to improve grain quality.
SRMIST Hosts ‘Agri Startup 2.0’ to Promote Sustainable Farming
- Organisers: SRMIST College of Agricultural Sciences. In collaboration with Isha Save Soil Movement, active in Tamil Nadu for nearly three decades.
- Focus Areas: Revitalising soil health. Promoting natural farming. Enhancing farmers’ livelihood. Ensuring toxin-free food for all.
- Enhancing farmers’ livelihood.
- Encourages agripreneurship and innovation in farming.
Urea and Its Role in Agriculture
- Urea is a nitrogen-rich chemical fertilizer (46% nitrogen content – the highest among solid nitrogenous fertilizers).
- Subsidy Burden: Heavy government subsidy (₹2 lakh crore+ annually) makes it prone to diversion and black marketing.
- Neem-coated Urea (2015): Made mandatory to reduce misuse and improve efficiency.
- Cost-effective: Due to government subsidies, urea is the cheapest source of nitrogen for farmers.
Bayer Launches Camalus Insecticide for Indian Horticulture
- Benefits: Reduces frequent spray cycles and lowers input costs. Compatible with Integrated Pest Management (IPM); minimizes harm to beneficial insects. Enhances leaf penetration for consistent performance even in adverse weather.
- Reduces frequent spray cycles and lowers input costs.
- Enhances leaf penetration for consistent performance even in adverse weather.
Fortified Rice Scheme
- National Rollout: 2022 for universal coverage.
- Universal Coverage: Normal rice replaced by fortified rice in all central schemes by March 2024.
- Union Cabinet (Aug 2025) approved universal supply of fortified rice under all government schemes till December 2028.
- Objective: Address anaemia, malnutrition, and hidden hunger by adding Iron, Folic Acid, and Vitamin B12 to rice.
VOPPA Regulation Order, 2025
- Monthly Reporting Requirements Registered producers must file detailed monthly reports (by the 15th) on production, stocks, sales, and usage. This tightens supply chain tracking and helps maintain fair retail prices.
- Registered producers must file detailed monthly reports (by the 15th) on production, stocks, sales, and usage. This tightens supply chain tracking and helps maintain fair retail prices.
- On August 1, 2025, the Government of India unveiled the Vegetable Oil Products, Production and Availability (VOPPA) Regulation Order, 2025, replacing the 2011 framework under the Essential Commodities Act, 1955. This policy aims to improve oversight and transparency in the edible oil sector, a critical commodity in India's food supply chain.
- Mandatory Producer Registration All vegetable oil producers must now register with the Directorate of Sugar and Vegetable Oils in New Delhi, submitting details such as factory location and production capacity.
Union Government Launches Pilot Project to Boost Fisheries in Kuttanad, Kerala
- Objective: Enhance income and livelihood for fish farmers in Kuttanad.
- Aim to empower small and marginal fish farmers by pooling resources and providing collective bargaining power.
- Formation of Fish Farmers Producers Organizations (FFPOs) to empower local communities and streamline operations.
- FFPOs are collectives of fish farmers, structured as companies, where members come together to improve production, marketing, and income.
Beyond Irrigation: Why India Needs Water Intelligence, Not Just Water Access
- Climate Variability: Erratic rainfall patterns worsen water scarcity and affect farm incomes.
- Monitoring & Data Collection: Real-time soil moisture, weather, and water use data through sensors, drones, and IoT devices.
- Cost Efficiency: Lowers water and energy costs for farmers while maintaining yields.
SAMARTH Mission (Sustainable Agrarian Mission on Use of Agri Residue in Thermal Power Plants)
- Launched: 2021
- Implementation Mechanism: Steering Committee: Chaired by the Secretary, Ministry of Power, to monitor and resolve inter-ministerial issues. Market Development: Long-term and short-term tenders for biomass supply.
- It aims to reduce stubble burning, decrease carbon emissions, and provide additional income to farmers by utilizing agricultural waste.
- Create a biomass market, encouraging farmers and entrepreneurs.
Financial Assistance in Agriculture
- Direct Income Support: PM-Kisan provides ₹6,000 annually to eligible farmers.
- Acts as a lifeline for farmers by addressing liquidity issues during sowing, harvesting, and marketing.
- Helps in adopting modern technologies, quality seeds, fertilizers, irrigation, and mechanization.
- Subsidies: For seeds, fertilizers, irrigation, power, machinery, and crop diversification.
1. ________: Allowed diverse feedstocks, including sugarcane juice, FCI surplus grains, rotten potatoes, etc.
2. ________: Governs all aspects of pesticide lifecycle.
3. The Union Cabinet has approved a new Central Sector Scheme titled ________, with a total outlay of ₹2,000 crore for four years (FY 2025–26 to FY 2028–29).
4. NABARD sanctioned ________ for a six-year tribal development project in Buttayagudem and Polavaram mandals, Eluru district.
5. Researchers sequenced genomes of ________.
Facts To Remember · 50
PM Modi to disburse ₹20,500 cr under PM-KISAN scheme in Varanasi
- Prime Minister Narendra Modi will visit his parliamentary constituency, Varanasi, tomorrow to lay the foundation stone and inaugurate the development projects worth around 2,200 crore rupees. On this occasion, PM Modi will also address a public gathering.
Cabinet approves ₹6,520 crore outlay for Pradhan Mantri Kisan Sampada Yojana
- The Cabinet has approved a total outlay of 6520 crore rupees, including additional outlay of 1920 crore rupees for ongoing Central Sector Scheme “Pradhan Mantri Kisan Sampada Yojana” during 15th Finance Commission Cycle.
4 astronauts from US, Japan, Russia successfully dock at space station: NASA
- Four astronauts from the United States, Japan, and Russia have successfully reached the International Space Station (ISS) as part of NASA’s Crew-11 mission.
Less than 15% Youth Skilled under PMKVY Secured Jobs, Reveals Govt Data
- Despite sustained efforts under the Pradhan Mantri Kaushal Vikas Yojana (PMKVY) to address youth unemployment in India, the latest government data indicates that less than 15% of those trained since 2015 have secured job placements. The data was shared by Skill Development Minister Jayant Chaudhary in a written reply to the Lok Sabha.
PM Matru Vandana Yojana Registration Drive Extended Till August 15
- The Ministry of Women and Child Development has extended the special registration drive for the Pradhan Mantri Matru Vandana Yojana (PMMVY) till the 15th of this month.
Govt. can issue national IDs to citizens: Centre
- The Lok Sabha was recently informed that the Citizenship Act, 1955 provides that the Union government should compulsorily register every citizen of India and issue national Identity Cards to them.
IRCTC Receives RBI Nod to Operate as Payment Aggregator
- On 4 August 2025, the Reserve Bank of India (RBI) granted in-principle authorization to IRCTC Payments Limited—a wholly-owned subsidiary—to operate as an online payment aggregator (PA) under the Payment and Settlement Systems Act, 2007.
Donald Trump doubles India tariff to 50% over Russian oil purchase
- US President Donald Trump on Wednesday signed an executive order doubling India tariff to 50 per cent, announcing an additional 25 per cent duties over Russian oil purchase, according to the White House website.
ChatGPT 5
- OpenAI has officially launched ChatGPT 5, the newest version of its advanced AI chatbot, bringing significant upgrades that are already generating buzz.
India’s bid to host 2036 Olympics in ‘continuous dialogue’ phase
- India’s bid to host the 2036 Olympics is in the “continuous dialogue” phase with the International Olympic Committee’s Future Host Commission, Sports Minister Mansukh Mandaviya told the Lok Sabha.
IIST–KAU Post-Flight Seed Study after ISS Mission
- The Indian Institute of Space Science and Technology (IIST) and Kerala Agricultural University (KAU) have initiated research on crop seeds sent to the International Space Station (ISS) during the Axiom-4 mission. The study aims to assess the effects of space exposure on seed germination, growth, and productivity.
Bond Market Selloff Continues Despite Retail Inflation Hitting 8-Year Low
- The Indian bond market witnessed continued selling pressure on 12 August 2025, even as retail inflation hit its lowest level in eight years. Government bond yields surged due to stop-loss triggers and higher-than-expected state development loan (SDL) cut-off yields.
PM addresses the 18th International Olympiad on Astronomy and Astrophysics
- India is hosting the 18th International Olympiad on Astronomy and Astrophysics (IOAA) in 2025, welcoming over 300 young astronomers from 64 countries.
ICICI Bank trims S/B minimum balance to ₹15,000 from ₹50,000
- In a U-turn, ICICI Bank has slashed the minimum monthly average balance (MAB) requirement to ₹15,000 from the earlier steep hike to ₹50,000, citing “valuable feedback” from customers.
Keymer remains undefeated; Pranesh wins Challengers crown
- German Vincent Keymer capped a memorable triumph in the Quantbox Chennai Grandmasters chess tournament 2025 with a convincing win in the final round of the Masters section over American GM Ray Robson.
AU Small Finance Bank to open 51 branches on Independence Day ahead of universal bank transition
- AU Small Finance Bank is expanding its branch network in preparation for its conversion into a Universal Bank. It will launch 51 branches across the country on August 15, 2025, coinciding with India’s 79th Independence Day.
One-time online registration for PMVBRY opens
- The Pradhan Mantri Viksit Bharat Rozgar Yojana (PMVBRY) portal under the Pradhan Mantri Viksit Bharat Rozgar Yojana has gone live. The scheme will provide incentive of up to 15 thousand rupees in two instalments to newly employed youth and upto three thousand rupees per month per new employee to employers for creation of new job opportunities.
Rajya Sabha passes Indian Ports Bill
- The Rajya Sabha passed the Indian Ports Bill, 2025, that replaces the Indian Ports Act of 1908.
Bengal CM announces scheme for migrant workers facing harassment
- West Bengal Chief Minister Mamata Banerjee announced a new scheme to provide monthly cash incentives to migrant workers who return to the State after facing harassment in other States.
23% of PM Jan Dhan accounts inoperative
- As many as 23% of the total 56.04 crore Pradhan Mantri Jan Dhan Yojana (PMJDY) accounts are inoperative, said Minister of State for Finance Pankaj Chaudhary.
Bank of Maharashtra and SBI Card Launch Co-Branded Credit Card
- On August 19, 2025, Bank of Maharashtra (BoM) and SBI Card jointly launched the “Bank of Maharashtra SBI Card” in three variants to offer enhanced value, convenience, and lifestyle benefits to customers.
Unemployment Rate Declines to 5.2% in July: PLFS Data
- The Periodic Labour Force Survey (PLFS) released by the Ministry of Statistics and Programme Implementation (MoSPI) on 18 August 2025 shows that India’s unemployment rate has fallen, with notable improvements in rural employment indicators.
Rajya Sabha Clears Mines and Minerals (Development and Regulation) Amendment Bill, 2025
- The Rajya Sabha passed the Mines and Minerals (Development and Regulation) Amendment Bill, 2025, following its passage in the Lok Sabha on August 12, 2025. The Opposition staged a walkout, citing procedural concerns.
21.89 lakh net additions to EPFO in June, says govt.
- The Union Labour Ministry said that the Employees’ Provident Fund Organisation (EPFO) registered a net member addition of 21.89 lakh in June – the highest since tracking of payroll data began in April 2018. Compared with May, net payroll additions increased 9.14%, and vis-a-vis June 2024, the growth is 13.46%.
RBI gets bids of ₹ 31K cr in ₹ 50K cr VRR auction
- The Reserve Bank of India (RBI) received bids worth ₹ 31,025 crore at the overnight variable rate repo (VRR) auction on Thursday against the notified amount of ₹ 50,000 crore, which the experts said was on expected lines.
APEDA opening new offices at Patna, Raipur, Dehradun
- The commerce ministry's arm, Agricultural and Processed Food Products Export Development Authority (APEDA), has decided to open its three new regional offices in Patna, Dehradun and Raipur to support agri exporters, an official said.
World Orangutan Day August 19th
- World Orangutan Day is a global event that takes place on the 19th of August every year. It’s an opportunity to show off just how spectacular these animals really are and to raise awareness of the dangers they face.
40% of Chief Ministers face criminal cases: ADR report
- Of the 30 Chief Ministers in the country, 12 of them, or 40%, declared criminal cases against themselves, according to a new report by poll rights body Association for Democratic Reforms.
Elavenil shoots her way to air rifle gold
- Elavenil Valarivan battled the Chinese and Koreans efficiently to bag the women’s air rifle gold with a 0.6 point margin over Peng Xinlu in the 16th Asian shooting championship in Shymkent on Friday. It was the second Asian championship individual gold for the 26-year-old , following the first in 2019.
Priya claims silver and Suraj bronze in World u-20 wrestling
- Priya Malik, a World under-20 champion in 2023, clinched the silver medal after being pinned by European World under-20 champion Nadiia Sokolovska in the women’s 76kg final at the World under-20 wrestling in Samokov.
Great Nicobar Project
- The ₹72,000-crore Great Nicobar Island Project — comprising a transshipment port, airport, power plant, and township — faces renewed opposition from the Nicobarese Tribal Council. The council has accused the Andaman & Nicobar Islands (A&NI) administration of falsely certifying compliance with the Forest Rights Act (FRA), 2006, to secure forest clearances for the mega project.
4th Semicon India 2025 to be organised from Sept 2
- Prime Minister Narendra Modi will inaugurate the fourth edition of Semicon India 2025 in New Delhi on 2nd September. The three-day event aims to showcase the country’s growing capabilities and ambitions in the microelectronics and semiconductor value chain.
National Space Day being celebrated across the country today
- The second National Space Day is being celebrated across the country today. The day commemorates the successful soft landing of the Chandrayaan-3 Mission’s Vikram Lander and the deployment of the Pragyan Rover on the Moon on 23rd of August 2023.
India sweeps mixed air rifle gold medals
- It was a sweep of the air rifle mixed team gold medals for India as it won the three events, including juniors and youth, in the 16th Asian shooting championship in Shymkent, Kazakhstan.
Chikitha, Sharvari strike gold
- Chikitha Taniparthi became the first Indian compound archer to win the women’s under-21 individual title at the World youth archery championships in Winnipeg, Canada.
RBI Approves SMBC to Acquire up to 24.99% Stake in Yes Bank
- The Reserve Bank of India (RBI) has granted approval to Sumitomo Mitsui Banking Corporation (SMBC) to acquire up to 24.99% stake in Yes Bank.
Minister Raksha Khadse Inaugurates ‘Giving Wings to Dreams Conclave 2025’
- Minister of State for Youth Affairs and Sports Raksha Nikhil Khadse today inaugurated the ‘Giving Wings to Dreams Conclave 2025’ in New Delhi.
Launch of Maruti Suzuki’s First Made-in-India Battery Electric Vehicle (BEV) – e Vitara
- Maruti Suzuki has commenced production of its first Battery Electric Vehicle (BEV), e Vitara, at its Suzuki Motor Gujarat Private Ltd. plant. The first batch will be exported to Europe in August 2025, marking India’s entry into mass-scale electric vehicle exports.
Nabfid & Nabard Plan Overseas Fundraising by FY26
- The National Bank for Financing Infrastructure and Development (Nabfid) and the National Bank for Agriculture and Rural Development (Nabard) are preparing to tap international debt markets for the first time by FY26 to diversify funding sources and meet long-term financing needs.
AIBOC opposes plan of central govt to privatise IDBI Bank
- TheAll-India Bank Officers Confederation has come out strongly against the Centres plan to privatise IDBI Bank, warning that such a step would undermine social justice, financial inclusion, and the countrys economic sovereignty.
Mizoram Assembly passes Bill to prohibit beggary
- The Mizoram Assembly on Wednesday (August 27, 2025) passed a Bill to prohibit beggery in the state amidst objections by opposition members.
India set to finalise General Electric deal for LCA Mark 1A engines
- Soon after the government cleared the ₹62,000-crore order for 97 additional LCA Tejas Mark 1A fighter jets, India is close to finalising a deal worth about $1 billion with U.S. firm General Electric (GE) for 113 GE-404 engines to power the indigenous aircraft.
‘India set to be 2nd-largest economy’
- India’s economy could reach $20.7 trillion in terms of purchasing power parity by 2030 and may emerge as the second-largest economy by 2038 with $34.2 trillion gross domestic product (GDP), an EY report said.
PM Modi to Engage Global Shipping CEOs at India Maritime Week 2025
- India is preparing to host India Maritime Week in October 2025, aimed at attracting significant investments in shipping, ports, and shipbuilding sectors.
CM launches regional version of Gujarat global summit
- Chief Minister Bhupendra Patel launched a regional version of the Vibrant Gujarat Global Summit with a focus on highlighting the strengths of each region to promote local products at international, national levels and also seek investment in districts.
India hosts international meeting on military medicine
- Union Minister of State for Defence Sanjay Seth on Thursday inaugurated “MILMEDICON-2025: international conference on physical and mental trauma in military settings” at Manekshaw Centre, New Delhi.
Nearly 60% of MGNREGS budget already spent in first 5 months of financial year
- Nearly 60% of the budget allocated for the Union government’s flagship rural employment programme — Mahatma Gandhi National Rural Employment Guarantee Scheme (MGNREGS) — has been exhausted with a month still left to go for the second quarter to end.
Gujarat to host 70th edition of Filmfare 2nd year in a row
- Gujarat will host the 70th Filmfare Awards for the second consecutive year, with the state govt on Thursday inking an MoU with Worldwide Media.
Mobile-Aadhaar Link Shields PMJDY Accounts from Fund Diversion
- On the 11th anniversary of the Pradhan Mantri Jan Dhan Yojana (PMJDY), the government highlighted that linking Jan Dhan accounts with mobile numbers and Aadhaar has created a diversion-proof system for subsidy and benefit transfers.
Agriculture & Allied GVA Growth Q1FY26
- Agriculture sector GVA grew 3.7% in Q1FY26 versus 1.5% last year. Growth reflects rabi harvest impact; kharif effects will be seen in Q2/Q3.
1. On August 19, 2025, Bank of Maharashtra (BoM) and SBI Card jointly launched the ________ in three variants to offer enhanced value, convenience, and lifestyle benefits to customers.
2. India is preparing to host ________ in October 2025, aimed at attracting significant investments in shipping, ports, and shipbuilding sectors.
3. The ________ the Mines and Minerals (Development and Regulation) Amendment Bill, 2025, following its passage in the Lok Sabha on August 12, 2025. The Opposition staged a walkout, citing procedural concerns.
4. Philippines President Ferdinand R. Marcos Jr. began his ________ on Monday, marking a significant diplomatic and strategic engagement between the two Indo-Pacific nations.
5. The government is finalising rules for private sector access to the ________ portal — a digital platform aimed at transforming infrastructure planning and execution in India.
Awards · 1
71st National Film Awards 2023
- Note: First National Award for both actors
- Note: First National Award for Rani Mukerji
- The 71st National Film Awards, recognising excellence in Indian cinema for the year 2023, were announced. The honours celebrated both seasoned actors and emerging talent across multiple languages and genres, reflecting the depth and diversity of Indian filmmaking.
- Winner: 12th Fail (Hindi)
Science & Tech · 1
ICMR Launches Portable Brain Injury Diagnostic Device ‘CEREBO’
- Features: Detects intracranial bleeding and edema in under a minute. Radiation-free, low-cost, and colour-coded results. Safe for infants and pregnant women. Operable by paramedical staff/unskilled personnel after 30 minutes of training.
- Operable by paramedical staff/unskilled personnel after 30 minutes of training.
- Technology: Uses near-infrared spectroscopy (NIRS) powered by machine learning.
Swipe for all 5 courses →